
How New Wafer ID System At Cognex (CGNX) Has Changed Its Investment Story
- Cognex recently introduced the In-Sight 1750 Series, a wafer and panel identification platform that combines AI, advanced imaging, and tailored illumination to read difficult semiconductor marks and support web-based setup and read logging.
- The system is designed to slot into existing wafer ID workflows with job conversion and upgrade support. This could influence Cognex’s ability to deepen relationships with current semiconductor customers while limiting disruption and retraining costs.
- The next step is to examine how Cognex’s investment narrative could be affected by this AI-powered wafer identification launch in semiconductors.
Scan beyond Cognex and this single product launch by reviewing a hand picked group of 93 robotics and automation stocks that are also wiring AI into factory floors and inspection lines.
Cognex Investment Narrative Recap
Cognex appeals to investors who think AI vision will keep gaining share in factories, logistics hubs, and semiconductor fabs. The core belief is that higher value software, cloud tools, and smarter sensors can support margins even as basic hardware faces price pressure. The In Sight 1750 launch fits that story but does not change it.
The key short term swing factor still looks tied to capital spending in cyclical areas like automotive and chips. Risk sits on the other side of that same coin. If competition in lower cost regions keeps pushing pricing down, or if customers delay upgrades, the new product family alone may not offset margin pressure.
Among recent developments, the In Sight 1750 announcement is the clearest operational data point for that semiconductor catalyst. It underscores how Cognex is trying to push more AI into specific workflows where traceability and uptime really matter, rather than relying only on generic machine vision hardware.
For you as a shareholder, the practical question is execution. Can management turn that AI heavy product into wider adoption that supports utilization and reduces customer churn in a shaky chip cycle? If they fall behind faster moving rivals or struggle to migrate users from older systems, the long term software heavy narrative could be slower to play out.
Cognex's current earnings are reported at US$174.8 million, and analysts forecast consensus earnings of US$373.0 million by 2029. This implies an earnings increase of about 2.1x and assumes revenue growth of 9.6% per year, with revenues projected to reach US$1.4b by that same year.
Uncover why Cognex's fair value indicates a 37% potential upside to its current price before the market closes the gap.
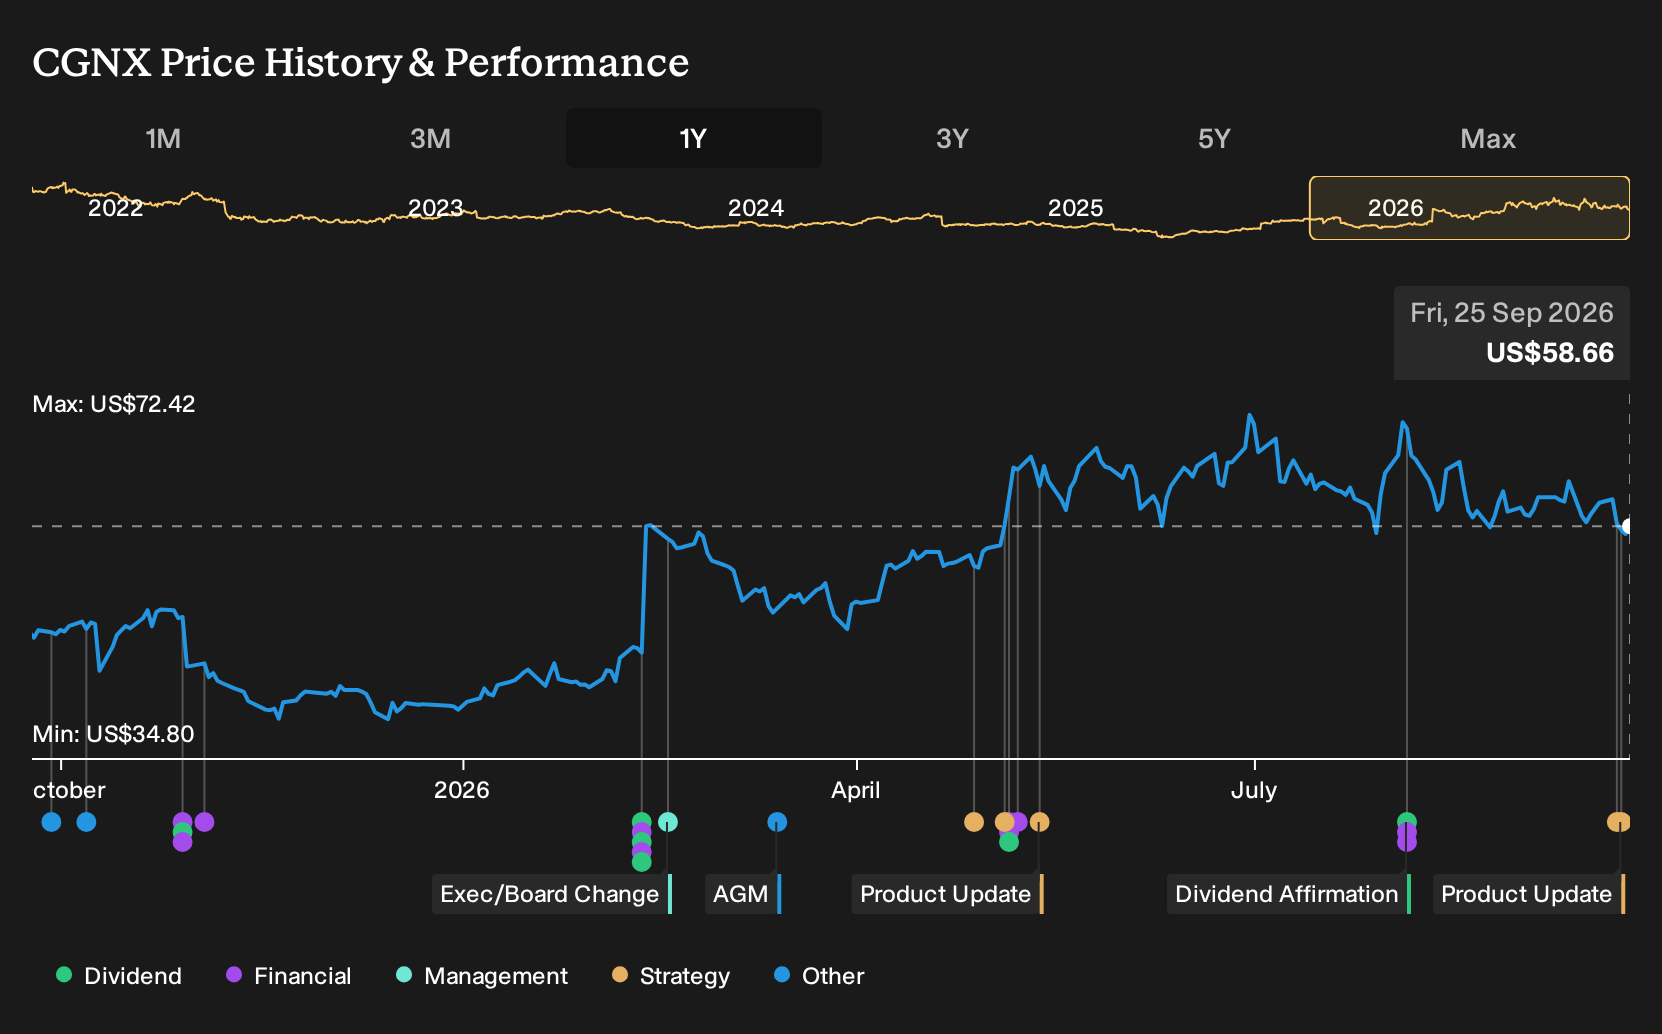
Exploring Other Perspectives
One alternate view focuses on upside from aggressive AI adoption. The most optimistic analysts were already modeling revenue growth of 10.9% a year and earnings of US$456.2 million by 2029 for Cognex, compared with US$142.5 million today. Those forecasts came before this wafer ID announcement, so expectations on that side could climb further or be reassessed.
Explore 5 other Cognex fair value estimates, including one that suggests up to 55% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cognex research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cognex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cognex's overall financial health at a glance.
Looking For More Ideas Beyond Cognex?
Once you are comfortable with where Cognex fits in your portfolio, it can help to widen the lens and scan for other businesses with different risk, income, and quality profiles using the Simply Wall St screener.
- For investors hunting for potential mispricing, review a curated 32 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- If capital preservation matters most to you, filter for 30 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- Those looking for resilient income streams can focus on 8 dividend fortresses that pair higher yields with supporting cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com