
How Major USCENTCOM Contract At CACI International Stock Has Changed Its Investment Story
- CACI International reported a major multi-year award to support U.S. Central Command with planning, analysis, information integration, and mission execution across its area of responsibility, with a ceiling of US$1,500 million and an expected US$1,200 million to be booked by the company.
- The USCENTCOM contract underscores how CACI International’s Apollo capabilities are being applied to complex irregular warfare and information environment missions. This reinforces the company’s focus on higher-value defense technology work within its broader services portfolio.
- We will now examine how CACI International’s large USCENTCOM award could reshape the existing investment narrative around defense technology.
CACI International Investment Narrative Recap
For a shareholder in CACI International, the core belief is that the business converts its record contract backlog and defense tech focus into steadier margins and cash generation. The USCENTCOM award and the Vantor Pulse work both point toward longer duration programs. The near term swing factor remains execution on these complex contracts, not just winning them.
The biggest risk is that higher capital spending and integration costs do not translate into stronger free cash flow, especially with debt not well covered by operating cash flow. The recent awards are sizable but do not yet change that cash conversion question in a clear, near term way.
The Vantor Pulse satellite announcement is the clearest link to CACI International’s push in space and defense technology. Providing optical imaging payloads for a planned 24 satellite fleet directly ties into its broader effort to grow higher value tech work, including electronic warfare, counter UAS, and space programs already highlighted in its pipeline.
For catalysts, this type of commercial adjacent satellite work can help diversify revenue beyond traditional contracts and support better use of in house manufacturing capacity. Execution risk is real, given payload performance, integration, and deployment timelines stretching from 2027 to 2029, so investors will likely watch milestones and any impact on margins and free cash flow closely.
CACI International Consensus Forecasts In Context
CACI International's consensus narrative points to revenue of US$12.2b and earnings of US$727.8m by 2029. That profile assumes 8.3% yearly revenue growth and an earnings increase of about US$192m from US$535.8m today.
Uncover why CACI International's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
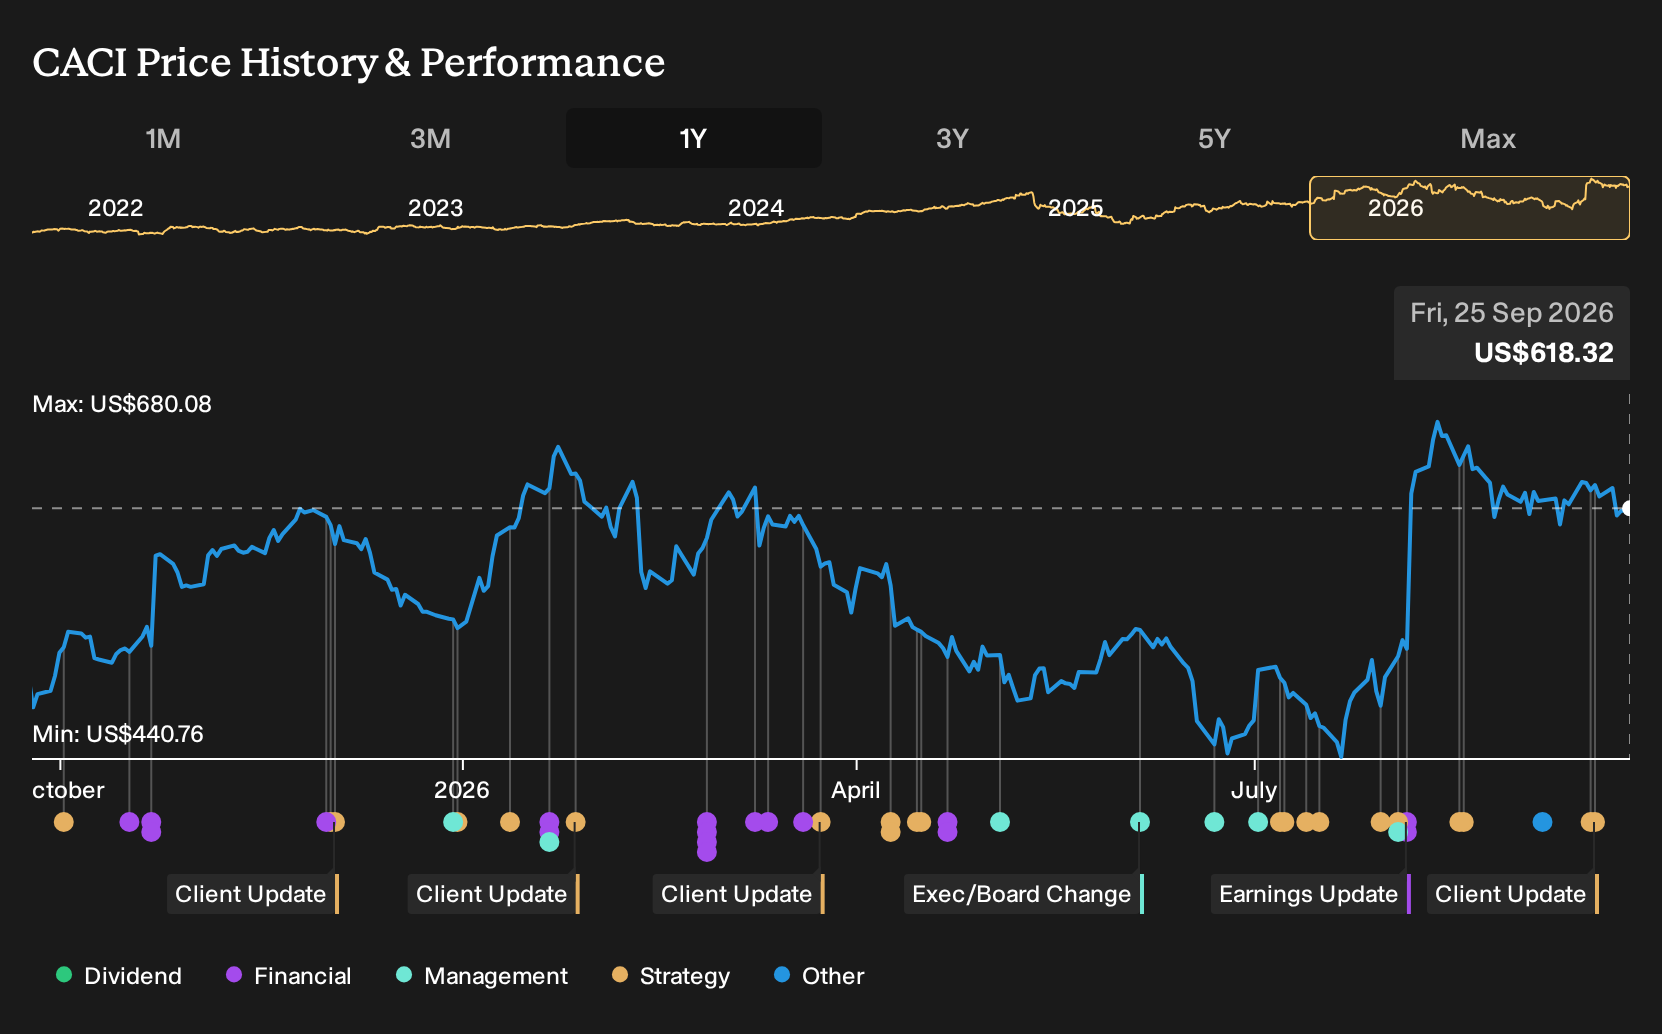
Exploring Other Perspectives
One alternate view puts contract concentration front and center. The most cautious CACI International analysts were modeling 7.0% annual revenue growth to about US$11.7b and earnings of roughly US$616.7m by 2029, before this USCENTCOM and Vantor news. That is a more pessimistic narrative. Opinions clearly differ, so consider several viewpoints before deciding what this new information might mean for you.
Explore 3 other CACI International fair value estimates, including one that suggests it could be worth just $735.21.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CACI International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CACI International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CACI International's overall financial health at a glance.
Looking For More Investment Ideas Beyond CACI International?
Once the CACI International story is clear, casting a wider net can help you build a watchlist that fits your own risk, income, and quality preferences. The Simply Wall St Screener lets you filter for exactly the kind of businesses you want to study next.
- Hunting for overlooked quality with strong fundamentals and room to grow? Start with a curated set of 16 high quality undiscovered gems that share similar resilience characteristics.
- If capital preservation matters just as much as upside, you can review a basket of 30 resilient stocks with low risk scores that screen well on financial strength and business stability.
- Income focused investors who want potential yield alongside staying power can review a focused group of 8 dividend fortresses to see which cash payers line up with their goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com