
How Investors Are Reacting To Piper Sandler (PIPR) Higher Fed Rates
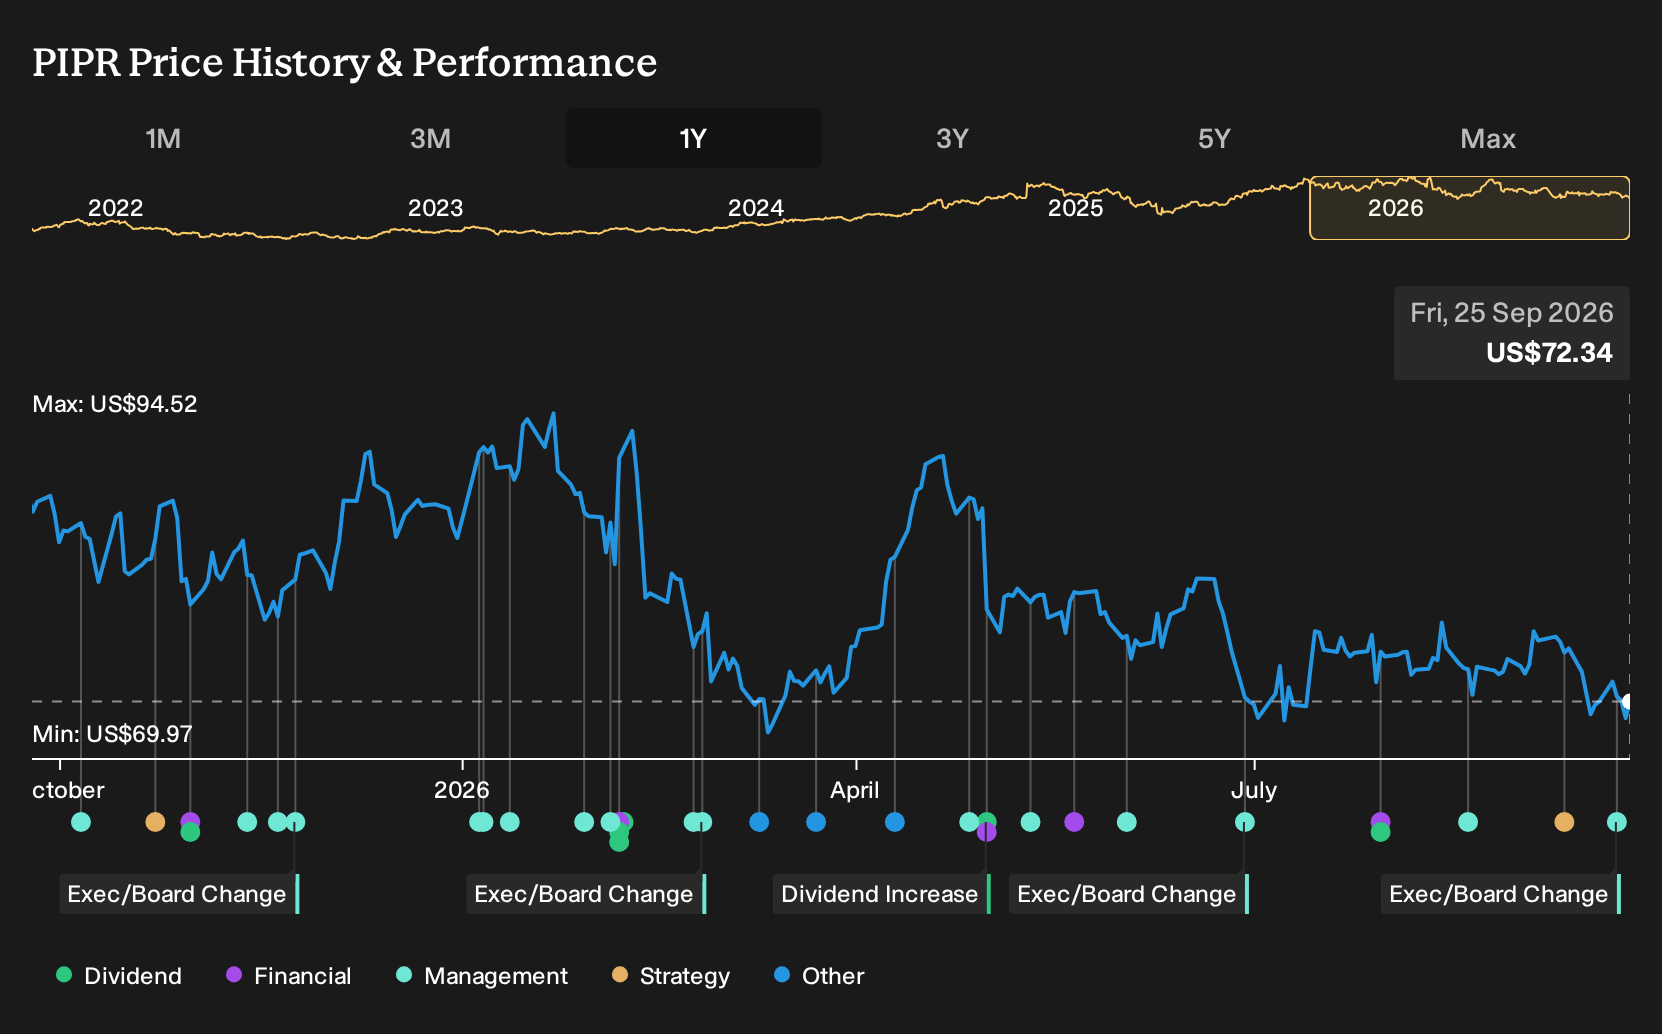
- Piper Sandler Companies recently appointed Wendy L. Schoppert to its board of directors, adding executive, finance and technology experience built across Sleep Number, U.S. Bank and several major corporate boards.
- The appointment brings a mix of CFO, CIO and international expansion experience that could inform how Piper Sandler manages technology spending, balance sheet risk and diversification of revenue streams.
- We will now examine how Piper Sandler Companies' investment narrative could be affected by higher Federal Reserve interest rates on capital markets.
Scan beyond Piper Sandler Companies and stress test your playbook for higher rates with a curated list of 30 resilient stocks with low risk scores that may handle tighter credit conditions more defensively.
Piper Sandler Companies Investment Narrative Recap
To own Piper Sandler Companies, you need to be comfortable with an investment bank whose fortunes are closely tied to deal activity, equity issuance, municipal financing and trading volumes, all of which are sensitive to higher Federal Reserve rates. The addition of Wendy Schoppert does not materially change the near term swing factors, which still hinge on capital markets staying open and active.
The biggest near term catalyst remains execution on advisory pipelines across bank consolidation, health care, biotech and public finance. The key risk is that tighter credit and higher funding costs curb private equity activity and municipal refundings. Board refreshment helps governance and oversight, but operational momentum still depends on client transaction follow through.
The new board appointment is the most relevant development here. Schoppert brings prior CFO and CIO experience plus time in banking and consumer facing sectors. That mix could support board level oversight of technology spend, risk management and capital allocation as Piper Sandler Companies continues to invest in sector coverage and balance compensation against revenue cycles.
Her background in international expansion and across multiple corporate boards may also be useful as management pursues opportunities in private credit, restructuring and sector focused capital markets work. Those areas are important to the firm’s diversification efforts but remain exposed to deal flow risk if higher borrowing costs keep private transactions and exits subdued.
Piper Sandler Companies' narrative projects US$2.6b revenue and US$449.4 million earnings by 2029. This assumes 8.5% yearly revenue growth and an earnings increase of about US$167.7 million from US$281.7 million today.
Uncover why Piper Sandler Companies' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$33.5 to US$88.1, so retail opinions on Piper Sandler Companies are already wide apart. Those views pre date Wendy Schoppert’s appointment and the latest Fed rate hike, so investors may wish to reassess board changes, deal pipelines and higher funding costs before leaning on any single valuation.
Explore 2 other Piper Sandler Companies fair value estimates, including one that suggests as much as 54% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Piper Sandler Companies research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Piper Sandler Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Piper Sandler Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Piper Sandler Companies?
Once you have a view on Piper Sandler Companies, it can help to compare that thesis against other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you a quick way to scan for businesses that match the kind of portfolio you want to build, not just the headline story that is in front of you today.
- If capital preservation sits high on your list, review a curated list of solid balance sheet and fundamentals (24 results) that may offer sturdier financial footing when conditions tighten.
- If you are hunting for potential mispricing, check a focused set of 31 high quality undervalued stocks that combine fundamental strength with pricing that may not fully reflect it.
- If your priority is recurring income, scan through a group of 8 dividend fortresses that pair higher yields with an eye on payout resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com