
Did Banking Tie Up Just Shift AppFolio (APPF) Investment Narrative?
- AppFolio announced an exclusive partnership with Column N.A., Member FDIC, integrating Column’s banking technology into the AppFolio Performance Platform to support more integrated financial operations for property managers.
- The collaboration ties AppFolio’s real estate data and AI workflows directly into a bank core and payments stack, which could sharpen its ability to offer deeper, higher value financial services inside the existing property management workflow.
- We will now assess how AppFolio’s tighter integration of banking capabilities with Column could influence the strength of its long-term investment narrative.
Scan how AppFolio’s banking tie up fits into a broader theme and shortlist other subscription driven platforms with potential for resilient cash flows using our hand picked list of solid balance sheet and fundamentals (24 results).
AppFolio Investment Narrative Recap
To own AppFolio, you need to believe its subscription platform can keep winning property managers who want automation across accounting, leasing, and payments, while AI tools drive better productivity for customers. The Column partnership sits squarely in that thesis. It tightens the link between operational workflows and money movement, which can support engagement and adoption if execution goes smoothly.
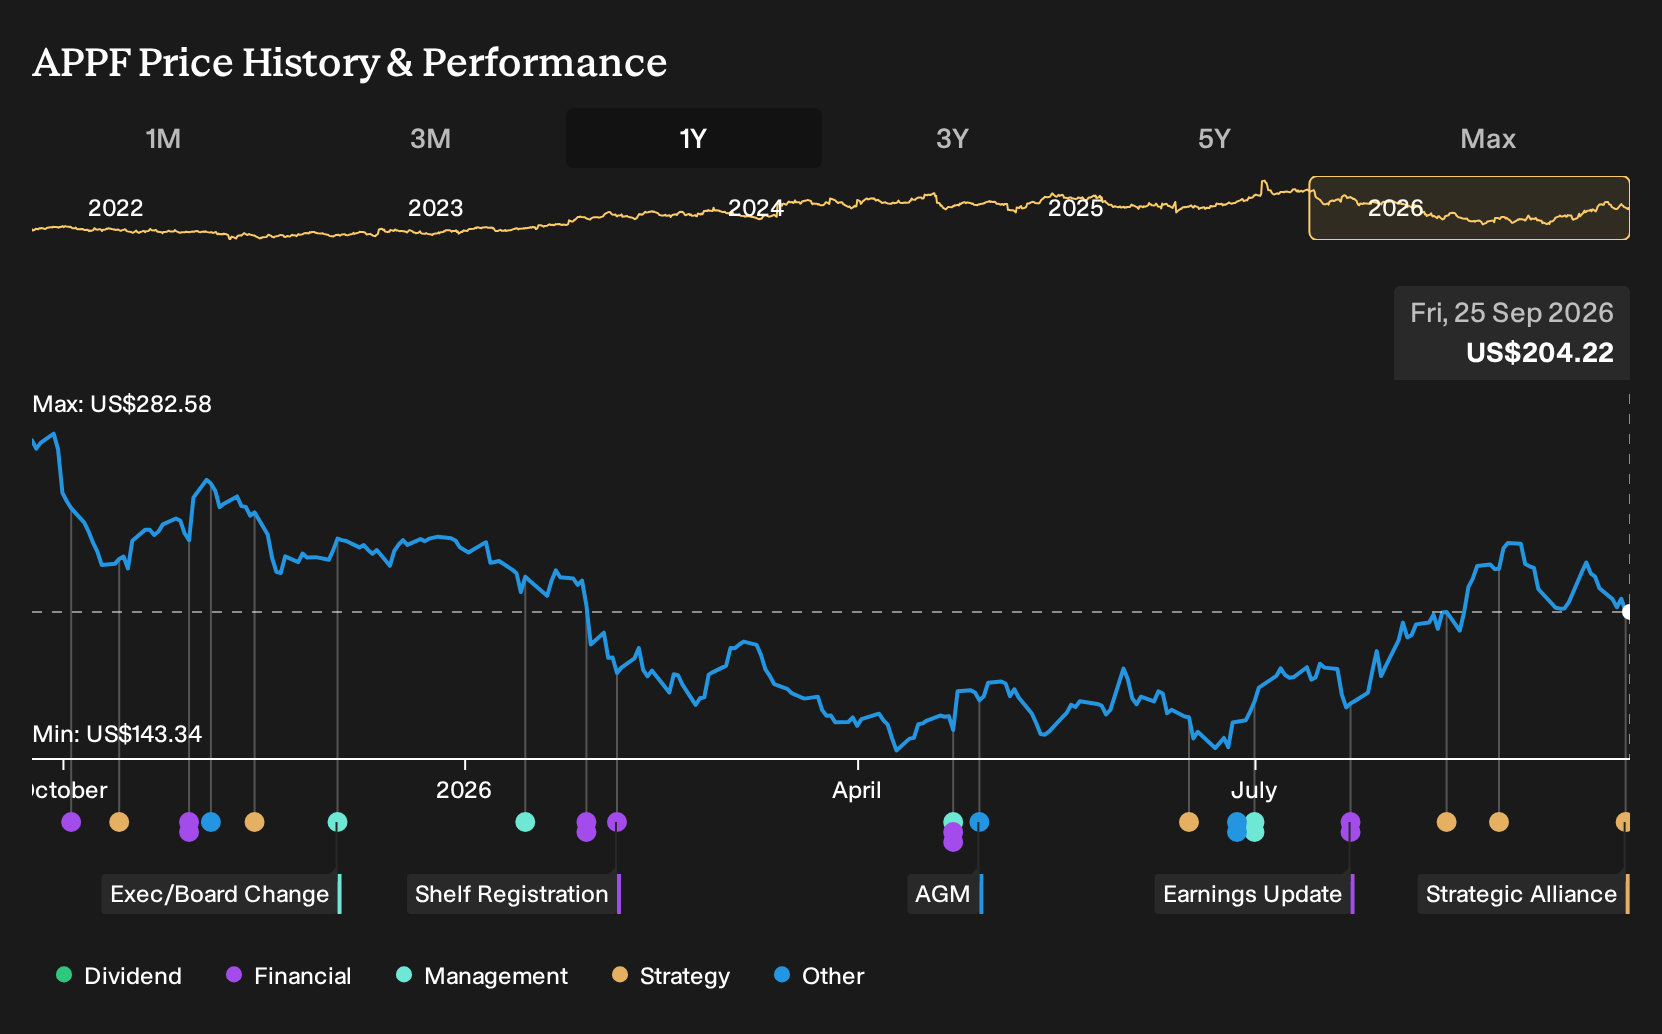
The near term focus stays on upcoming earnings and whether unit growth and value added services keep pace with expectations after a recent share price pullback. The biggest risk is that competition and pricing pressure in property management software, including rival AI offerings, slow customer additions or compress margins faster than AppFolio can offset with new products and banking integrations.
The Column N.A. partnership is the announcement that matters most here. AppFolio is wiring its real estate data and AI workflows into Column’s bank core and payments stack. That could make rent collection, reconciliations, and ledger management feel closer to a single system for customers rather than a patchwork of software and separate banking tools.
If property managers adopt these embedded banking features at scale, the deal could support two important catalysts for AppFolio. It can deepen platform stickiness as customers rely more on integrated payments, and it can expand usage of higher margin financial services. The flip side is greater dependence on a single banking partner, which raises third party and regulatory risk that investors need to keep front of mind.
AppFolio's current narrative points to revenues of $1.6b and earnings of $275.8m by 2029, based on analyst models that assume 16.3% yearly revenue growth and a move from $152.0m in earnings today to that 2029 consensus figure, an increase of about 1.8x.
Discover why AppFolio's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle puts margin pressure at the center of the AppFolio story. The most cautious analysts worry that big partnerships and AI spending could weigh on profitability, even as they still model about $1.7b of revenue and $302.1m of earnings by 2029. Those forecasts were set before this Column news, so views may shift.
Explore 5 other AppFolio fair value estimates, including one that suggests it could be worth just $200.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AppFolio research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AppFolio. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AppFolio's overall financial health at a glance.
Looking For More Investment Ideas Beyond AppFolio?
If the AppFolio story has you thinking about where else resilient cash flow models or strong balance sheets might show up, the Simply Wall St Screener can help you quickly surface a wider watchlist that fits your own risk and income preferences.
- For investors who like the idea of paying less for quality, scan a focused group of potential value opportunities through the 31 high quality undervalued stocks.
- If dependable income is a priority, check out companies in the 8 dividend fortresses that combine higher yields with an emphasis on durability.
- When you want to cast the net a bit wider and look for potential future winners before they are widely followed, filter for under-the-radar opportunities with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com