
Emerson Electric (EMR) Stock Looks Above Fair Value Despite Qatar Service Center Plans
Emerson Electric has ridden a strong multi year run and a fresh burst of buying interest, which puts a bright spotlight on whether its current share price still lines up with the earnings that support it. With the stock recently closing at US$158.23, the key issue is how much of the business's profit power the market is already banking in.
- Over the past 5 years the stock has returned 83.6%, which raises the question of how much future earnings strength is already embedded in that climb.
- The plan to build a new automation solutions service center in Qatar may support expectations for future revenue and cash flow from Emerson Electric's Middle East and Africa operations.
- The analysts covering Emerson Electric have run their own numbers. See what analysts think Emerson Electric's shares could be worth.
The issue now is whether the earnings that Emerson Electric generates today are enough to justify this share price or whether the recent performance has moved ahead of what the business is currently producing.
If you want a reference point for Emerson Electric's recent run and earnings focus, it can help to line it up against companies in 39 power grid technology and infrastructure stocks
Has Emerson Electric Run Too Far on Earnings?
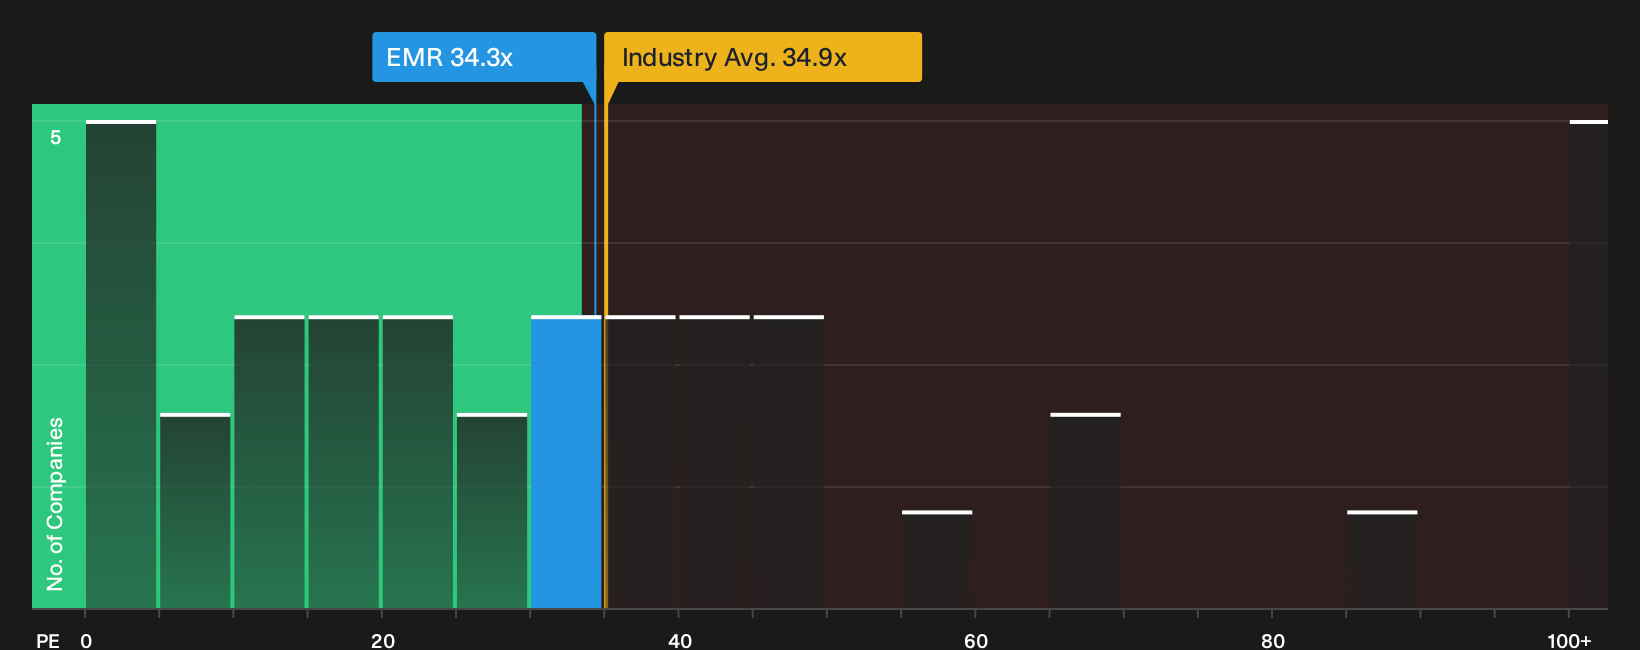
The P/E ratio is a useful lens for Emerson Electric because earnings remain the central anchor for how this industrial group is priced. At a P/E of 34.3x, the stock trades very close to the broader Electrical industry average of about 34.9x, yet sits below the peer group average of roughly 44.4x. That mix suggests the market is already assigning an earnings premium relative to book and sales based peers, but not the highest one available in this corner of the market.
The fair multiple implied by a more tailored model that incorporates Emerson Electric's margins, growth profile, size and risks comes in below where the shares trade today. On this framework, the stock appears overvalued. Because the planned automation solutions service center in Qatar may be lifting optimism around future earnings power, the current P/E indicates that investors are willing to pay a higher price now in anticipation that those profits justify it. For anyone weighing fresh capital, the key question is whether the current earnings base and its prospects are strong enough to support a multiple above that modelled fair band. Explore the numbers behind Emerson Electric's P/E valuation.
The Emerson Electric Narrative: What Would Justify Today's Price?
Narratives pick up where Emerson Electric's valuation puzzle leaves off and spell out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today. Each scenario on Simply Wall St's Community page focuses on the assumptions sitting under its view of fair value so you can compare those inputs with Emerson Electric's actual results as they are reported.
Community views on Emerson Electric are split between a patient growth story and concern that recent enthusiasm already prices in a lot of that optimism.
Bull case: 8% undervalued
"The company's transformation toward a pure-play automation leader, emphasizing innovation, commercialization of new products, and operational excellence, continues to yield improved profitability…"
Discover why this Narrative puts Emerson Electric at 8% undervalued.
Bear case: 20% overvalued
"Intensified global competition from low-cost suppliers and widespread adoption of non-proprietary automation platforms increase the threat of price erosion and customer attrition…"
Explore why this Narrative puts Emerson Electric at 20% overvalued.
One more angle on Emerson Electric that could change your view
Everything so far has focused on what Emerson Electric looks like today. Yet a different picture emerges when you line up where professional forecasters expect the business to be in a few years. Explore where analysts expect Emerson Electric to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com