
Costco (COST) Stock Climbs On Profit Resilience As Valuation Debate Deepens
The market cheered Costco Wholesale, sending the stock up about 3% to roughly $923, even though expectations were already sky high. That reaction sits against a warehouse giant that just printed roughly $95.7b in quarterly revenue and about $6.75 in earnings per share, all while running a slim 3% net margin business that lives or dies on volume and loyalty.
What really drives this print is profit resilience. Trailing earnings over the past year reached about $9.2b, and the company squeezed slightly more profitability out of each dollar of sales. For a retailer on a premium P/E multiple, that margin story is what matters most.
Is Costco Wholesale priced for perfection, or does it simply reflect its premium status among retailers trading at lower P/E multiples and cash flow values? Compare the current share price against our valuation analysis for Costco Wholesale
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs Q4 2025): US$95.7b vs. US$86.2b (up about 11%)
- Net Income (Excl. Extra Items, Q4 2026 vs Q4 2025): US$3.0b vs. US$2.6b (up about 15%)
- Basic EPS (Q4 2026 vs Q4 2025): US$6.75 vs. US$5.88 (up about 15%)
- Trailing Net Margin (TTM to Q4 2026 vs prior TTM): 3.0% vs. 2.9% (slight margin expansion)
Tired of scrolling through dense paragraphs and raw figures trying to piece together Costco Wholesale’s story on your own? See the full financial picture, including a visual read on its valuation in the company report for Costco Wholesale.
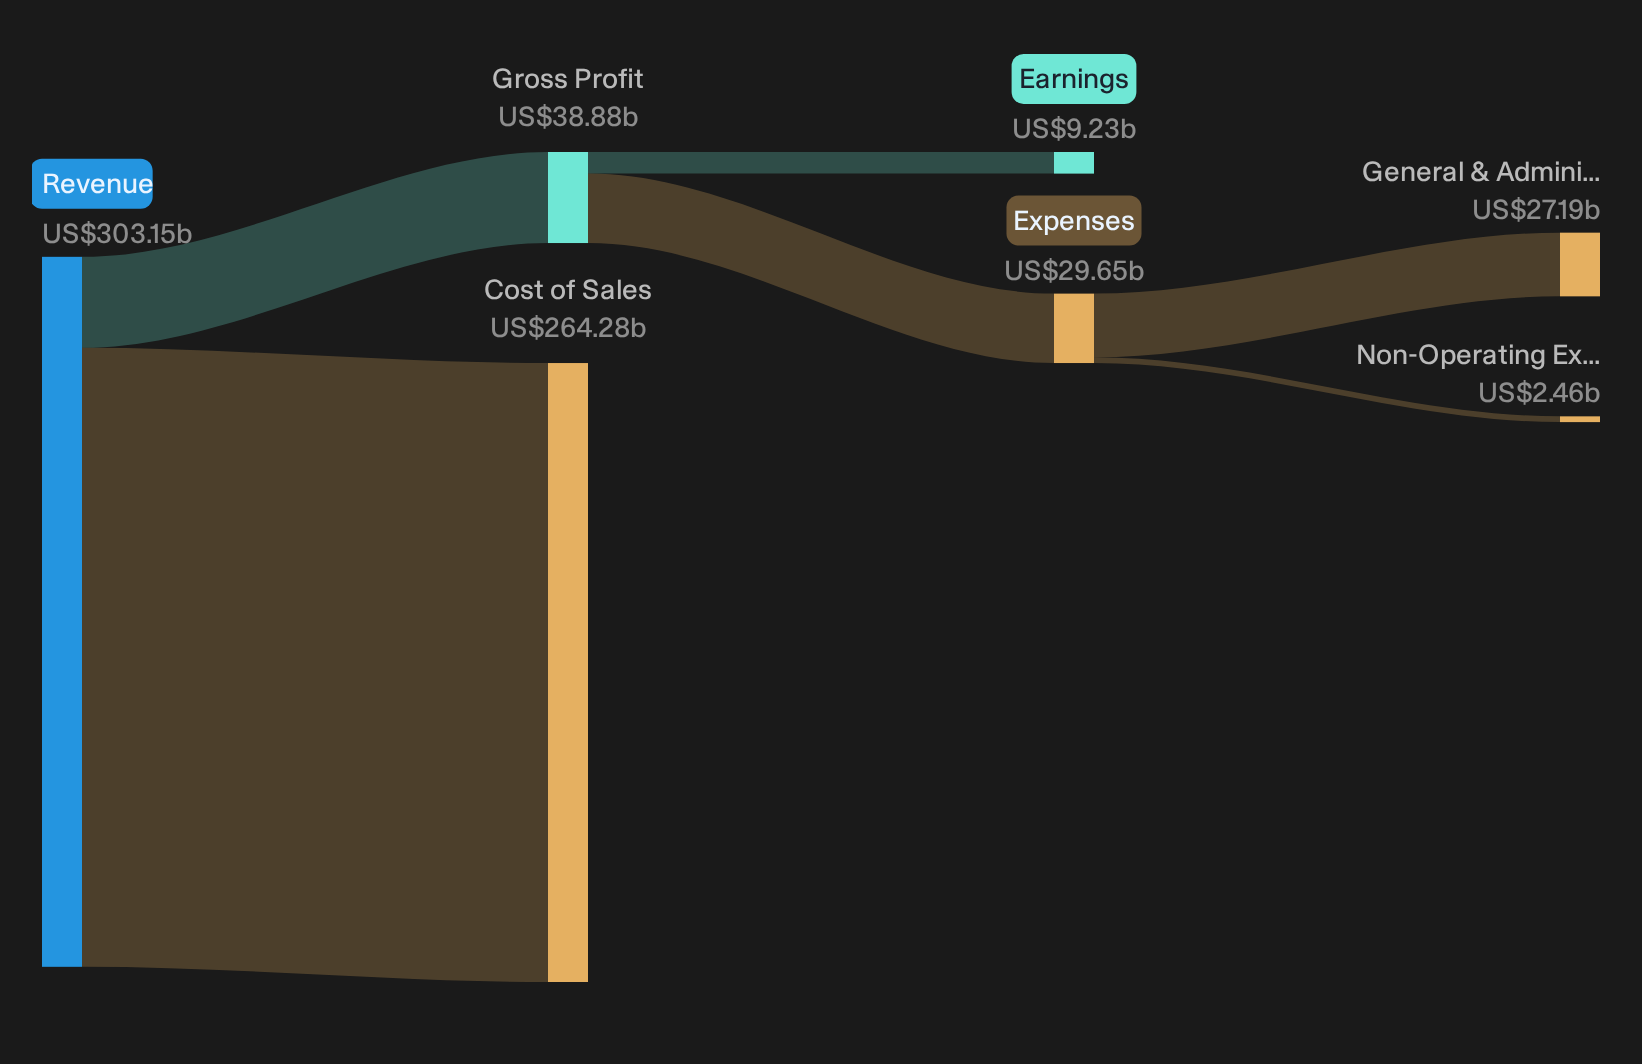
Evaluating Costco’s Bull Case Against Hard Milestones
At its core, the bullish story on Costco is that a sticky membership engine, growing digital usage, and store expansion can keep earnings durable even as the business gets larger. The latest quarter hits several of those checkpoints. Membership fee income reached US$1.85b with paid members at 84.1 million and U.S. and Canada renewal at 92.3%. That kind of stickiness is exactly what the thesis needs, even if membership growth is slowing.
Digital is another key plank. Digitally enabled sales moved above US$33b with growth above 20%, while same day delivery partnerships with Uber Eats, DoorDash and Instacart are now nationwide. For a warehouse retailer, that is real progress toward an omnichannel model where more spending can flow through the same cost base, aligning well with the idea of operating leverage tied to higher online penetration.
Compare Costco Wholesale’s membership and digital momentum with the street’s conviction. See the consensus price target analysis for Costco WholesaleBear Case Stress Test: Costco Growth Still Maturing
Bears argue Costco is sliding into maturity, with slower member additions, cooling traffic in older markets, and rising costs quietly eating into a thin model. The latest figures partly back that worry. Paid members reached 84.1 million and membership fee income hit US$1.85b, yet membership growth has decelerated for eight straight quarters, even as renewal rates ticked up. That is loyalty without much new blood.
Sales and comps stayed healthy, but digitally enabled revenue above US$33b and traffic up 3.3% now rely more on existing shoppers spending more, not a surge of fresh households. On costs, reported gross margin rate edged down to 11.02% while labor and a US$152m LIFO inventory charge pulled in the opposite direction of tight pricing. Tariff refunds and SG&A leverage offset some pressure this time, which means a key bear milestone, structural cost squeeze, is delayed rather than resolved.
With Costco Wholesale trading on a rich P/E and the price sitting above the internal DCF estimate, you need to verify whether liquidity, leverage and cash generation actually justify that premium. Analyze the full financial health analysis of Costco Wholesale stock.Take Control Of Your Next Move
If Costco Wholesale’s mix of thin margins, membership strength and rich P/E has your attention, register for free with Simply Wall St and add it to a Watchlist to keep an eye on price versus fair value and wait for your preferred entry point. After you own shares, manage your exposure with our Portfolio Command Center so you only see the most important updates instead of day to day noise. For long term planning, tap into crowd insights through the Community and see how other investors are thinking about the same risks and opportunities. By spotting hidden catalysts and potential red flags early, you give yourself a better chance of staying ahead of the wider market.
Seeking Fresh Alternatives Beyond Costco?
New ideas move first. By the time every headline flags the breakout, the best entries can be gone. Scan fresh stock ideas while the data still matters and get in early.
- Track income streams that aim to stay resilient while prices swing by reviewing 8 dividend fortresses, built to highlight businesses where cash payouts remain a central focus.
- Spot early movers in AI infrastructure before momentum flies away by zeroing in on 87 AI infrastructure stocks, curated for companies powering the backbone of data and compute.
- Hunt for under the radar stability in a curated list of solid balance sheet and fundamentals stocks (24 results) that focuses on resilient finances and cash generation while others chase dropping headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com