
How Investors May Respond To Wabtec (WAB) $700 Million Simandou Services Deal
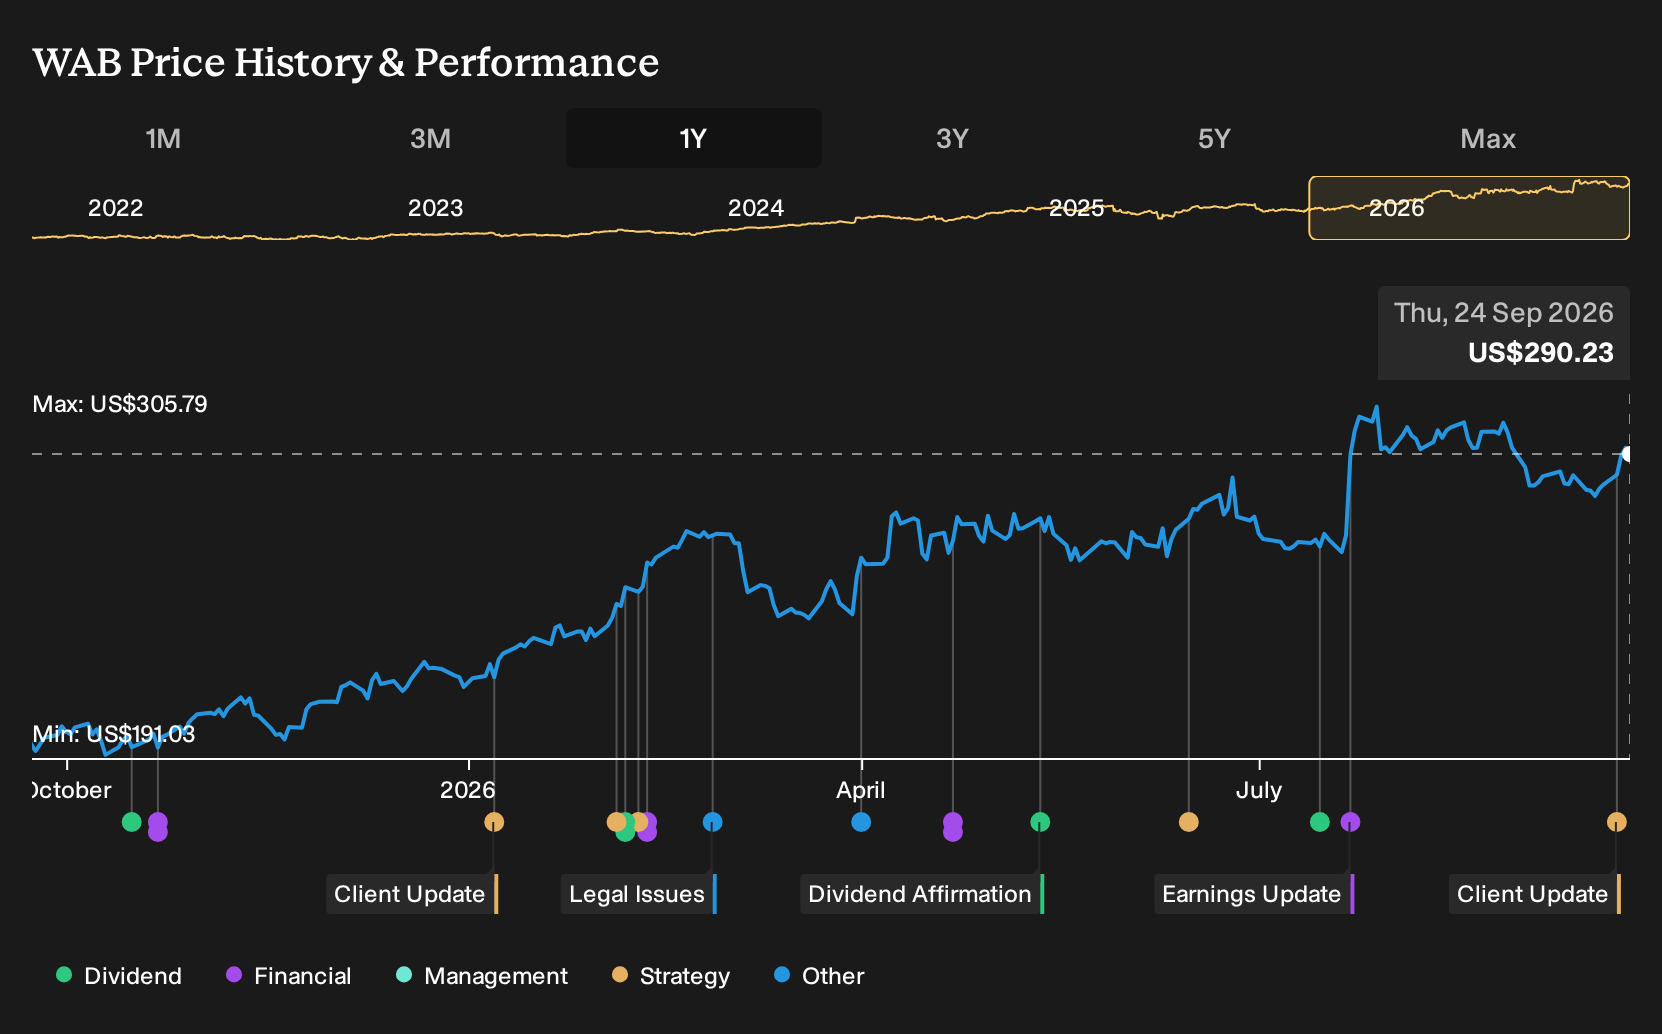
- Wabtec Corporation reported a long term services agreement of more than US$700 million with La Compagnie du TransGuinéen in September 2026, supporting ES43AC Evolution Series locomotives for Guinea's Simandou rail project and lifting total related commitments above US$1.2b.
- The contract extends Westinghouse Air Brake Technologies deeper into recurring maintenance, parts, and digital support services. It adds multi year visibility on high value aftermarket work in a region where the business has been scaling its rail presence.
- Now the focus shifts to how Westinghouse Air Brake Technologies' investment narrative could be reshaped by this large Simandou services contract.
Scan how Westinghouse Air Brake Technologies compares to other rail and infrastructure plays by running the hand picked 39 power grid technology and infrastructure stocks alongside this new Simandou services deal.
Westinghouse Air Brake Technologies Investment Narrative Recap
To own Westinghouse Air Brake Technologies, you need to believe that rail operators keep prioritizing modernization, long term maintenance, and higher margin digital systems, and that WAB converts its roughly US$30b plus backlog into steadier earnings. The new Simandou services contract reinforces that core services thesis, but it does not meaningfully change near term expectations on its own.
The key short term swing factor still looks like execution on services and modernization, after management flagged weaker 2026 services revenue tied to lower North American upgrades. Tariffs and input costs remain the other big operational risk, since management already describes them as a major margin headwind.
The most relevant recent disclosure for this Simandou news is the focus on Digital Intelligence, where sales reportedly grew around 76% in Q1 2026 and around 89% in Q2 2026. The Simandou agreement explicitly includes advanced remote diagnostics and data driven fleet support, which ties directly into that higher margin software and analytics push.
For you as a shareholder, the interesting question is execution. Wabtec now has a very large multi year African services contract layered on top of a broad freight and transit backlog, while also managing tariffs, integration of roughly US$4.5b of prior acquisitions, and a higher P/E multiple alongside significant insider selling.
Westinghouse Air Brake Technologies’ current analyst script points to revenues of US$14.8b and earnings of US$2.4b by 2029, based on 7.3% yearly revenue growth and an earnings increase of about US$1.1b from US$1.3b today.
Uncover why Westinghouse Air Brake Technologies' fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster tightly between about US$283 and US$330 per share, even before factoring in the Simandou win. That narrow band sits beside risks around weaker 2026 services revenue and tariff pressure, so you can see how opinions on Westinghouse Air Brake Technologies can split. Explore the full range of community forecasts before deciding how this story fits your portfolio.
Explore another Westinghouse Air Brake Technologies fair value estimate, including one that suggests it could be worth just $283.19.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Westinghouse Air Brake Technologies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Westinghouse Air Brake Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westinghouse Air Brake Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Westinghouse Air Brake Technologies?
Once you have formed a view on Westinghouse Air Brake Technologies, it can help to line it up against other potential opportunities so you see where the risk and reward profile really stands out. The Simply Wall St Screener lets you do exactly that by filtering for specific traits that match how you like to invest.
- If you want yield to do more of the work, scan for income opportunities through 8 dividend fortresses that might complement a rail focused holding like Westinghouse Air Brake Technologies.
- If you prefer to keep downside in check, especially when stories are already well owned, then run a search across 29 resilient stocks with low risk scores to see which businesses score better on resilience.
- If you are looking for under followed opportunities rather than widely tracked tickers, widen your watchlist with 16 high quality undiscovered gems and compare their fundamentals with what you see at Westinghouse Air Brake Technologies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com