
Kidney Drug Study Progress Might Change The Case For Investing In Vertex Pharmaceuticals (VRTX)
- Vertex Pharmaceuticals reported past positive Phase 2b AMPLIFIED results for inaxaplin in APOL1-mediated kidney disease, with a 45 mg once-daily regimen added to standard of care showing a generally safe and well tolerated profile and completion of enrollment in the Phase 2/3 AMPLITUDE trial.
- The inaxaplin data and AMPLITUDE enrollment progress point to a concrete effort by Vertex Pharmaceuticals to build a kidney disease franchise alongside its existing cystic fibrosis products as well as its newer pain and endocrinology products.
- Now the focus turns to how Vertex Pharmaceuticals' investment narrative around pipeline diversification could be reshaped by inaxaplin's Phase 2b kidney data.
Vertex Pharmaceuticals Investment Narrative Recap
To own Vertex Pharmaceuticals, you need to be comfortable with a story that still leans heavily on cystic fibrosis cash flows, while management spends aggressively to broaden into pain, gene editing, kidney and endocrine diseases. The inaxaplin Phase 2b AMPLIFIED readout fits that wider push but does not change the near term reality that commercial execution in CF, CASGEVY and JOURNAVX does most of the financial lifting.
The biggest swing factor in the short run is how quickly newer launches gain real-world uptake and reimbursement, given earnings forecasts assume double digit annual growth. The key risk is that ongoing R&D spending in kidney, pain and gene editing outpaces future product contribution or faces regulatory setbacks, which could pressure margins even with today’s strong profitability profile.
The inaxaplin AMPLIFIED data is the clearest recent proof point for Vertex Pharmaceuticals trying to build a kidney disease pillar alongside its existing franchises. A generally well tolerated 45 mg once daily regimen, on top of standard of care, gives the business a cleaner operational path into AMKD populations with modest proteinuria and with type 2 diabetes that are outside the AMPLITUDE design.
For catalysts, investors are likely to watch how AMPLITUDE progresses after full enrollment and how both trials feed into the broader narrative of reducing reliance on CF over time. The risk side of that same coin is straightforward. Any disappointing proteinuria or eGFR outcomes, or regulatory friction around trial design and endpoints, would weaken one of the more tangible diversification efforts currently in Vertex’s pipeline.
Vertex Pharmaceuticals' current analyst narrative points to revenue of US$17.2b and earnings of US$6.5b by 2029, which rests on 10.9% yearly revenue growth and an earnings increase of about US$2.1b from US$4.4b today.
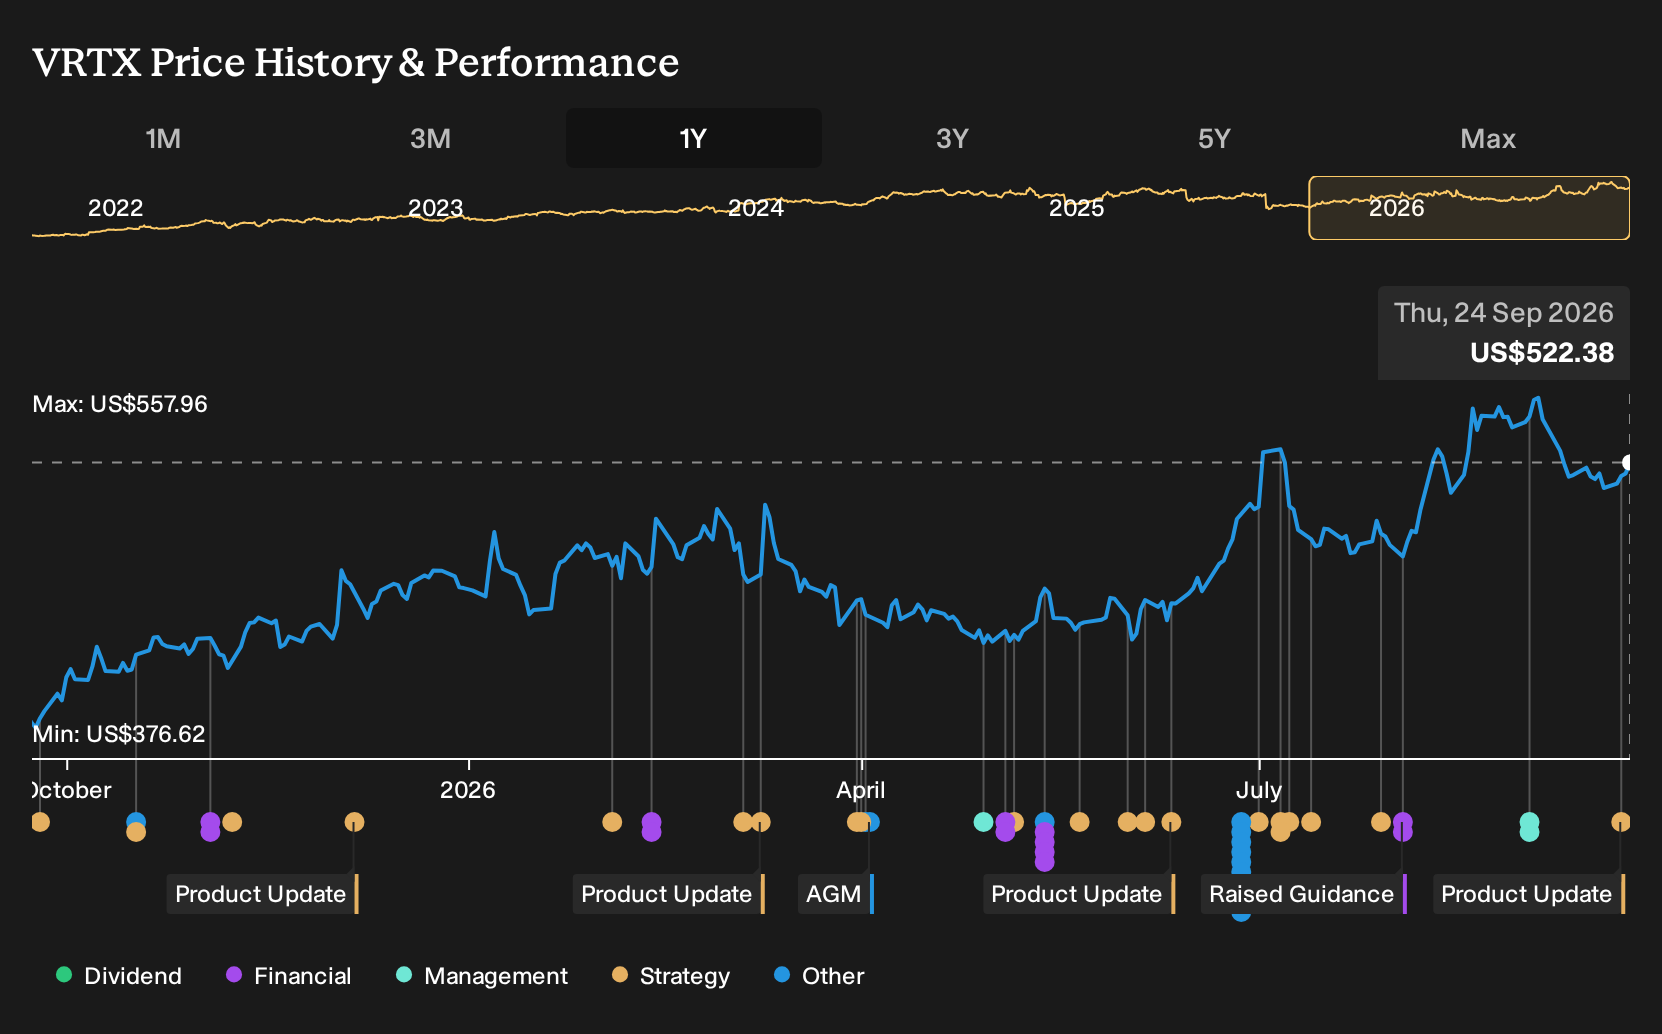
Uncover why Vertex Pharmaceuticals' fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One catalyst the most optimistic analysts keep coming back to is how Vertex Pharmaceuticals could use kidney and gene editing wins to push earnings far beyond today’s consensus. Before this inaxaplin news, the bullish camp was already penciling in US$19.1b of revenue and US$9.0b of earnings by 2029. That contrasts with the baseline US$17.2b and US$6.5b view. Both sets of forecasts were built before AMPLIFIED, so you should expect opinions and possibly those numbers to shift as you weigh different scenarios for your own portfolio.
Explore 5 other Vertex Pharmaceuticals fair value estimates, including one that suggests as much as 29% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vertex Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vertex Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vertex Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vertex Pharmaceuticals?
If the Vertex Pharmaceuticals story has you thinking about how new products can reshape future cash flows, it can be useful to line it up against other companies with different strengths. The Simply Wall St Screener lets you filter for the traits you care about most, then compare those profiles with Vertex on your own terms.
- For investors who care most about balance sheet resilience and clean fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that meet those criteria.
- If you are hunting for quality businesses that the market may be overlooking, consider a curated pool of 16 high quality undiscovered gems and see how they stack up next to your current watchlist.
- For a focus on stability and income, check out companies screened as 8 dividend fortresses and compare their profiles with growth stories like Vertex Pharmaceuticals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com