
British Penny Stocks To Watch In September 2026
Global bond markets are under pressure as long dated US Treasury yields sit around levels not seen since 2004, lifting borrowing costs worldwide and forcing investors to think harder about risk. That backdrop is putting quiet, solid UK small caps on many radars. This article looks at a group of stronger balance sheet British penny stocks and highlights three that screen as financially robust and still under the radar.
The stocks covered below are just a small sample of this theme. The full screen surfaces 8 more British penny shares with similar balance sheet strength, valuation appeal and growth forecasts that are not covered here. To identify and analyze the highest conviction opportunities from this broader pool, head straight into the Elite Penny Stocks screener.
Franchise Brands (AIM:FRAN)
Franchise Brands runs a collection of franchise and service businesses, with asset light, recurring revenue from its Filta International cooking oil and fryer management arm sitting alongside Pirtek hydraulic services, water and waste operations and several B2C brands. Recent revenue is led by Pirtek at about £64 million, W&WS at £45 million and Filta at £37 million, with a smaller B2C and Azura contribution, all under a roughly £297 million market cap.
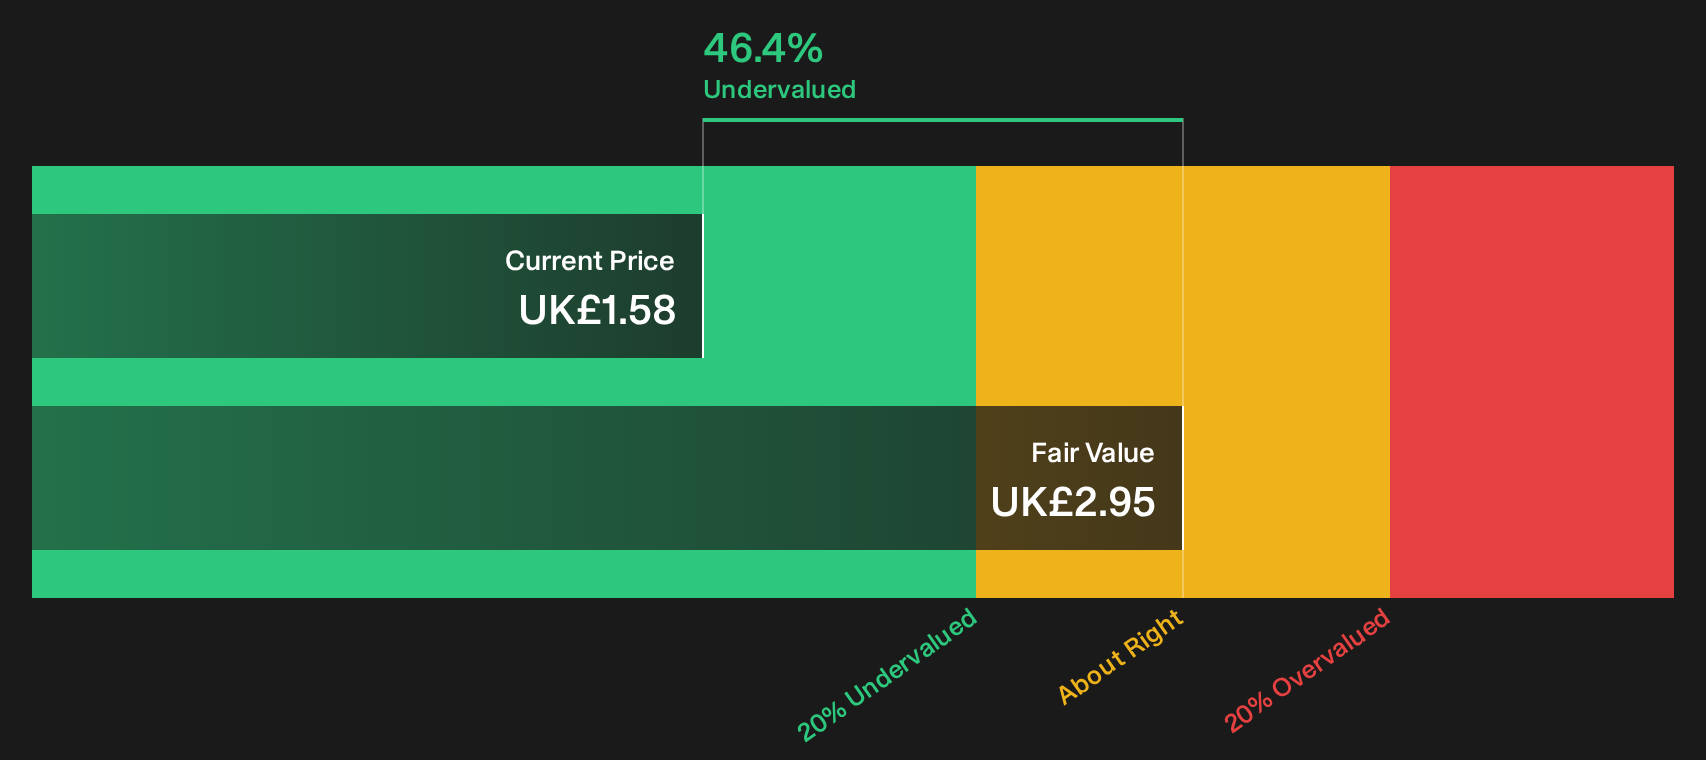
Franchise Brands plugs into the Elite Penny Stocks theme through Filta’s recurring franchise model. Group earnings grew 39.1% last year and the shares trade about 46.4% below one estimate of fair value. The business still relies fully on external borrowing, so the appeal of this asset light growth story hinges on how that funding structure interacts with margins over time.
That funding question is exactly what makes the DCF valuation analysis for Franchise Brands useful for judging how Franchise Brands’ debt load interacts with its asset light model.
Afentra (AIM:AET)
Afentra is an Africa focused upstream oil and gas producer, with the Elite Penny Stocks theme connection coming from its operated and non operated interests in Angola and Somaliland. The group generates about US$153 million from oil and gas exploration and production and has a market cap of roughly £212 million.
Afentra gives you pure upstream oil and gas exposure through producing and appraisal assets in Angola, plus exploration in Somaliland, all wrapped inside a penny stock that has outperformed both the wider UK market and UK oil and gas sector over the past year. The appeal now hinges on how the move from forecast growth to consistent profitability interacts with one unresolved pressure on its balance sheet.
That balance sheet question is exactly why the 3 key rewards and 1 important warning sign could matter for Afentra, as it provides the full picture of what might accelerate or stall the story.
Diaceutics (AIM:DXRX)
Diaceutics runs DXRX, a precision medicine diagnostic commercialization platform that uses lab testing data and tools like DXRX Signal and Physician Mapping to help pharma and biotech roll out targeted therapies. Almost all of its £41 million Medical Labs & Research turnover comes from this data led work, underpinned by a roughly £164 million market cap.
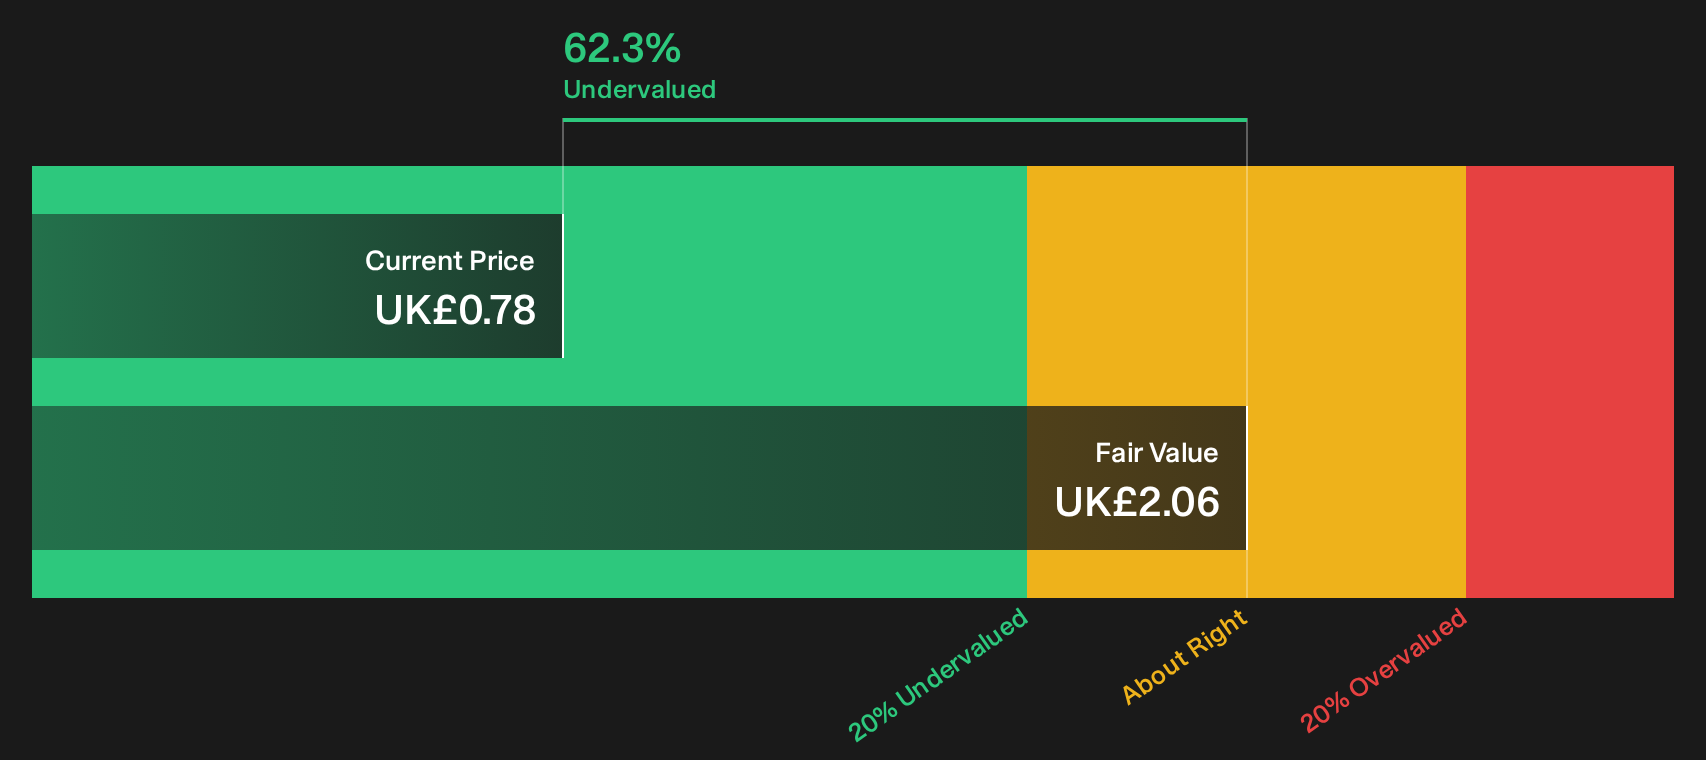
DXRX combines a data heavy diagnostics platform with revenue growth forecasts of 19.3% a year and earnings expected to rise very quickly. The shares trade about 25.1% below one fair value estimate and at a P/S discount to peers. Interest hinges on what happens when that rapid growth path meets a loss making, debt funded balance sheet that still needs to absorb the shift to profitability.
That pivot to profitability makes the analyst forecasts for Diaceutics a sharp way to see whether Diaceutics’ expected trajectory is accelerating fast enough to justify the risk.

Curious About Alternative Opportunities?
Fresh ideas move first. By the time momentum is flying, the easy entry points are gone. Scan these under the radar lists before the crowd catches on and act now.
- Spot income workhorses early and tap into the 1 dividend fortresses while payout strength and balance sheet resilience are still being priced as an afterthought.
- Track tomorrow's infrastructure backbone and review the 39 power grid technology and infrastructure stocks before grid upgrade demand turns these quiet operators into fully priced momentum stories.
- Position ahead of the next computing wave and review the 25 quantum computing stocks while quantum hardware and software leaders remain under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com