
AI Data Center Growth Might Change The Case For Investing In Celestica Stock
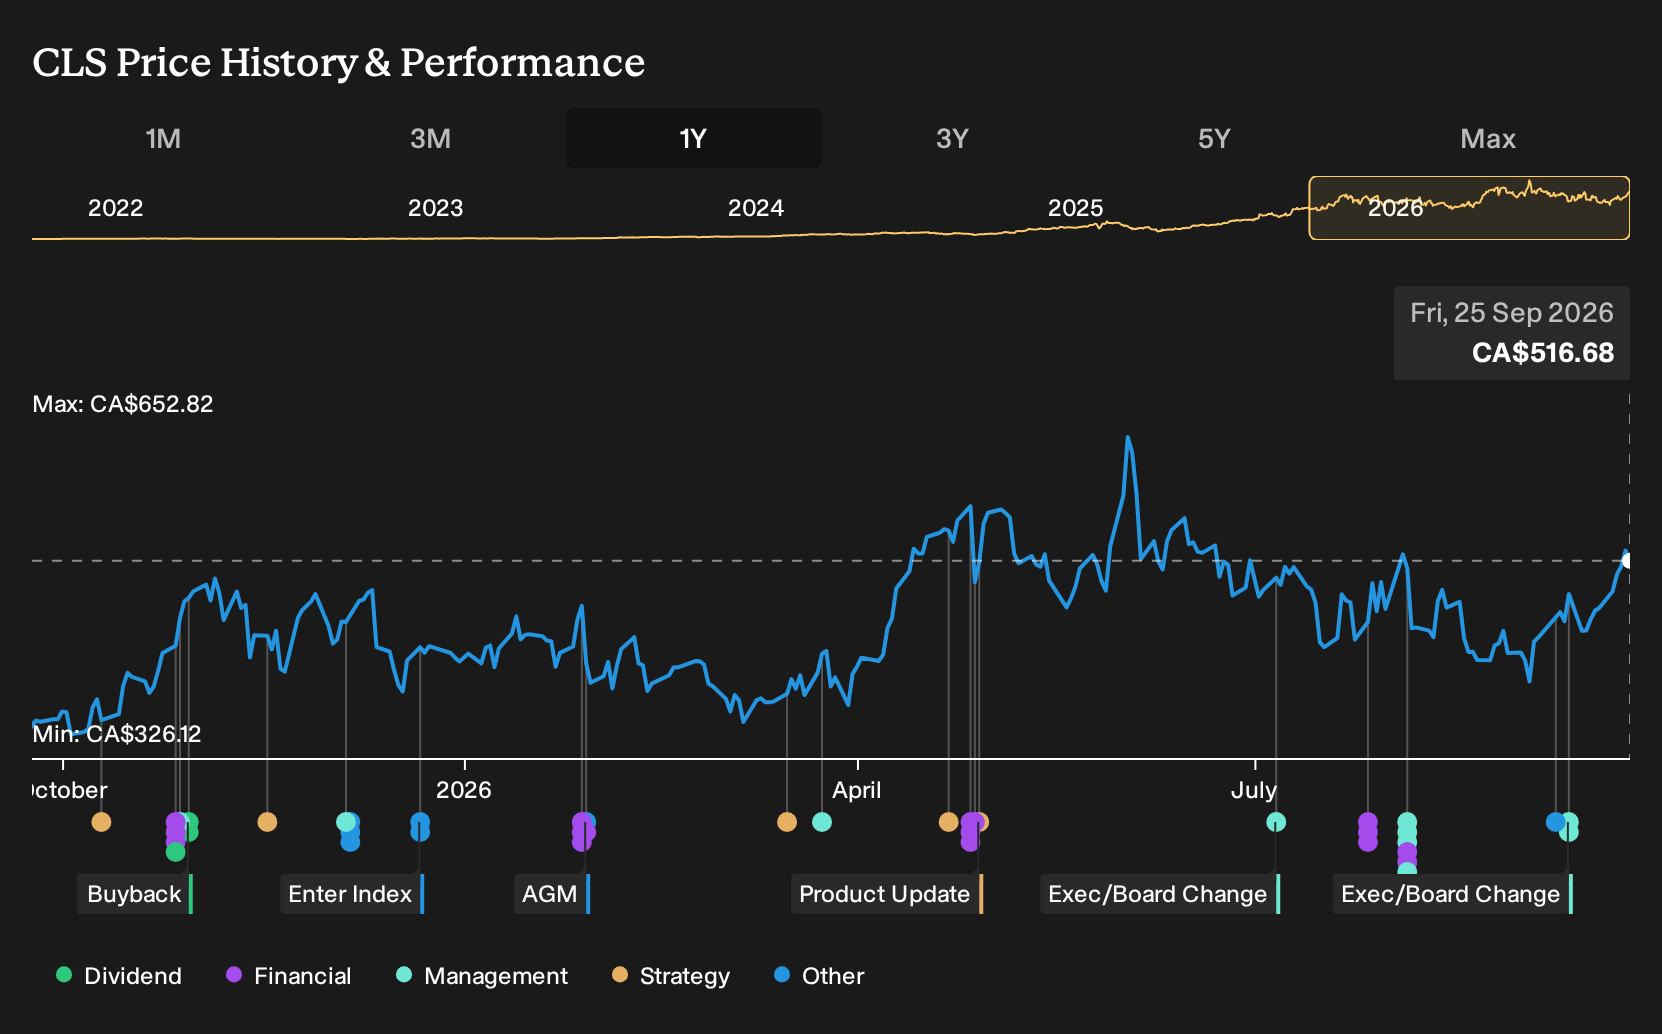
- Celestica reshaped its leadership earlier in September 2026, creating a Group President, Global Markets role for long-time CFO Mandeep Chawla and promoting Senior Vice President of Finance Todd Ankenmann to Chief Financial Officer with higher salaries, CTI targets, and fresh RSU and PSU equity awards.
- The expanded commercial focus for Chawla and the elevation of Ankenmann indicate management attention on scaling AI data center demand while tightening financial execution and capital allocation.
- The next area of attention will be how Celestica's refreshed leadership structure around AI data center demand could influence its broader investment narrative.
Scan how Celestica’s leadership reshuffle around AI data centers compares with other hand-picked enablers of this buildout across 87 AI infrastructure stocks.
Celestica Investment Narrative Recap
To own Celestica, you need to believe the AI and cloud buildout can support sustained demand for its Connectivity and Cloud Solutions work, while the Advanced Technology Solutions segment gradually adds more stable, higher margin exposure. The near term swing factor is execution on large AI data center programs and complex technology ramps, where timing and delivery discipline matter.
The biggest risk is still concentrated exposure to a few hyperscaler customers and a heavy tilt toward CCS. The leadership reshuffle looks operationally focused rather than thesis changing. It does not materially alter the core near term catalyst or the primary concentration and execution risks already in play.
The most relevant recent item alongside this leadership move is the focus on accelerated AI infrastructure demand and multiple 800G and upcoming 1.6T program ramps inside Celestica’s CCS segment. These ramps remain the practical engine behind expectations for strong revenue and earnings performance over the next few years.
Chawla’s new Group President, Global Markets role and Ankenmann stepping in as CFO put more organizational weight on commercial execution and capital allocation around that AI data center pipeline. For you, the key question is whether this structure helps the business manage customer concentration, technology transition risk, and the heavy investment needed to support those large, complex programs.
Celestica's narrative projects $41.7b revenue and $2.7b earnings by 2029. This assumes 38.8% yearly revenue growth and an earnings increase of about $1.6b from $1.1b today.
Uncover why Celestica's fair value indicates a 31% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, Celestica’s range runs from about 676 to 771, which is wide for a single group of private investors. These views sit alongside leadership changes aimed at capturing AI infrastructure demand, so readers can see both optimism and clear execution risk. Explore the full spread of opinions.
Explore 2 other Celestica fair value estimates, including one that suggests it could be worth just CA$676.25!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Celestica research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Celestica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Celestica's overall financial health at a glance.
Looking For More Investment Ideas Beyond Celestica?
If Celestica has sharpened your interest in AI infrastructure and resilient balance sheets, it can help to line it up against other potential opportunities using the Simply Wall St Screener.
- For investors who care most about financial resilience and lower downside risk, consider starting with a 8 resilient stocks with low risk scores that have historically scored well on balance sheet strength and volatility.
- If you want solid fundamentals backed by strong finances, you can scan a list of solid balance sheet and fundamentals (7 results) and see which ones fit the profile you have in mind.
- To widen the search to lesser-known opportunities that still clear high quality bars, check out a 9 high quality undiscovered gems that might deserve a spot on your radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com