
Albany International (AIN) Beat Earnings And Extended Boeing Work, Is It Still Cheap?
Albany International (AIN) just put two clear signals in front of investors. Quarterly earnings per share came in ahead of expectations, and a renewed Boeing composites contract adds firmer visibility to future aerospace work.
That stronger quarter has arrived after a choppy stretch for Albany International, with the share price up 3.43% over the past month but down roughly 20% over the last 90 days. At the same time, the year-to-date share price return of 16.51% and 1-year total shareholder return of 16.17% point to momentum rebuilding from a weaker multi year total return record.
Spot 16 high quality undiscovered gems that share Albany International’s mix of specialized industrial exposure and aerospace ties before they move back onto everyone’s radar.After a sharp 90 day slide and a recent bounce around $60.98, Albany International now sits at a pivot point. Is this recent strength enough to justify paying up today, or is patience the better price risk trade off?
Most Popular Narrative: 7% Undervalued
The most followed narrative on Albany International compares a fair value of $65.67 to the recent $60.98 close, framing the stock as modestly undervalued and heavily tied to long term aerospace and specialty materials demand.
Accelerating adoption of lightweight composites in aerospace and defense, as demonstrated by expanding content on next-generation aircraft, ramping on key programs like CH-53K, LEAP, and Bell 525, and new applications such as 3D woven parts replacing titanium, positions Albany's Engineered Composites segment for significant high-margin revenue and earnings expansion.
See why 2 investors see Albany International as 7% undervalued.
Result: Fair Value of $65.67 (UNDERVALUED)
Still, the narrative around Albany International can crack if structural declines in traditional paper markets deepen, or if key aerospace programs face delays or contract changes.
Find out about the key risks to this Albany International narrative.
Another View: What Multiples Say About Albany International
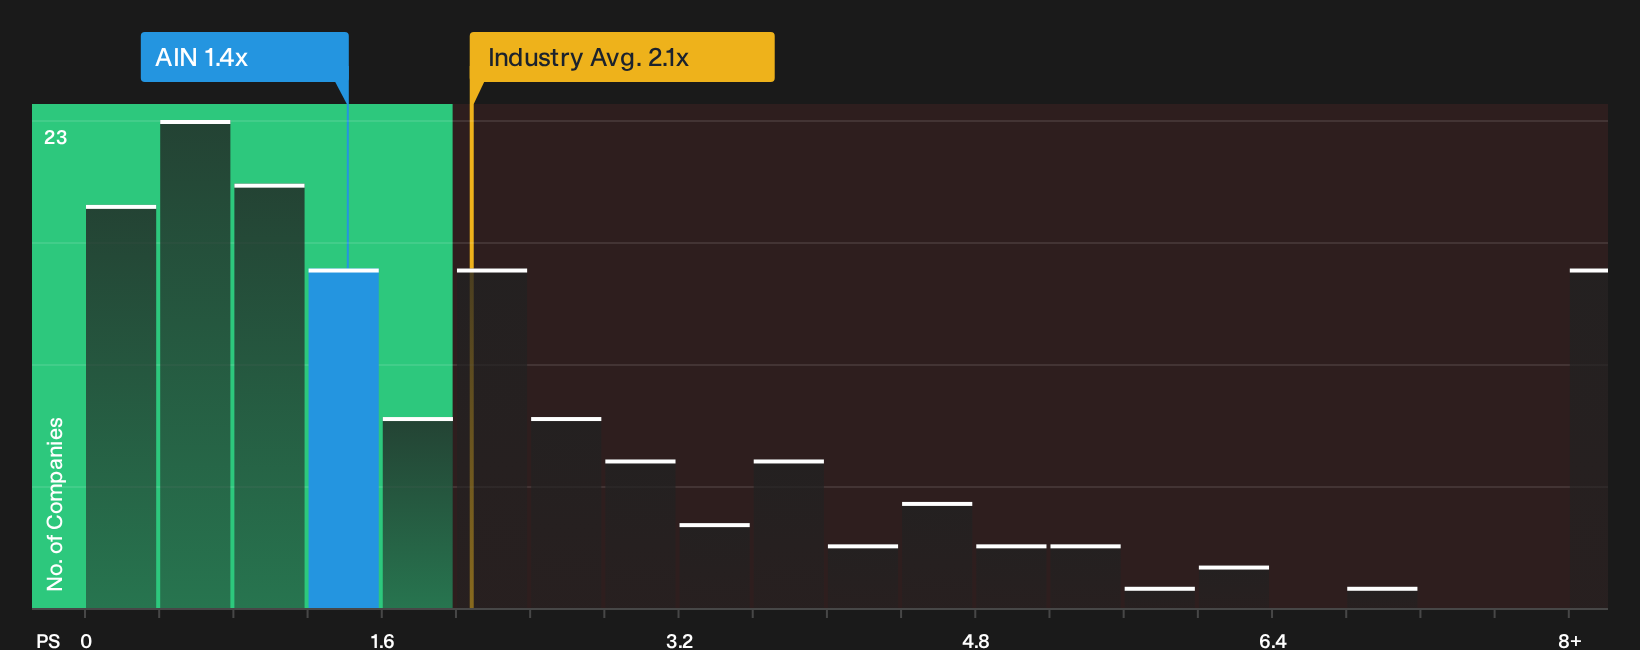
There is a different read on Albany International once price ratios are brought into the picture. The P/S multiple sits at 1.4x, which is higher than the fair ratio of 1x that the market could move toward over time. Yet it is lower than both the US Machinery industry at 2.1x and the peer average at 2.6x. That mix points to limited cushion if sentiment cools, but also to less excess optimism than some rivals. Which side of that trade off matters more to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Albany International so far. If you want to move early instead of simply following the crowd, consider both perspectives by reviewing the full picture of 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Albany International?
Do not stop with Albany International. Broaden your watchlist with focused idea lists that many investors overlook until the easy gains have already moved on.
- Target resilience by scanning 30 resilient stocks with low risk scores that attempt to balance return potential with a focus on durability when conditions get tougher.
- Zero in on quality by reviewing the list of solid balance sheet and fundamentals (24 results) so you can spot businesses that may handle pressure better than highly leveraged peers.
- Hunt for mispriced opportunities through the 30 high quality undervalued stocks before other investors start bidding up those same tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com