
AI Payment Trial At Danske Bank Stock Has Changed Its Investment Story
- Danske Bank and Mastercard recently completed Denmark’s first consumer payment handled entirely by an AI agent, which booked and paid for a coffee-tasting experience using Mastercard Agent Pay and a Danske Bank issued card.
- The test shows Danske Bank experimenting with AI driven transaction flows that could affect customer engagement, payment economics, and long term digital operating models.
- Attention now turns to how this AI powered payment milestone might influence Danske Bank’s investment narrative around digital execution and competitiveness.
Scan how Danske Bank's AI driven payment move compares with other financial institutions experimenting with machine-led transactions by reviewing 227 resilient stocks with low risk scores in the sector.
Danske Bank Investment Narrative Recap
To own Danske Bank, you need to believe the group can keep turning a broad Nordic footprint, steady volume trends and disciplined costs into resilient earnings, even as digital disruption and regulation keep pressure on fees and compliance spend. The AI driven payment trial with Mastercard sits within that digital push but, on its own, does not look like a major near term earnings catalyst.
The bigger swing factor in the short term still looks like how funding costs, credit quality and fee pressure evolve against gradually growing revenue and modest earnings growth expectations. The key risk remains margin pressure from competition, regulation and higher risk funding, which could offset benefits from digital projects such as AI enabled payments.
Among recent developments, the disclosure that BlackRock holds 5.27% of shares and voting rights in Danske Bank is the clearest operationally relevant data point. It confirms a large institutional investor on the register, which can matter for liquidity, governance focus and how management messages around capital use and digital execution are received.
This stake does not directly change earnings, returns or risk, although it arrives as analysts expect relatively modest profit growth and a P/E of 12.8x compared with an estimated fair P/E of 15.9x. For you, the practical question is whether Danske Bank’s mix of digital experiments, capital strength and regulatory overhang still lines up with your own view of risk and return.
Danske Bank’s current analyst story points to DKK 63.9b in revenue and DKK 26.1b in earnings by 2029, based on assumed yearly top line growth of 3.5% and an earnings increase of DKK 2.4b from DKK 23.7b today.
Uncover why Danske Bank's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
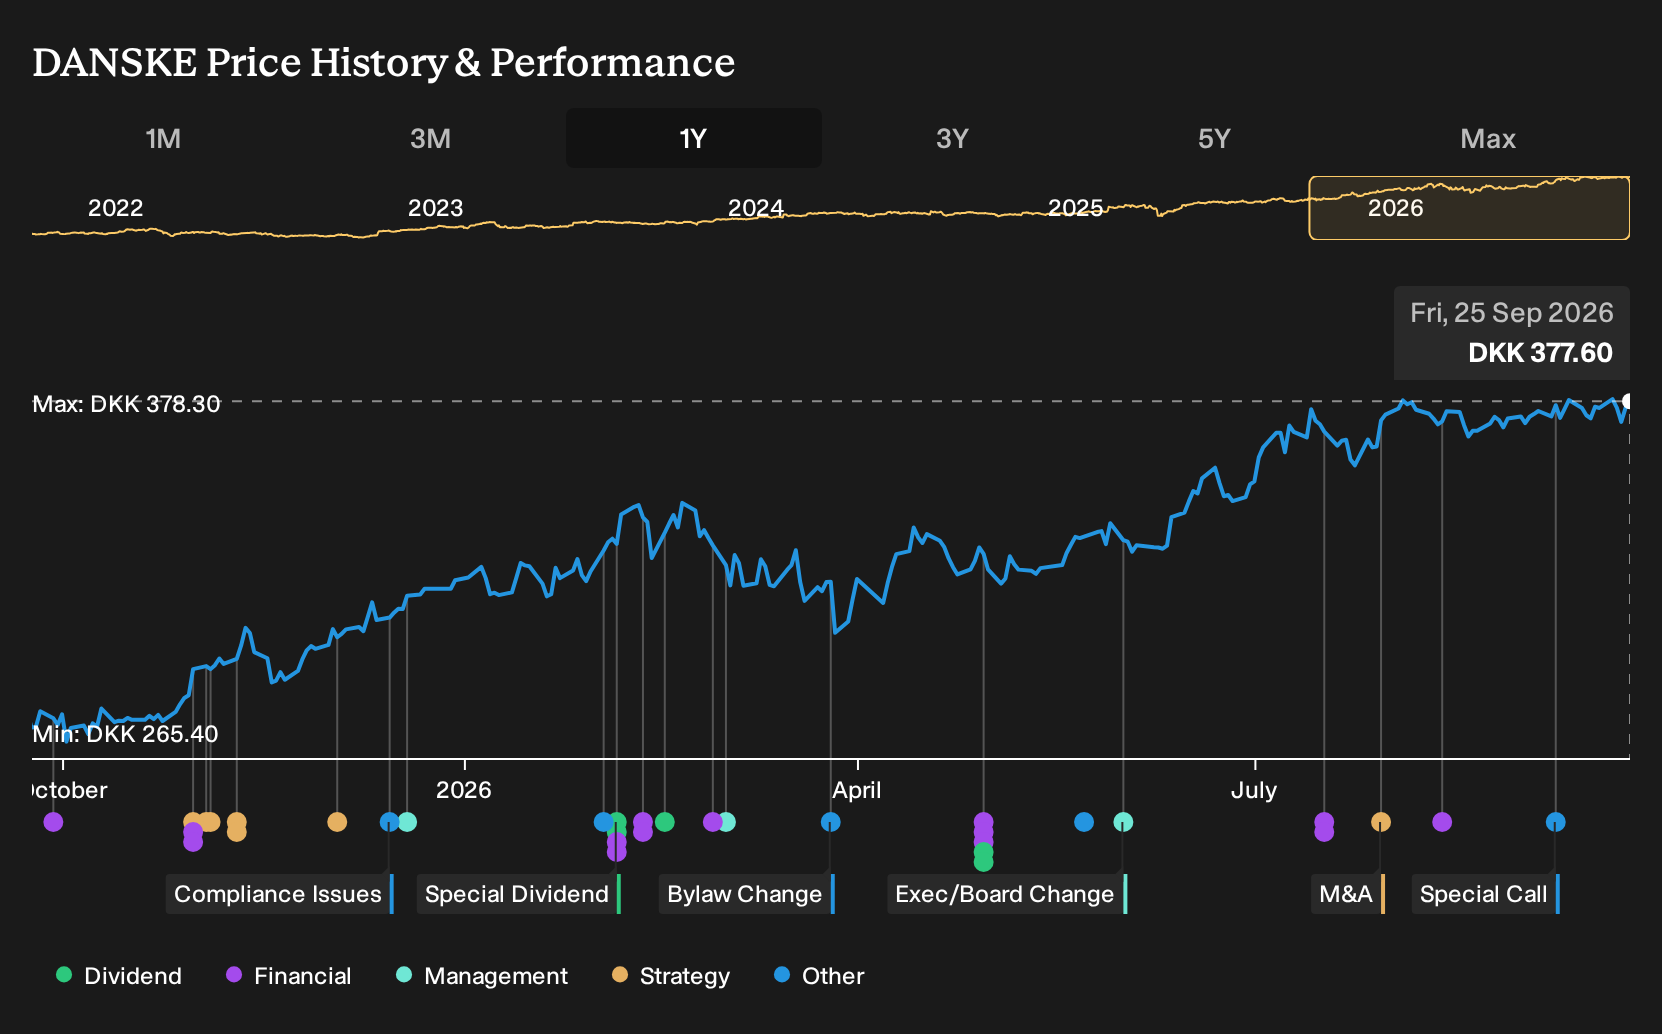
Exploring Other Perspectives
Think about one alternate angle here. The most optimistic analysts already had Danske Bank reaching DKK 67.7b in revenue and DKK 28.3b in earnings by 2029, helped by faster digitalisation. The AI powered payment test could either reinforce that upbeat view or cause some to rethink it; explore multiple forecasts before deciding where you sit.
Explore 3 other Danske Bank fair value estimates, including one that suggests there may be as much as 81% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Danske Bank research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Danske Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Danske Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond Danske Bank?
Once you have a view on Danske Bank, it can help to widen the lens and compare it with other opportunities that match your preferred style, risk level and income needs. The Simply Wall St Screener gives you a quick way to do that using consistent fundamentals across the market.
- If you want potential mispricing plus quality fundamentals, scan a focused group of 180 high quality undervalued stocks that might warrant a place on your watchlist.
- For investors who care most about getting paid while they wait, check out income ideas drawn from 162 dividend fortresses to see which payouts and balance sheets appeal to you.
- When capital preservation is your first filter, start with a list of solid balance sheet and fundamentals (202 results) and see how financial strength compares with what you see at Danske Bank.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com