
SPS Commerce (SPSC) Could Be 13% Overvalued Following Its MAX AI Rollout
SPS Commerce (SPSC) just pushed deeper into AI-powered supply chain software, rolling out its MAX agentic AI layer and a suite of new tools across fulfillment, onboarding, analytics and visibility.
The AI rollout lands while SPS Commerce’s 90-day share price return of 40.46% points to strong recent momentum, even though the year-to-date share price return declined 5.94% and the 1-year total shareholder return fell 21.21%. This suggests that investors are still weighing execution risk against long-term potential.
See how other AI-focused software players are positioning for their next phase by running the curated 37 profitable AI stocks that aren't just burning cash.
Bulls view SPS Commerce’s MAX rollout and recurring supply chain software as the beginning of a reset, while bears point to mixed returns and execution risk. Which story does the current valuation actually support?
Most Popular Narrative: 13% Overvalued
The most followed narrative values SPS Commerce at $73.18 per share, which sits below the recent $82.69 close and implies investors are paying a premium for the story already in the price.
The accelerating digitalization of retail supply chains and rising compliance requirements are driving robust demand for SPS Commerce's cloud-based EDI and supply chain solutions, supporting sustained growth in new customer adds and recurring revenue.
As the complexity of omni-channel retail and need for real-time, integrated supply chain analytics increases, SPS Commerce is well positioned to expand its average revenue per user (ARPU) through expanded network connections and the cross-selling of high-value products like analytics and revenue recovery solutions.
See why 4 investors see SPS Commerce as 13% overvalued.
Result: Fair Value of $73.18 (OVERVALUED)
Still, SPS Commerce faces real pressure if cautious U.S. supplier spending persists or if recent acquisitions fail to deliver the expected cross-sell benefits.
Find out about the key risks to this SPS Commerce narrative.
Another View: SWS DCF Model Points To Upside
The first storyline has SPS Commerce trading around $82.69 against an analyst fair value of $73.18, which frames the stock as 13% overvalued. A different lens tells a very different story.
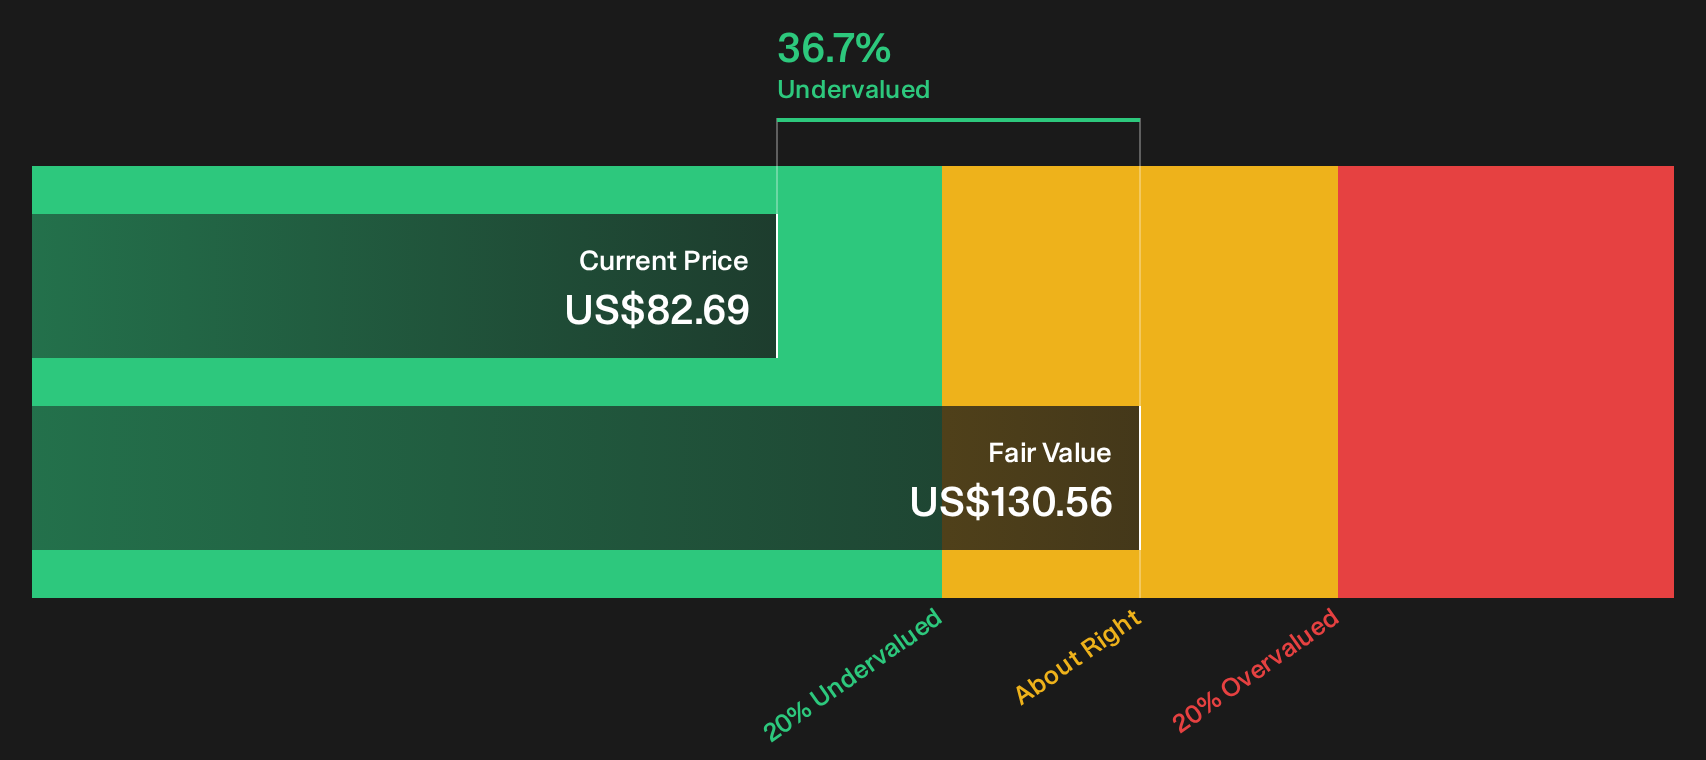
Simply Wall St’s DCF model estimates future cash flows at $130.56 per share, which is 36.7% above the recent price. That suggests the cash flow profile and long term earnings power could support a higher number than the analyst target implies. So which signal do you trust more: the market’s current P/E based mood, or the cash flow math over time?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
The split between SPS Commerce’s narratives only matters if you test the numbers yourself and decide where you land. To see what investors view as potential upside drivers right now, have a look at the 2 key rewards.
Looking for more SPS Commerce style ideas?
If SPS Commerce has you rethinking what belongs in your portfolio, do not stop with one ticker. Use focused screeners to surface fresh opportunities before they move.
- Target stability first by scanning a 30 resilient stocks with low risk scores that filters for resilient businesses with lower risk profiles.
- Hunt for value by running the 30 high quality undervalued stocks and spotting companies where quality fundamentals and pricing still look out of sync.
- Get early to potential future leaders by checking the 16 high quality undiscovered gems before they appear on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com