
Is Graham (GHM) Still Below Fair Value After Its Sharp 90 Day Pullback?
Graham (GHM) is back in focus after commentary around a roughly 30% perceived undervaluation, which is linked to record backlog levels and a firm book-to-bill ratio tied to long-running U.S. Navy defense programs.
Recent trading in Graham reflects that mixed backdrop. The share price is now US$87.53 after a 7 day share price return of 4.68%. However, it is still down 28.05% over 90 days, while the 1 year total shareholder return of 68.98% and very large 3 year total shareholder return suggest longer term momentum has been strong despite the pullback.
Scan beyond Graham and compare it with hand picked industrials and defense contractors that also screen as potential value opportunities on our 30 high quality undervalued stocks list.
After a sharp run over 12 months and a steep 90 day pullback, Graham now sits in a grey zone. Do the current fundamentals still justify buyers taking that risk for the perceived discount?
Most Popular Narrative: 30% Undervalued
Against Graham's last close at $87.53, the most followed valuation narrative points to a fair value near $125.75. This frames the recent pullback as a potential discount that still relies heavily on execution in defense and energy end markets.
Record backlog growth and strong book-to-bill ratio signal rising multi-year demand, underpinned by sustained U.S. Navy defense programs and increasing global infrastructure investment, supporting future revenue visibility and stability.
See why 21 investors see Graham as 30% undervalued.
Result: Fair Value of $125.75 (UNDERVALUED)
Still, the Graham narrative weakens quickly if U.S. defense orders slow or if early stage bets in small modular nuclear and cryogenics fail to scale.
Find out about the key risks to this Graham narrative.
Another View On Graham’s Valuation
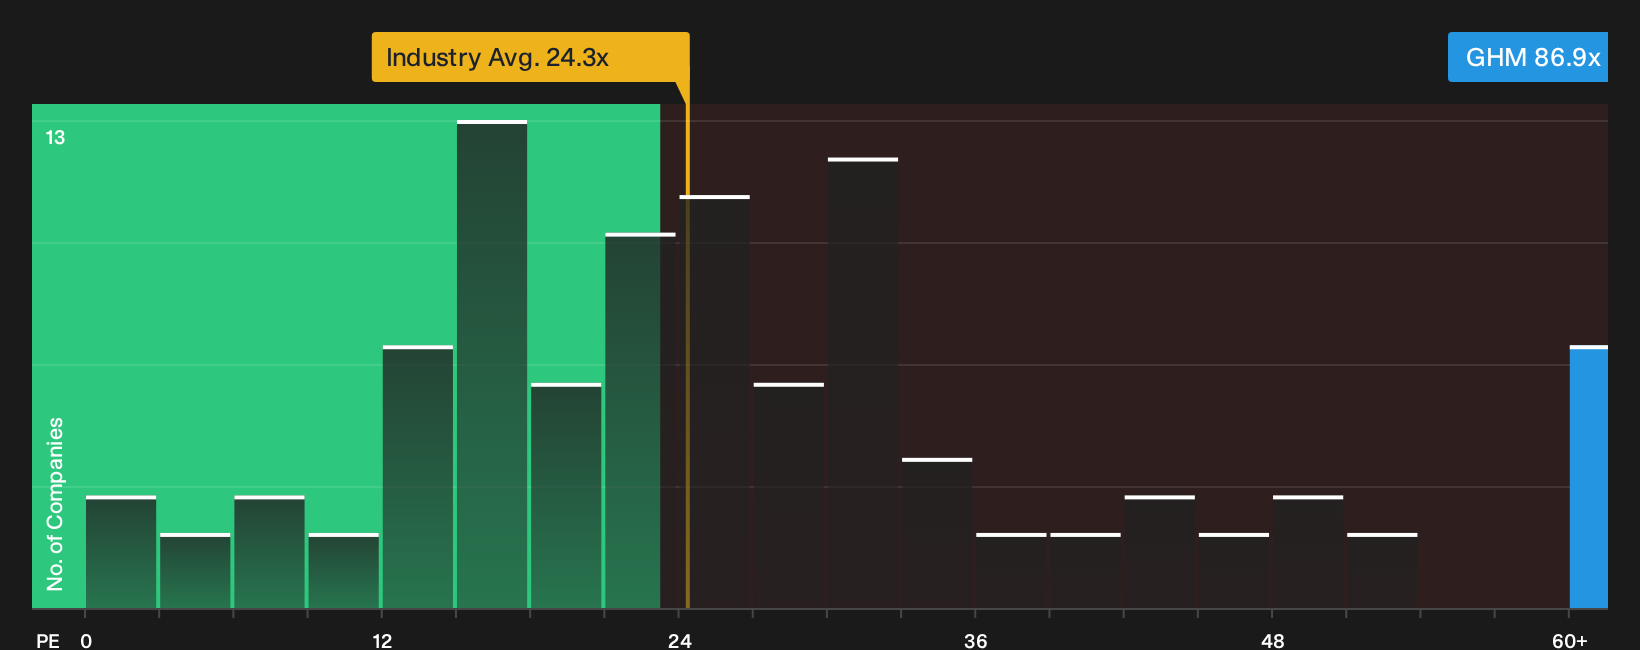
The 30% perceived discount on Graham looks very different when you switch lenses. On current numbers, the stock trades on a P/E of 86.9x, compared with 24.4x for the US Machinery group and a fair ratio estimate of 34.3x. That gap points to meaningful valuation risk if sentiment cools.
For a closer look at how those earnings multiples stack up against what the fair ratio suggests the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Graham so far. If you want to move fast and build your own angle on the upside case, start by reviewing its 2 key rewards
Looking for more investment ideas beyond Graham?
If Graham is already on your radar, it can help to widen the lens. Fresh ideas can influence your overall portfolio construction.
- Scan the 8 elite penny stocks with strong financials that already pass tighter financial filters to find early growth stories before they hit the mainstream.
- Review the 30 high quality undervalued stocks to focus on resilient businesses with room for a re rating that combine quality with compressed valuations.
- Use the list of solid balance sheet and fundamentals (24 results) to prioritise strength over headline excitement and build a watchlist anchored by financial resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com