
Arhaus (ARHS) Moved, What Is Drawing Fresh Attention Now?
Event context and why it matters for Arhaus
Arhaus (ARHS) plans to join the Bank of America Global Research Nashville Store Tour and Consumer Event on October 6, 2026, using its showroom as a live backdrop for investor conversations.
Vice President and Head of Investor Relations Tara Atwood Saja will attend in person, which will give analysts and portfolio managers a closer look at how the retailer presents its premium home furnishings brand inside a key market.
Recent trading has been volatile for Arhaus, with a 1-day share price return of 4.99% and a 7-day share price return of 24.77% on a US$9.47 stock. However, the year-to-date share price return has declined 16.64%, while the 3-year total shareholder return of 10.33% points to more mixed long run progress.
Compare Arhaus with other premium retailers by scanning a hand picked list of 16 high quality undiscovered gems that may still be flying under most investors radar.
After a sharp 7 day move and a year to date decline, Arhaus now sits in a very different spot on many watchlists. Investors may be considering whether it makes more sense to step in at US$9.47 or wait for a cleaner entry based on fundamentals.
Most Popular Narrative: 6% Undervalued
On the most followed view, Arhaus screens as slightly undervalued, with a fair value estimate of $10.12 against the recent $9.47 close. This perspective puts more weight on its long term brand and showroom strategy than on near term share price swings.
The successful execution of showroom expansion in both mature and underpenetrated markets, paired with high contribution margin design studio concepts and a growing national footprint, creates a significant runway for revenue growth and EBITDA margin improvement as Arhaus gains market share in a fragmented industry.
See why 3 investors see Arhaus as 6% undervalued.
Result: Fair Value of $10.12 (UNDERVALUED)
Still, Arhaus faces real pressure if higher fixed showroom costs meet softer demand, or if rising input and freight expenses squeeze already thin profit margins.
Find out about the key risks to this Arhaus narrative.
Another view on Arhaus valuation
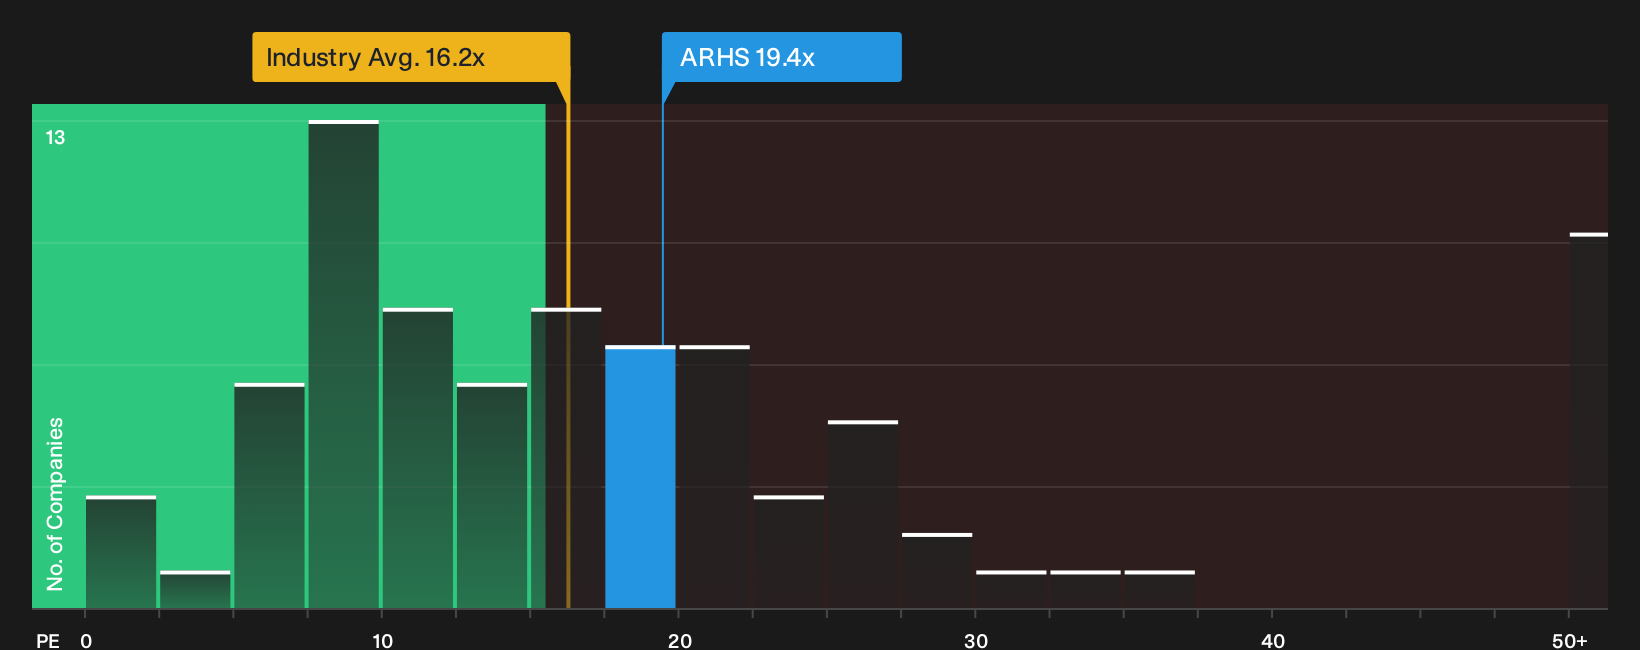
On a simple earnings multiple check, Arhaus screens very differently. The stock trades on a P/E of 19.4x, while the fair ratio points to 12.9x and peers sit nearer 15.5x and the broader US Specialty Retail group around 16.6x. That gap leans more toward valuation risk than obvious upside. Which signal do you put more weight on: the narrative of undervaluation, or the multiples on the screen?
For a closer look at how those numbers stack up against earnings power over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Arhaus valuation can be confusing, especially with both risks and potential upsides in play. Act while the facts are fresh, and pressure test the thesis yourself using the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Arhaus?
If Arhaus has you rethinking your watchlist, this is the moment to widen your search and pressure test other opportunities before the market moves first.
- Target resilient upside by scanning 30 high quality undervalued stocks that combine quality fundamentals with prices that still sit below many investors radars.
- Protect your downside by reviewing 30 resilient stocks with low risk scores that score well on balance sheet strength and lower historical volatility.
- Strengthen your core holdings by assessing a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio when conditions turn choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com