
Heiwa Real Estate REIT (TSE:8966) Could Be 50% Below Fair Value On Raised Guidance
Heiwa Real Estate REIT (TSE:8966) has just linked a fresh property acquisition to higher earnings and dividend guidance for the fiscal period ending May 2027, giving investors new information on the direction of its portfolio.
Despite the higher guidance and fresh acquisitions, Heiwa Real Estate REIT’s 1-year total shareholder return is down 10.28%, while the 3-year total shareholder return is up 4.60%. This hints that recent share price weakness and a 17.71% year-to-date share price decline sit against a more muted longer-term gain.
Scan how Heiwa Real Estate REIT’s latest guidance compares with peers that are expanding through fresh acquisitions by reviewing a curated set of 18 high quality undervalued stocks.
Heiwa Real Estate REIT is pairing fresh assets and slightly higher guidance with a weaker unit price. Does that mix still tilt the risk reward toward buyers once you look at valuation next?
Preferred P/E of 16.1x: Is it justified?
On valuation, the starting point is simple. Heiwa Real Estate REIT last closed at ¥130,100, and the stock trades on a P/E of 16.1x, which sits slightly above the Asian REITs sector level and just below the peer group average.
The P/E ratio compares the current unit price to earnings per unit. For a real estate trust such as Heiwa Real Estate REIT, it reflects how much investors are willing to pay for each unit of profit, which then gets filtered through to distributions and reinvestment decisions.
There is a mixed message in the data. The trust is labelled as expensive versus the broader Asian REITs industry on a P/E of 16.1x compared with 16x, yet it is also described as good value relative to closer peers on 17.7x. That points to a unit price that is not obviously cheap or stretched based on earnings alone, and leaves more weight on individual assessments of balance sheet strength, acquisition discipline and cash flow coverage.
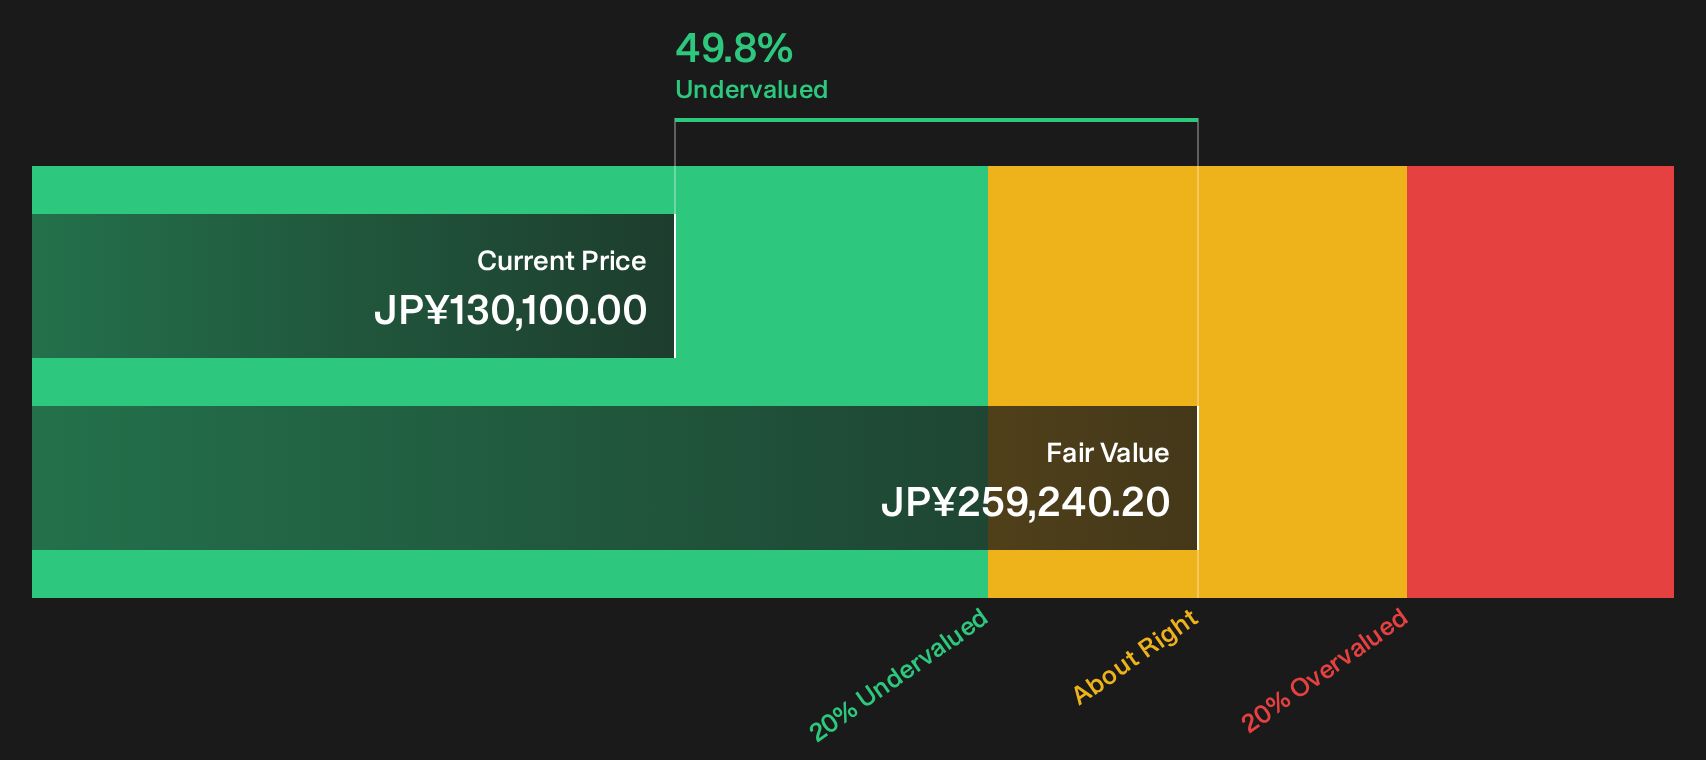
Against that backdrop, the SWS DCF estimate suggests a different story on intrinsic value, with the unit price of ¥130,100 sitting below an indicated future cash flow value of ¥259,240.20. That kind of gap, if it persists, can reflect the market applying a cautious stance to the trust's funding mix, payout coverage or growth visibility rather than simply mispricing the current earnings line.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Preferred multiple of P/E 16.1x (ABOUT RIGHT)
Still, Heiwa Real Estate REIT faces clear pressure if occupancy drops from 97.1% or if acquisition returns fail to support current distribution expectations.
Find out about the key risks to this Heiwa Real Estate REIT narrative.
Another view on Heiwa Real Estate REIT’s value
The earnings multiple paints one picture. A different angle comes from the SWS DCF model, which points to a future cash flow value of ¥259,240.20 per unit versus the current ¥130,100 price. That gap implies Heiwa Real Estate REIT screens as undervalued on this second test. The question is whether investors trust the cash flow assumptions that sit underneath it.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Heiwa Real Estate REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in Heiwa Real Estate REIT’s valuation and guidance can easily pull you in different directions, so act while the details are fresh and test the data yourself against the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Heiwa Real Estate REIT?
If Heiwa Real Estate REIT has sharpened your focus on value and income, use that momentum to scan broader opportunities and pressure test your watchlist with fresh ideas.
- Target resilient cash flow profiles and debt positions by reviewing a curated list of solid balance sheet and fundamentals (22 results) that can help anchor your portfolio when sentiment swings.
- Hunt for mispriced opportunities by scanning a focused 18 high quality undervalued stocks that pairs quality fundamentals with attractive entry points.
- Strengthen your income stream by comparing companies in a handpicked 14 dividend fortresses that concentrates on higher yields supported by financial substance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com