
COSCO SHIPPING Ports (SEHK:1199) Global Expansion Story Leaves Valuation Looking Full
COSCO SHIPPING Ports (SEHK:1199) has drawn fresh attention after recent share price moves in Hong Kong, with the stock up over the past month and past 3 months. Investors are weighing that shift against the company’s underlying fundamentals.
Recent trading has been strong, with COSCO SHIPPING Ports posting a 15.52% 1 month share price return and a 32.82% 3 month share price return. The 1 year total shareholder return of 14.23% points to momentum that has been building rather than fading.
Scan how COSCO SHIPPING Ports compares with other transportation and infrastructure plays showing strong recent moves by checking our hand picked 180 high quality undervalued stocks.
COSCO SHIPPING Ports has already moved sharply. The real tension now is whether you pay up at today’s price or sit tight and hope the valuation offers an easier entry.
Most Popular Narrative: 1% Overvalued
COSCO SHIPPING Ports last closed at HK$6.03, while the most followed narrative centers on a fair value of about HK$5.98 using a 9.09% discount rate. That small gap puts more weight on the underlying story than on any big pricing disconnect.
The company's proactive global expansion, particularly in emerging markets along key trade corridors such as Southeast Asia, South America, and the Middle East, positions it to capture rising global trade volumes and future throughput growth, this is expected to drive sustainable increases in top-line revenue.
See why 4 investors see COSCO SHIPPING Ports as 1% overvalued.
Result: Fair Value of HK$5.98 (OVERVALUED)
Still, COSCO SHIPPING Ports remains heavily tied to China-linked trade and faces rising competition in overseas terminals, which could unsettle those analyst assumptions.
Find out about the key risks to this COSCO SHIPPING Ports narrative.
Another View on COSCO SHIPPING Ports Valuation
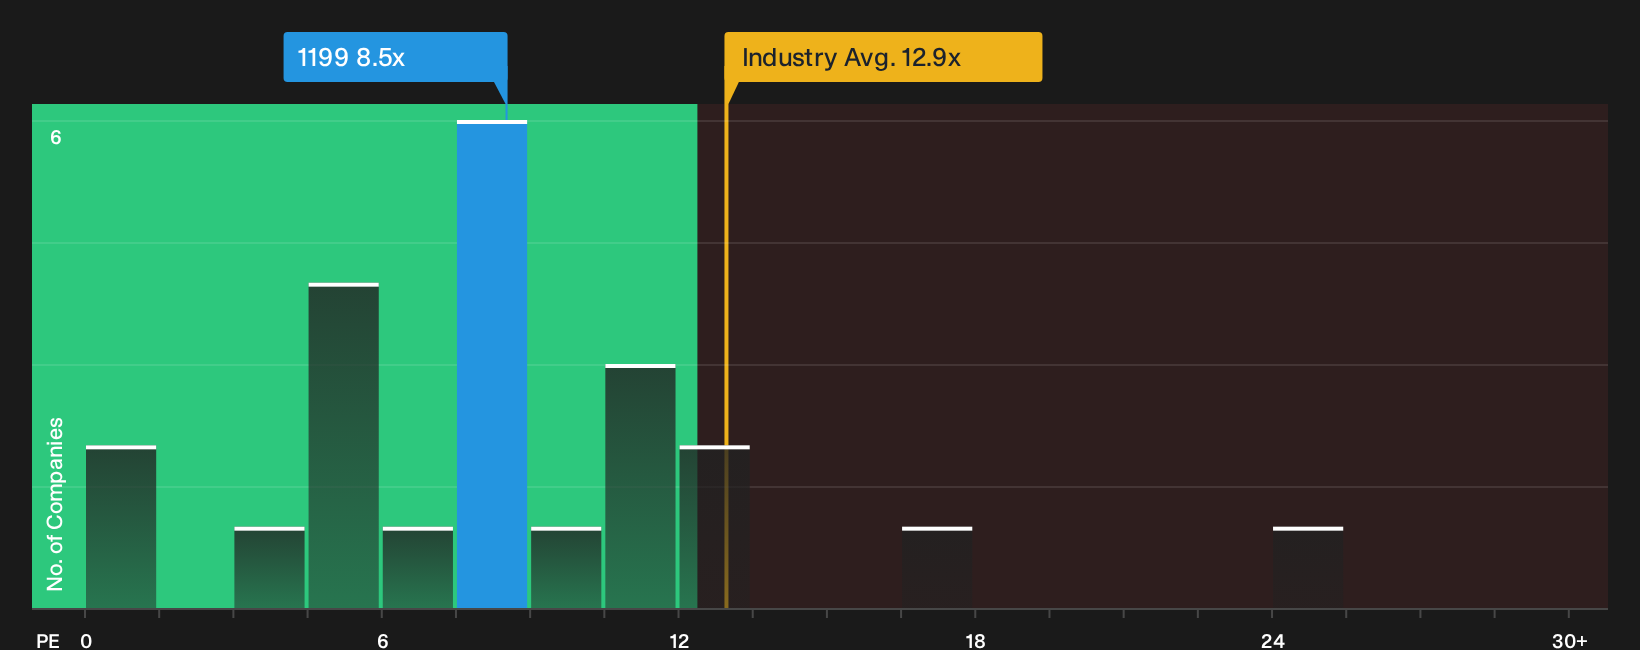
On simple earnings multiples, COSCO SHIPPING Ports looks cheaper than peers, with a P/E of 8.5x versus 10.2x for similar companies and 12.9x for the wider Asian infrastructure group. Yet the fair ratio is also 8.5x, which implies the discount may already be fully reflected. Is this a margin of safety or just fair value dressing up as a bargain?
For a closer look at how this P/E gap lines up with fundamentals, see what the numbers say in our valuation breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around COSCO SHIPPING Ports valuation and risk profile make this a judgment call, so move quickly to review the underlying data and weigh both sides with the help of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond COSCO SHIPPING Ports?
If COSCO SHIPPING Ports has caught your eye, broaden your watchlist now by scanning other opportunities that could fit your risk, income, and quality preferences.
- Target steadier compounding by reviewing a 226 resilient stocks with low risk scores that may better match your appetite for smaller drawdowns and fewer unpleasant surprises.
- Boost potential income streams by checking a 159 dividend fortresses that focuses on higher yields backed by underlying cash flows.
- Get ahead of the crowd by tracking a 618 high quality undiscovered gems that filters for strong fundamentals before they hit the spotlight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com