
Redox (ASX:RDX) Launches RDX Flex, Is It Still 12% Below Fair Value?
Redox (ASX:RDX) is in focus after the launch of RDX-Flex, a foliar-applied biostimulant that targets more efficient nitrogen use and could allow farmers to materially cut fertilizer inputs while keeping yields steady.
At around A$3.48, Redox has seen its share price slip about 14% over the past 90 days, even though the year-to-date share price return is up about 13% and the 1-year total shareholder return sits near 29%. This points to longer term momentum despite recent cooling, as the RDX-Flex launch adds a fresh talking point for where the next leg of sentiment might come from.
Scan beyond Redox and this fertilizer efficiency story to spot other agriculture and materials suppliers that could be setting up their next leg of momentum with the 16 high quality undiscovered gems.
Bulls see Redox as a growth story trading at a temporary discount after the recent pullback, while bears argue the run from the listing went too far. The question is which case today’s valuation markers support.
Most Popular Narrative: 12% Undervalued
Compared with Redox’s last close at A$3.48, the most followed narrative points to a fair value of about A$3.98, which frames the current share price as a discount built on specific growth and margin assumptions rather than pure sentiment.
Redox continues to invest heavily in its proprietary digital ERP/CRM and logistics platforms, which drives operational efficiencies, improved customer retention, and margin enhancement. These digital initiatives should help contain costs and underpin long-term EBITDA and net margin improvement.
See why 14 investors see Redox as 12% undervalued.
That storyline rests on a few key numbers. The narrative uses a discount rate of 7.94% and assumes revenue growth of about 10.1% a year, with profit margins moving from 6.3% to 6.9%. On those inputs, it lands on a fair value close to A$3.98 per share, which is around 12% above the current A$3.48 price.
Analysts within that framework also factor in earnings rising from A$80.7m to A$117.8m by around July 2029 and a future P/E of 22.3x, a touch above the AU Trade Distributors industry on 21.5x. In plain terms, the narrative assumes investors will still pay a small premium for Redox’s earnings a few years from now.
For anyone weighing that view against their own expectations on growth, margins, and what a reasonable future P/E looks like, the gap between A$3.48 and A$3.98 is the key judgment call.
Result: Fair Value of A$3.98 (UNDERVALUED)
Still, that 16.3% jump in underlying expenses and higher working capital needs leave Redox exposed if wage pressure, inventory build or softer North America demand persist.
Find out about the key risks to this Redox narrative.
Another View on Redox’s Valuation
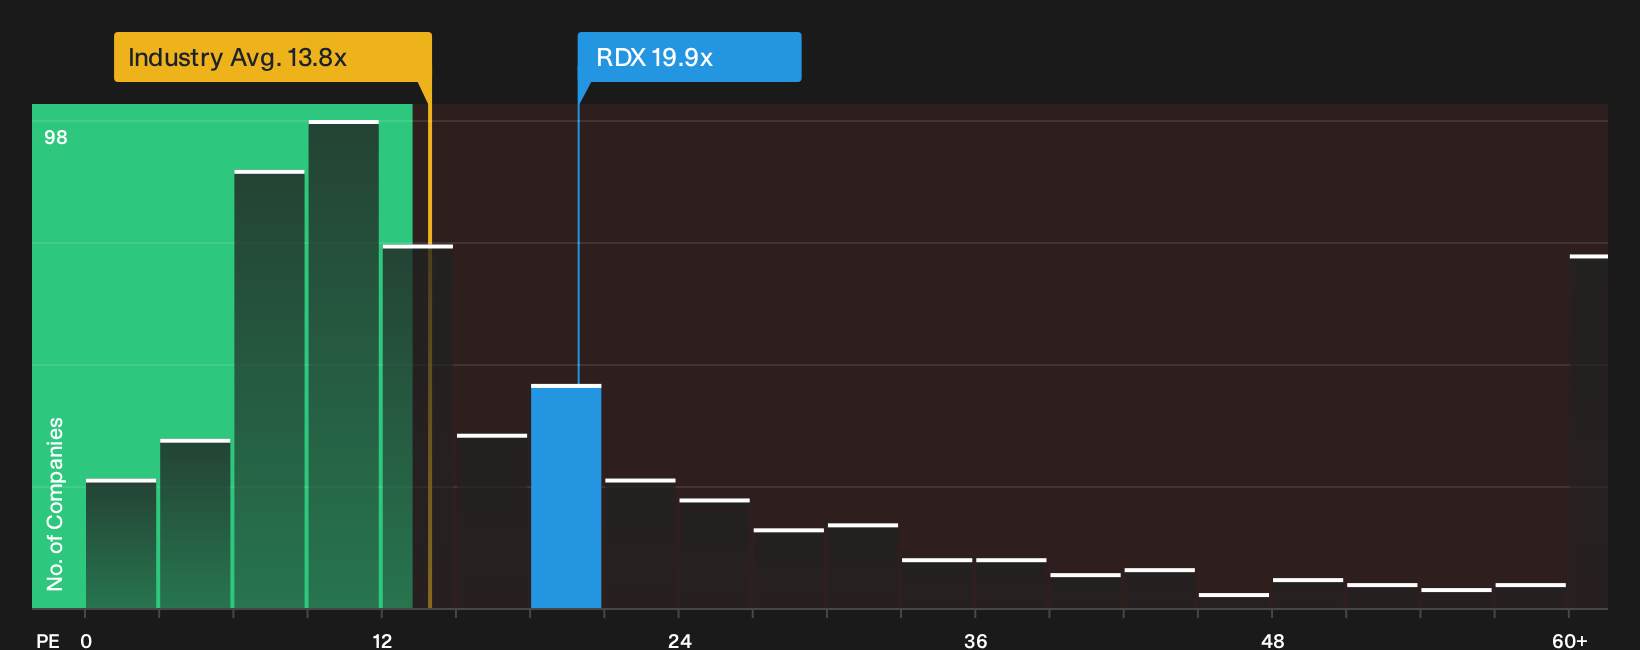
The narrative fair value implies Redox is 12% undervalued at A$3.48, yet the P/E picture sends a cooler signal. The current P/E sits at 19.9x, only slightly below the local Trade Distributors average of 20.3x and above the global industry on 13.8x, while the fair ratio for Redox is 19.2x. That leaves only a thin margin of safety on earnings, so investors may want to consider how much valuation risk they are willing to take relative to the growth on offer.
For a closer look at how those earnings multiples compare with peers and the fair ratio that the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed mood around Redox leaves you uncertain, consider reviewing the data quickly to test the underlying assumptions and assess the potential upside yourself. To see the optimistic factors that analysts are focusing on, start with the 3 key rewards.
Looking for more Redox investment ideas?
Do not stop at Redox. Use the Simply Wall St screener to spot fresh opportunities, compare setups quickly, and pressure test your own thesis in minutes.
- Target potential mispricings early by reviewing companies that show up in the 5 high quality undervalued stocks.
- Prioritize income reliability by focusing on companies screened as 3 dividend fortresses.
- Lean toward resilience by concentrating on businesses that meet the criteria in the 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com