
3 Australian Owner Operator Stocks To Own In September 2026
Global bond markets are selling off and long-term yields are climbing, which puts pressure on companies that rely heavily on cheap debt and short-term market sentiment. Founder-led Australian businesses often sit on the other side of that equation. Leaders with meaningful skin in the game tend to think in decades, not quarters. This article highlights three founder-run stocks from our screener that show how that mindset can matter when conditions get tougher.
The three founder-led stocks covered below are only a small sample, as the wider screen surfaced another 82 businesses with similarly committed leadership stories that are not unpacked in this article. If you want to identify and analyze those additional founder-backed ideas in detail, head straight to the Founder-Led Companies screener.
Macquarie Technology Group (ASX:MAQ)
Overview: Macquarie Technology Group runs founder-led telecom, cloud, cybersecurity and data centre services for Australian government and corporate customers.
Operations: The group generates about A$235 million from Cloud Services & Government, A$105 million from Telecom and A$87 million from Data Centres, almost entirely in Australia.
Market Cap: A$1.4b
Macquarie Technology Group ties the founder-led idea directly to mission critical cloud, security and telecom services for government and large enterprises, with revenue of A$390 million and net income of A$32 million in the year to June 2026. Investors attracted to long-term owner-operator thinking may be interested, depending on how one unseen pressure shapes future profitability against that premium valuation.
That pressure point is already baked into the current share price story, so it is worth sizing it properly through the DCF valuation analysis for Macquarie Technology Group before judging how Macquarie Technology Group’s future returns could decouple from headline earnings.
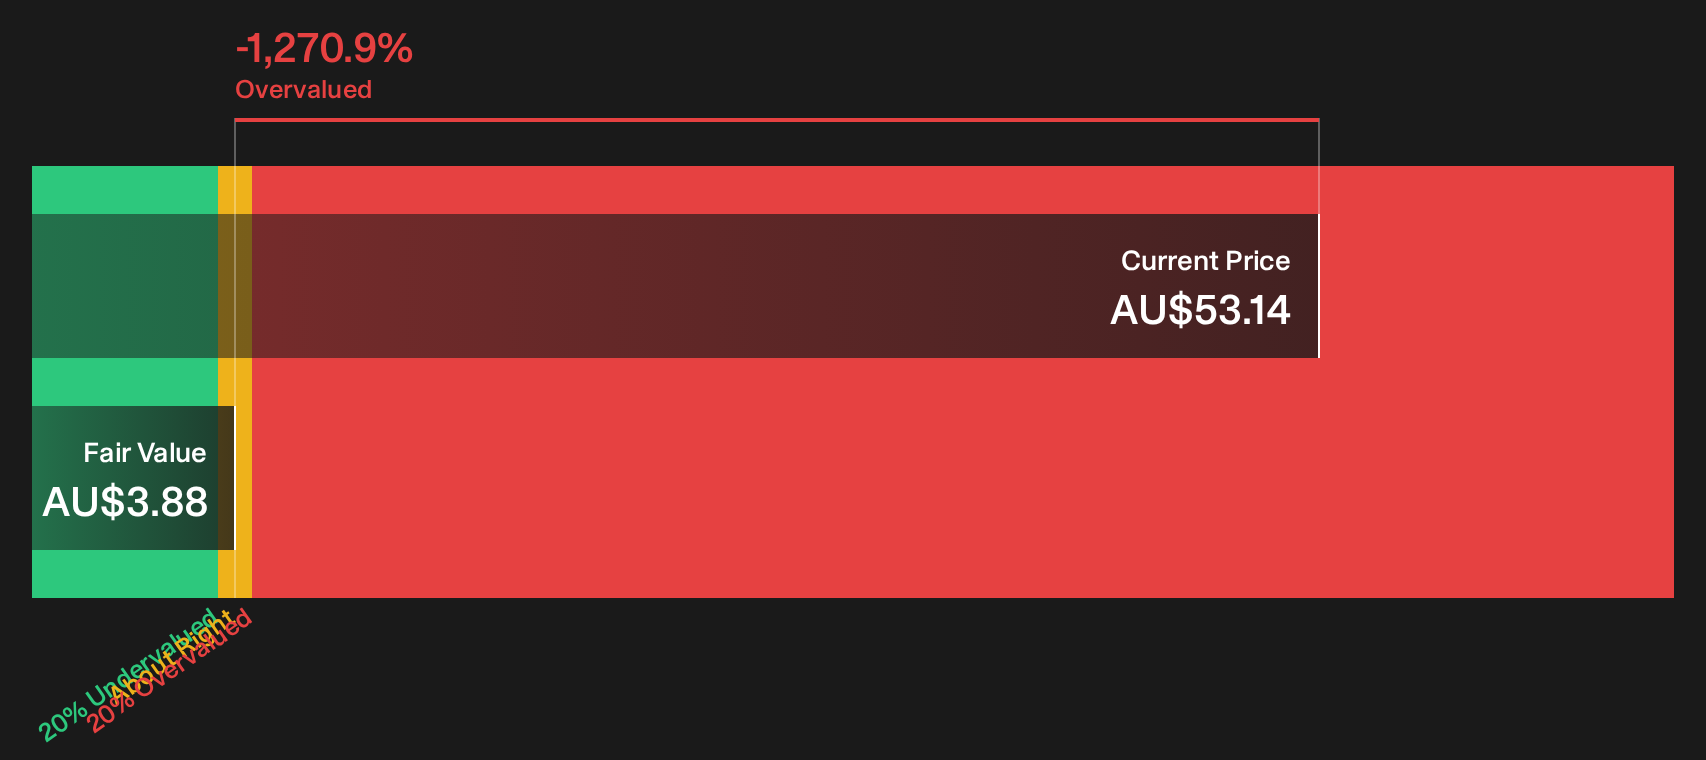
Mesoblast (ASX:MSB)
Overview: Mesoblast develops founder-led regenerative cell therapies using mesenchymal lineage cells to treat severe inflammatory and cardiovascular conditions.
Operations: Mesoblast currently generates about $120 million from developing and commercializing its allogeneic cellular medicines platform.
Market Cap: A$2.8b
Mesoblast fits the founder-led theme through Dr. Silviu Itescu’s long tenure and focus on building a mesenchymal cell platform into a durable franchise. Investors are effectively backing a scientist-founder who has committed his career to a single therapeutic approach rather than a rotating set of short-term projects.
"The first and only FDA approved mesenchymal stromal cell product in the U.S., Ryoncil, together with over 1,100 patents and established commercial scale manufacturing, positions Mesoblast to benefit if cell therapies gain wider medical adoption."
What really matters from here is how one key set of late-stage trial readouts reshapes the balance between cash burn and future pricing power.
If that cash burn and pricing power balance matters to you, read the full narrative for Mesoblast to see how Mesoblast’s risk profile could shift as adoption accelerates.

Harvey Norman Holdings (ASX:HVN)
Overview: Harvey Norman Holdings runs founder-influenced furniture, bedding, electronics and electrical retail chains, alongside property ownership and leasing tied to those stores.
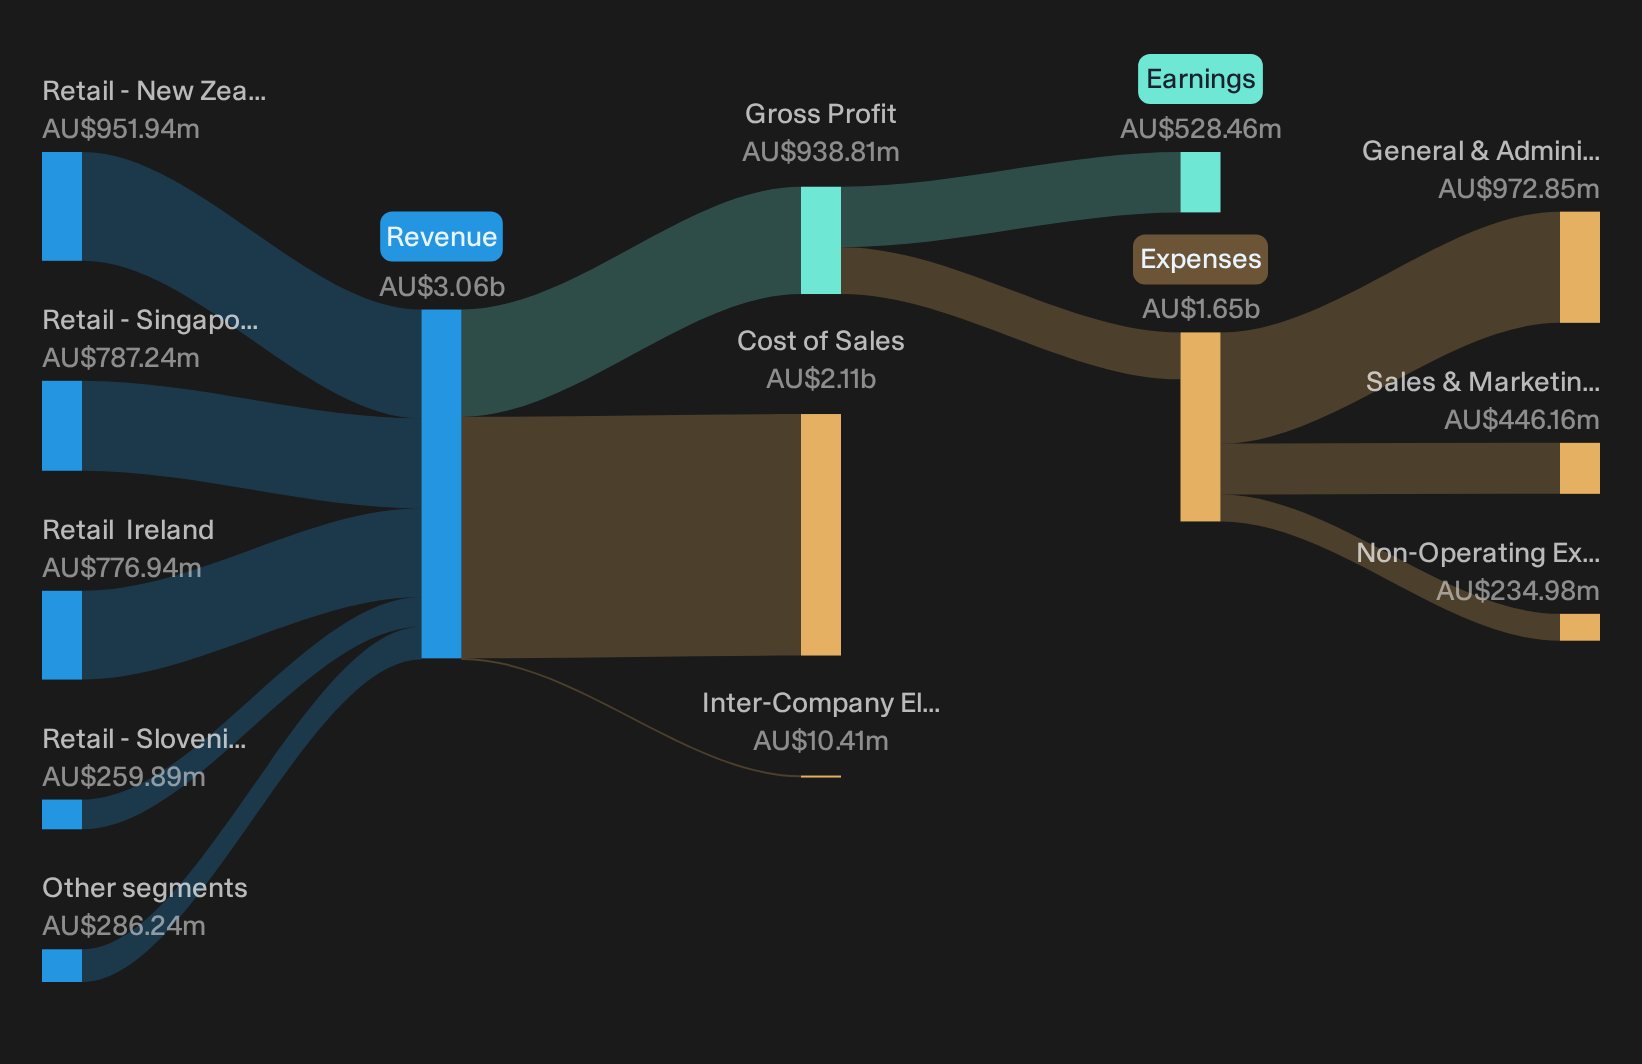
Operations: Harvey Norman Holdings generates most of its revenue from international and non franchised retail stores, led by New Zealand, Ireland, Singapore and Malaysia.
Market Cap: A$5.2b
Harvey Norman matters for a founder-led screen because co founder and executive director Gerry Harvey still shapes how the retail and property engine is run. This links day to day decisions on store networks and property assets directly to long standing owner influence.
"It is worth noting, however, that just over 20% of 2025 profit can be attributed to property revaluations, non-cash gains that can be volatile and are not recurring operational earnings."
The key test for that founder backed model now is how any shift in underlying operating momentum flows through to future retail and property margins.
If that profit mix keeps you curious, read the full narrative for Harvey Norman Holdings to see whether property gains are masking pressure or setting Harvey Norman up for a stronger cycle.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first, and late money can end up chasing momentum after a breakout. Look under the radar while interest is still limited and consider acting early, when it can have more impact.
- Track cash rich potential compounders by scanning a curated list of solid balance sheet and fundamentals (12 results) that keeps weaker balance sheets out of your shortlist.
- Focus on potential income generators using a pre filtered 3 dividend fortresses designed to highlight payout strength with room for resilience if conditions tighten.
- Align with structural technology shifts by filtering for curated 84 AI infrastructure stocks that support demand for data, chips and high capacity networks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com