
Smurfit Westrock (SW) Stock May Trade At A Premium After $420 Million Deal
Smurfit Westrock has delivered a 57.7% share price gain over the past three years, and that kind of move naturally puts the spotlight on whether the current price still lines up with its earnings power. With the stock now trading around $46.00 after a mixed short term run, the key issue for you is how much of the business’s profit story is already built into that tag.
- A 57.7% return over three years puts meaningful expectations on Smurfit Westrock, which raises the question of how much earnings strength the current valuation assumes.
- The agreed US$420 million acquisition of Empresas CMPC’s Chilean containerboard and corrugated operations may support future profit potential in Latin America, but it also adds timing questions around integration costs and cash generation.
- Your read on Smurfit Westrock is one view; the desks covering it have another. See what analysts think Smurfit Westrock's shares could be worth.
The stock's next move may depend on whether Smurfit Westrock's current earnings profile is strong enough to justify the price investors are paying today.
If you want more context around Smurfit Westrock's earnings-driven valuation story, it can help to compare it with other companies screened for 30 high quality undervalued stocks
Has Smurfit Westrock Run Too Far on Earnings?
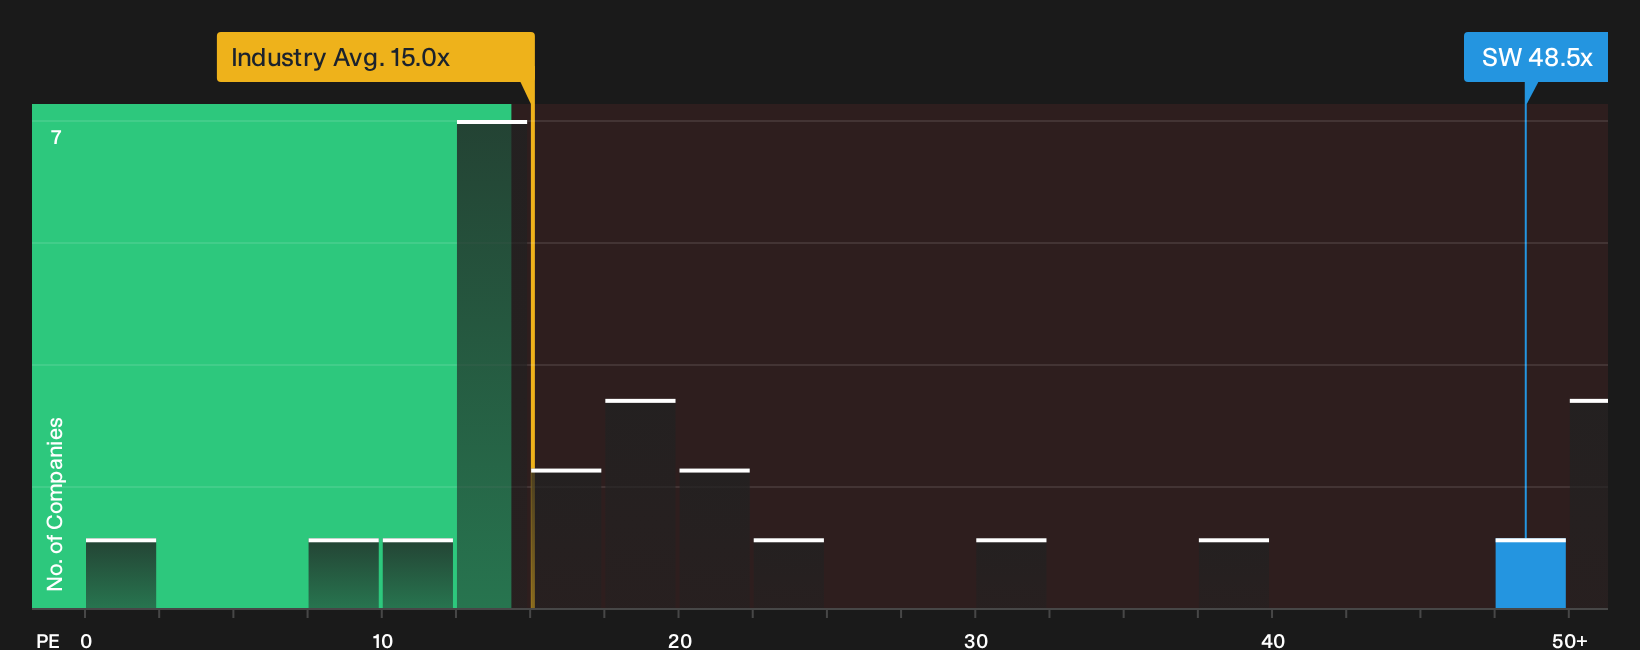
The P/E ratio suits Smurfit Westrock because earnings are a core focus for how investors value established packaging groups. On this yardstick, the stock trades at about 48.5x earnings, which is more than double the Packaging industry average of roughly 15.0x and well above the broader peer group on about 18.5x. That is a rich headline number for a business in a relatively mature sector, so the earnings that sit behind it matter a lot for your thesis.
The Fair Ratio model, which blends in Smurfit Westrock’s margins, growth profile, scale and risk, points to a lower multiple than the current 48.5x, so the shares screen as overvalued on this framework. Because the agreed US$420m CMPC acquisition is still several years from expected completion, the market is effectively paying a premium P/E today while waiting to see how those Chilean assets contribute to profit over time. That gap between the earnings being generated now and the price you pay per dollar of profit is the key trade off to weigh before assuming the stock is still attractively priced on this metric. Explore the numbers behind Smurfit Westrock's P/E valuation.
The Smurfit Westrock Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Smurfit Westrock by spelling out which mix of future growth, profit margins and earnings power would need to play out for the shares to look meaningfully cheaper or more expensive than they do today. Each one ties a fair value range to a specific storyline around the company's possible catalysts and risks, so you can track over time which version seems closest to reality on Simply Wall St's Community page.
One of the top community narratives on Smurfit Westrock: roughly fairly valued
"Although Smurfit Westrock is investing roughly US$2.4 billion to US$2.5 billion per year in asset upgrades and efficiency projects, the combination of a reduced EBITDA guidance range and a low Altman Z-Score raises the possibility that elevated capital spending limits flexibility..."
Discover why this Narrative puts Smurfit Westrock at roughly fairly valued.
Smurfit Westrock’s valuation is only part of the story
Before acting on where Smurfit Westrock trades today, it helps to weigh the specific risk checks our research has already flagged and decide how much those issues matter for you. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com