
Is Record Orders Altering The Investment Case For Allient (ALNT)?
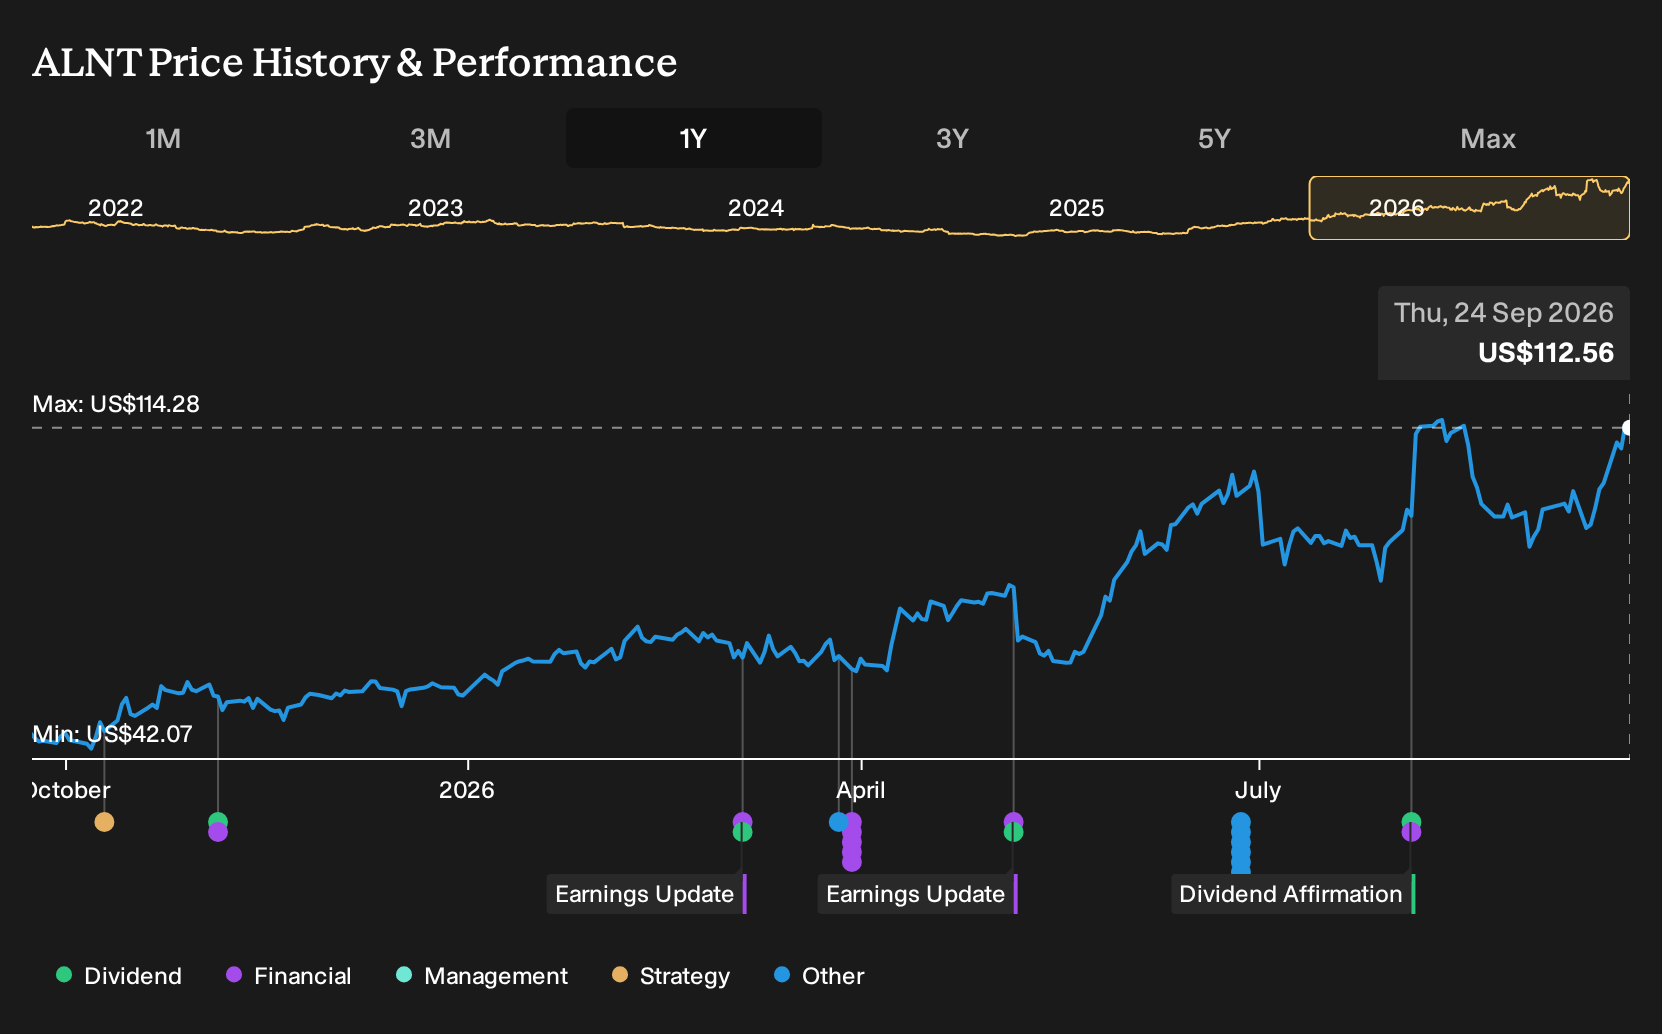
- Allient reported record orders, a sizeable backlog and margin expansion. Together, these factors support management’s expectation that most booked work converts to revenue within three to nine months.
- The combination of a growing backlog and rising earnings estimates indicates that Allient’s recent commercial wins are translating into near term operating visibility rather than one off demand.
- We will now look at how Allient's record backlog and revenue timing visibility could reshape the existing investment narrative around the company.
Extend your research beyond Allient and scan a hand picked list of industrials with growing order books and improving profitability using the list of solid balance sheet and fundamentals (24 results).
Allient Investment Narrative Recap
To own Allient, you need to believe that its record backlog, margin progress and mix shift toward higher value sectors can translate into durable earnings quality, not just a short burst of activity. The latest spike in orders and revenue visibility reinforces that thesis by tightening the link between booked work and near term cash generation.
The flip side is execution risk. If demand in automation, data centers or aerospace slows, or if supply chain and regulatory costs rise, the current backlog could prove less repeatable than it looks. In the short term, the key swing factor remains how efficiently Allient converts this order book into profitable shipments.
The most relevant development tied to this news is the reported record orders and growing backlog at Allient, paired with management’s three to nine month revenue conversion window. That combination gives you clearer sight on near term activity levels and helps frame how current demand flows through to margins and earnings.
This operational backdrop matters for every current catalyst. The recovery signs in industrial automation, ongoing demand in data centers, aerospace and defense, and the Simplify to Accelerate NOW efficiency program all depend on consistent execution against that backlog. Any stumble in delivery, pricing or cost control would quickly test the strength of this recent order momentum.
What The Allient Forecasts Assume
Allient's narrative projects US$727.9 million in revenue and US$56.3 million in earnings by 2029. This rests on analysts assuming 8.2% yearly revenue growth and an earnings increase of about US$27.7 million from US$28.6 million today.
Uncover why Allient's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For a very different angle on Allient, focus on obsolescence risk. The most cautious analysts worry that a tilt toward software heavy motion control could leave hardware centric offerings behind. Before this backlog news, the bearish camp still penciled in about US$729.0 million of revenue and US$56.8 million of earnings by 2029, yet settled on a US$90.0 target. That contrast shows how far opinions can stretch. Use this range to test your own view, then consider how fresh information might pull those narratives closer together or push them further apart.
Explore 2 other Allient fair value estimates, including one that suggests as much as 53% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Allient research is our analysis highlighting 2 key rewards and 1 important warning sign that could inform your investment decision.
- See our latest analysis for Allient. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Allient's overall financial health at a glance.
Looking For More Investment Ideas Beyond Allient?
If Allient has sharpened your thinking about earnings quality and backlog visibility, broaden that lens to other companies using the Simply Wall St Screener. You can filter for balance sheets, income strength or income streams that better match your own risk tolerance and return goals.
- If you want potential upside with strict balance sheet discipline, start with a list of solid balance sheet and fundamentals (24 results) that already screen well on financial strength and fundamentals.
- For investors hunting for quality at a reasonable entry point, narrow your focus to companies flagged as 30 high quality undervalued stocks based on cash flows and balance sheet support.
- Income focused readers can concentrate on reliable cash distributions by reviewing a curated set of 8 dividend fortresses that combine higher yields with robustness checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com