
Korn Ferry (KFY) Stock Could Be Undervalued Even After A 63% Run
Korn Ferry has delivered a strong multi‑year run, yet the recent pullback in the share price puts fresh focus on a simple question: Is today's valuation still supported by the earnings power of this people and consulting business?
- The stock has returned 62.5% over the past 3 years, which raises the issue of how much of Korn Ferry's earnings strength is already reflected in the price.
- As an advisory and talent-focused firm that leans heavily on fee-based work and human capital, Korn Ferry's ability to sustain margins and convert profit into cash can shape how much investors are willing to pay for each dollar of earnings.
- The analysts covering Korn Ferry have run their own numbers. See what analysts think Korn Ferry's shares could be worth.
For investors, the debate is whether Korn Ferry's current share price is appropriately aligned with the earnings it generates today and what those profits may reasonably support over time.
If you want to test the same earnings question you are asking of Korn Ferry against a wider universe, compare it with companies in the 30 high quality undervalued stocks
Is Korn Ferry a Bargain on Earnings?
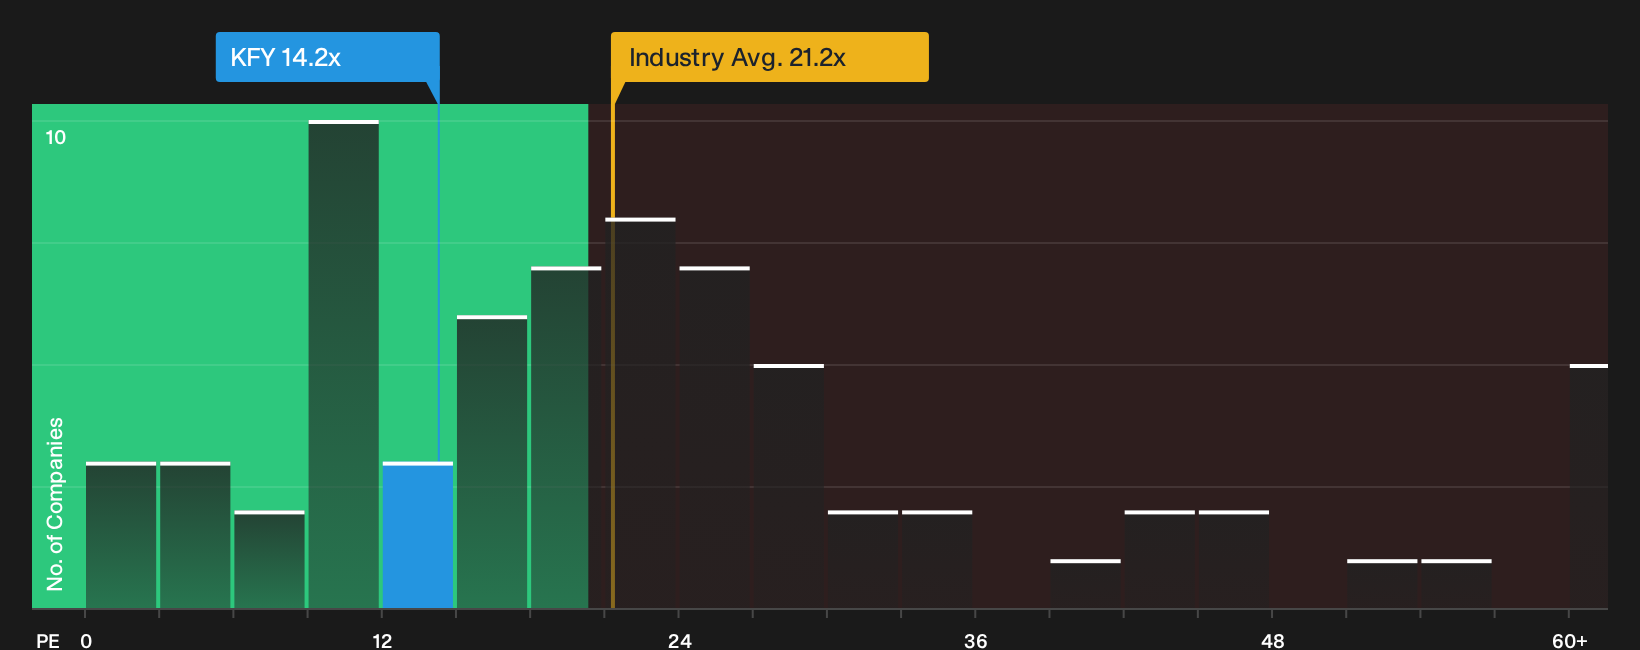
A P/E lens fits Korn Ferry because earnings quality matters a lot for a people-heavy consulting group where cash flow is closely tied to fee income. On that measure, Korn Ferry trades on a P/E of about 14.2x, compared with roughly 21.2x for the wider Professional Services industry and around 20.8x for its peer group. That is a sizeable gap in how the market prices each dollar of profit.
The fair multiple implied by the valuation framework, which blends the company’s growth profile, profitability, sector and risk, sits meaningfully above the current 14.2x P/E. For an investor weighing Korn Ferry against other listed advisers, the stock appears undervalued on this earnings yardstick, with the market applying a lower price tag to its current profit stream than the model would suggest. Explore the numbers behind Korn Ferry's P/E valuation.
The Korn Ferry Narrative: What Would Justify Today's Price?
Simply Wall St Narratives continue from this valuation puzzle for Korn Ferry by explaining which combinations of future growth, profitability and earnings power would need to hold for the current share price to appear significantly higher or lower than it does today. Each scenario is tied to its own view of fair value, catalysts and key risks, so you can track over time which version of events comes closest to reality on the Community page.
One of the top community narratives on Korn Ferry: 20% undervalued
"Korn Ferry has secured significant transformation engagements with major global companies, indicating a strong demand for their services in strategic transformation and workforce transformation..."
Discover why this Narrative puts Korn Ferry at 20% undervalued.
One more Korn Ferry check that belongs beside the earnings multiple
The missing piece is who sits in Korn Ferry's cockpit and how that leadership team is rewarded, because incentives shape decisions and risk appetite in ways the share price alone cannot show. See who runs Korn Ferry and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com