
China Motor Bus (SEHK:26) Stock Trades Rich As Revenue Slides And Losses Linger
China Motor Bus Company closed at HK$59.0 after the latest full-year scorecard, with the share price still reflecting a premium story while the earnings tell a much harsher one. The firm has stayed in loss-making territory over the past year, with trailing net income from continuing operations down at HK$120.174 million and basic EPS at a loss of HK$2.66. That profit squeeze coincides with a rich P/S multiple near 29x and a market value that sits far above a discounted cash flow estimate, which puts the long-term risk-reward trade-off firmly in focus.
Love the premium pricing story but concerned about loss-making earnings and a rich P/S multiple? Check out the 178 high quality undervalued stocks.
FY 2026 Earnings Summary
- Revenue (FY 2026 TTM vs. FY 2025 TTM): HK$92.698 million vs. HK$166.286 million (top line declined)
- Net Loss from Continuing Operations (FY 2026 TTM vs. FY 2025 TTM): HK$120.174 million loss vs. HK$184.504 million loss (loss size changed)
- Basic EPS (FY 2026 TTM vs. FY 2025 TTM): HK$2.66 loss per share vs. HK$4.08 loss per share (per share loss changed)
- Second Half FY 2026 Revenue vs. Second Half FY 2025: HK$25.671 million vs. HK$79.169 million (second half sales contracted)
Prefer clean visuals instead of endless rows of figures and dense earnings notes? See China Motor Bus Company's full picture with a clear view of its valuation trade off in the company report for China Motor Bus Company.
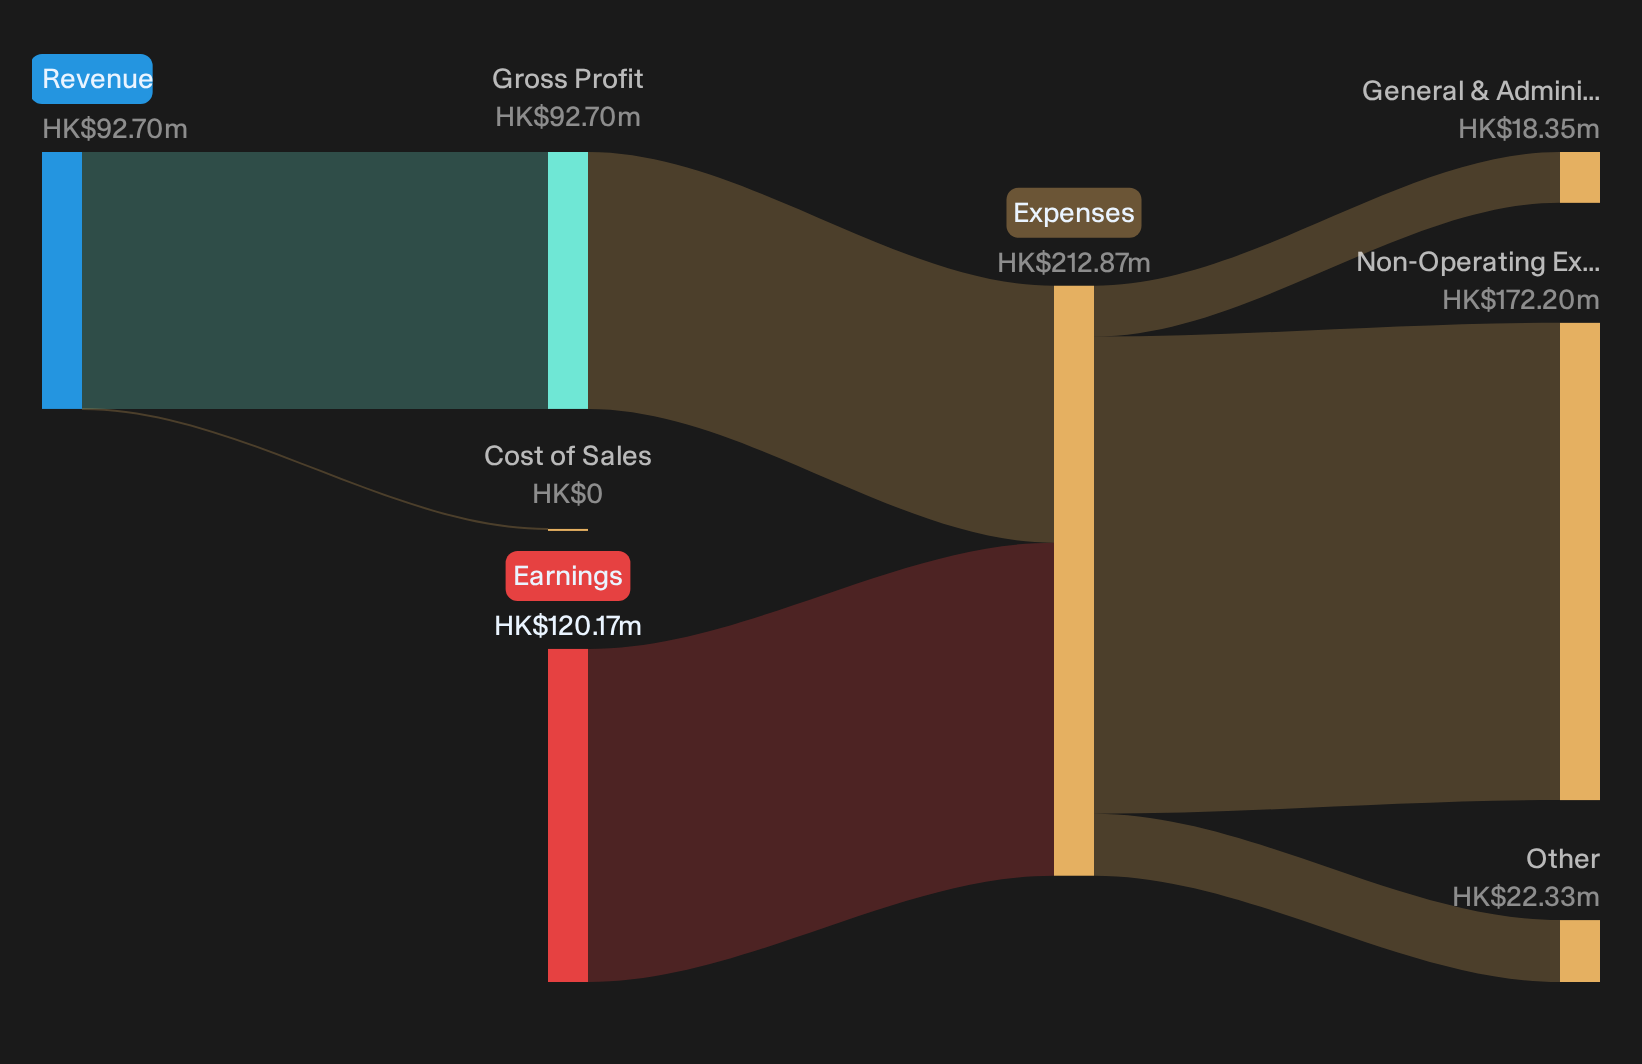
China Motor Bus bullish story faces mixed signals
For anyone leaning toward a positive view on China Motor Bus, the shrinking loss from continuing operations and smaller per share loss provide one supportive thread. The business is still in the red, but the direction of earnings points to some pressure easing compared with the previous year. That matters for a property and treasury focused group where patience is often tied to capital discipline. Recent share price gains over 7 and 90 days also suggest investors have not abandoned the asset based story despite weaker revenue.
Bearish concerns anchored in revenue strain
The bear case finds more immediate support in the top line. Revenue for the full year and the second half both fell sharply, which challenges any narrative that the underlying portfolio is quietly compounding cash flows. China Motor Bus is still reporting a sizeable loss, so the improvement in earnings does not yet translate into profitability. When income falls while operations remain loss making, it raises questions about how quickly any asset value or treasury returns can feed through to the income statement and justify ongoing optimism.
After several years of shrinking earnings and a dividend that is not well covered, it is fair to ask whether the current losses and revenue strain at China Motor Bus Company hint at deeper structural pressure. Before drawing a conclusion, Review the risk analysis for China Motor Bus Company which shows 2 important warning signs.Own Your Next Investment Move
China Motor Bus Company trades on a rich story but carries loss-making earnings, which makes timing and entry price especially important, so register for free with Simply Wall St and add it to a Watchlist to track the share price against fair value before committing capital. After you build a position, keep your decisions clear with the Portfolio Command Center that focuses your view on key developments that matter for your holdings. For a longer term plan, tap into crowd insights and different angles on China Motor Bus Company through the Community to see how other investors are reading the same numbers. Spotting potential catalysts and watching for early warning signs in one place helps you react faster and stay ahead of the market.
Seeking Fresh Alternatives Beyond China Motor Bus
Some opportunities move from quiet accumulation to breakout momentum before most investors even notice. Scan fresh ideas while they are still under the radar for now and act now.
- Spot robust cash generators before momentum traders pile in by reviewing the curated 618 high quality undiscovered gems that still trade as if few investors are paying attention.
- Track resilient performers that aim to hold up when sentiment turns by working through the hand picked 227 resilient stocks with low risk scores, which is built around tougher risk filters than a basic screener.
- Hunt for consistent income streams while yields are still flying above savings rates using the focused 160 dividend fortresses, which is geared toward payout durability as well as headline yield.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com