
Is Meitav Investment House (TASE:MTAV) Cheap As Fresh Business Data Tests Its Valuation?
Meitav Investment House (TASE:MTAV) has drawn fresh attention after publishing its August 2026 business data, highlighting NIS 479.6b in assets under management for more than 1.6 million clients.
Set against that operational update, Meitav Investment House’s share price has been choppy in the short term, with the stock down 2.13% over the past day even after a 7.00% 1 month share price return from a recent trough. For long term holders, the story looks very different, with a 1 year total shareholder return of 45.92% and a 3 year total shareholder return that is more than 8x. This suggests that recent monthly momentum sits within a much stronger multi year rerating driven by changing expectations for the business and its risks.
Scan Meitav Investment House’s latest move in context by comparing it with a hand picked 618 high quality undiscovered gems that also pair scale with strong underlying fundamentals.
After a strong multi year run and a modest pullback this week, the key question around Meitav Investment House is whether the current valuation still offers enough potential reward for the level of risk involved.
Price-to-Earnings of 10.9x: Is it justified?
Valuation on Meitav Investment House today revolves around a relatively low P/E of 10.9x against a last close of ₪119.3, which points to a cheaper earnings tag than many peers despite the strong multi year share price run investors have already seen.
The P/E ratio compares what you pay for each ₪1 of reported profit. For an investment manager such as Meitav Investment House, that single figure captures how the market is weighing current earnings against expectations for future profitability and the volatility that can come with capital markets activity.
On the numbers provided, the stock trades at a P/E of 10.9x compared with 14.5x for its peer group and 15.5x for the broader Asian capital markets industry. That is a clear discount, which suggests the market is assigning a lower earnings multiple than both direct competitors and the wider sector.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 10.9x (UNDERVALUED)
Still, the Meitav Investment House story can be knocked off course by weaker capital markets activity or regulatory shifts that squeeze fee pools and profitability.
Find out about the key risks to this Meitav Investment House narrative.
Another View on Meitav Investment House’s Value
The P/E picture presents Meitav Investment House as cheap. The SWS DCF model presents a very different view. On that framework, the stock at ₪119.3 sits well above an estimated future cash flow value of ₪31.02, which indicates a rich price rather than a bargain.
If earnings-based pricing appears appealing while the SWS DCF model indicates overvaluation, it raises a simple question for you as an investor: Which signal matters more for your own risk tolerance, current profits or long range cash generation?
Look into how the SWS DCF model arrives at its fair value.
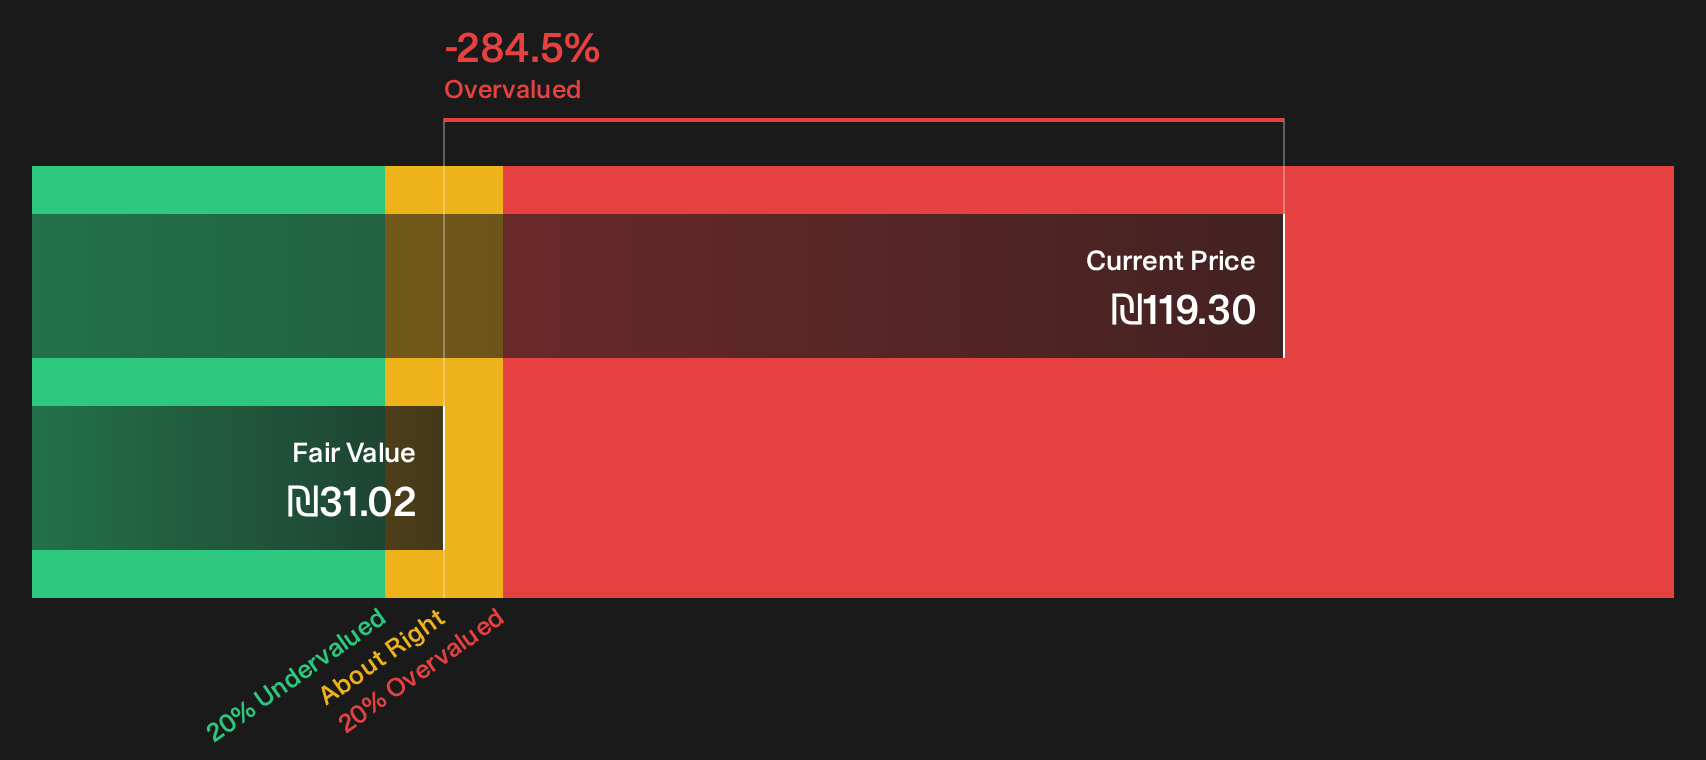
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Meitav Investment House for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Meitav Investment House can feel confusing. Review the numbers, weigh the mood, and act quickly to build your own thesis with the help of 3 key rewards and 3 important warning signs
Looking for more Meitav Investment House sized opportunities?
If Meitav Investment House has sharpened your focus on quality, do not stop here. Use this momentum to widen your watchlist with fresh, data driven ideas.
- Target rock solid balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (202 results) that could help anchor your portfolio.
- Hunt for mispriced quality by scanning the 178 high quality undervalued stocks that match strong financials with potentially appealing entry points.
- Prioritise resilience and capital preservation by checking the 227 resilient stocks with low risk scores that may help smooth returns when conditions turn choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com