
What Could Constellation Brands (STZ) Do With A $300 Million Term Loan?
- Constellation Brands (NYSE: STZ) entered a new term loan credit agreement that allows up to US$300 million of borrowing capacity.
- The facility can be used for general corporate purposes, including debt repayment, under terms that vary with the firm's credit rating.
- The agreement includes new covenants and links to existing credit facilities associated with the Sands family, which affects Constellation Brands' capital structure.
- The new US$300 million term loan credit agreement is important, but investors should weigh it alongside other key factors. Check out 1 warning sign that Constellation Brands investors should know about.
Constellation Brands is not the only large beverage business using flexible financing, so it is worth comparing it with peers exposed to similar income themes through 7 dividend fortresses.
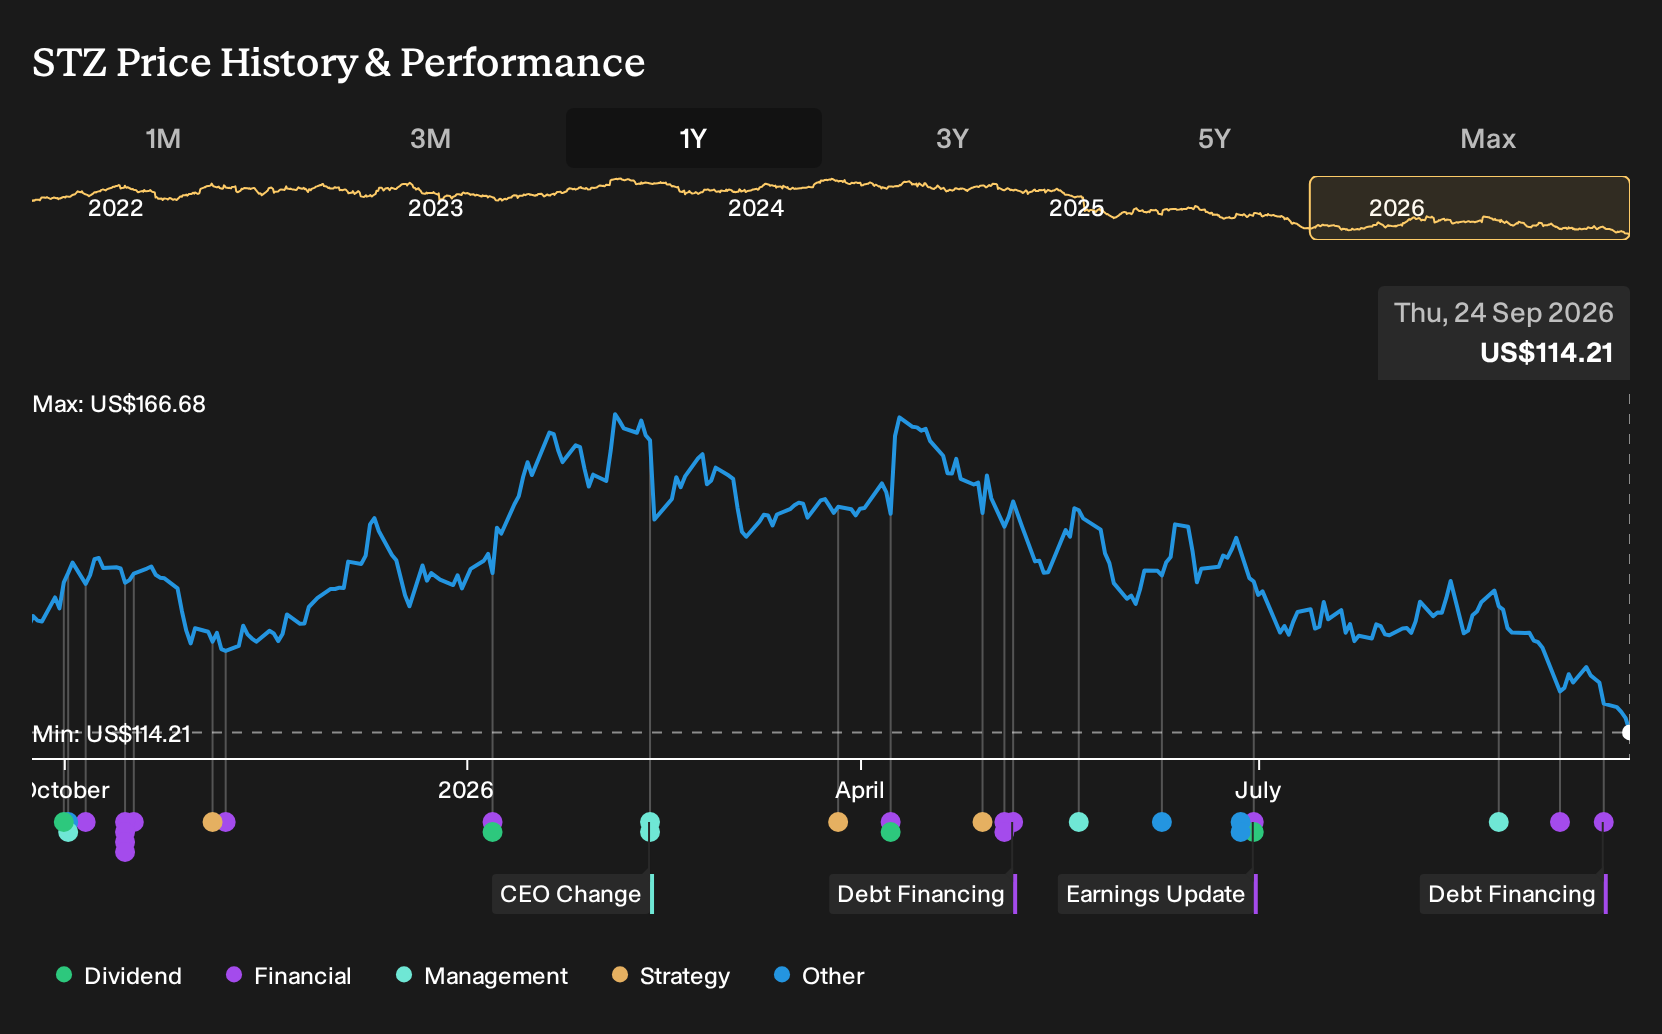
Constellation Brands runs a large US$19.9b beverage platform across beer, wine, and spirits in markets such as the United States, Canada, Mexico, New Zealand, and Italy. As a result, added lending capacity feeds into decisions on how it funds that broad portfolio of brands and distribution.
See how Constellation Brands's balance sheet measures up.
How does the new US$300 million credit agreement change Constellation Brands’ balance sheet options?
The delayed draw structure gives Constellation Brands up to two draws of term debt that it can match to specific cash needs rather than taking the full amount upfront. It can route the money into general corporate uses or refinancing, which may shift the mix between short term facilities, bonds, and cash on hand. That flexibility could affect both total leverage and interest costs depending on how much it chooses to draw.
What do the covenants tell you about Constellation Brands’ leverage and interest coverage?
The credit deal hardwires a minimum consolidated interest coverage ratio of 2.50x and a maximum consolidated net leverage ratio of 4.00x, with a temporary 4.50x ceiling after a material acquisition. These tests, plus restrictions on extra subsidiary debt and liens, put bookends around how aggressively the group can add borrowings. For readers, they frame the guardrails for debt funded expansion, buybacks, or restructuring moves.
Does this new debt capacity change the Constellation Brands Narrative?
The community Narrative leans heavily on plans for US$9b in operating cash flow, US$6b in free cash flow, brewery expansion in Mexico, and a US$4b buyback program. Extra term loan headroom could support that capital plan or refinancing if cash generation timing is bumpy, but it also adds another layer of commitments on a business already flagged as having a high level of debt.
See how these catalysts shape Constellation Brands' path to a $171 fair value.
What should investors watch next to see if this facility really matters?
The key test is when and how Constellation Brands actually taps the loan between now and June 18, 2027, and whether those draws go mainly to refinancing or to new spending. Investors can track future filings and earnings materials for disclosed term loan balances, changes in the consolidated net leverage ratio, and any material acquisition that triggers the 4.50x step up.
One valuation question Constellation Brands investors still have to answer
All of this leaves one missing piece that matters for every shareholder. Independent models use the cash flowing through Constellation Brands to estimate what the whole business could be worth beside today’s share price. Find out exactly what Constellation Brands is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com