
Global Growth Companies With High Insider Ownership For September 2026
In September 2026, global markets have been navigating a complex landscape marked by rising interest rates and fluctuating oil prices due to geopolitical tensions, with growth stocks notably outperforming their value counterparts. Amidst these conditions, companies with high insider ownership often attract attention as they can indicate strong alignment between management and shareholder interests, potentially offering resilience in volatile times.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 112.1% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
We'll examine a selection from our screener results.
VM (KOSDAQ:A089970)
Simply Wall St Growth Rating: ★★★★★☆
Overview: VM Inc. manufactures and sells dry etcher systems for semiconductor production processes both in South Korea and internationally, with a market cap of ₩1.64 trillion.
Operations: The company generates revenue of ₩248.48 billion from its semiconductor equipment and services segment.
Insider Ownership: 19%
Revenue Growth Forecast: 23.6% p.a.
VM Inc. is poised for significant growth, with earnings expected to increase 26.18% annually over the next three years, despite recent shareholder dilution and high share price volatility. The company trades at a substantial discount to its estimated fair value and boasts a high forecasted return on equity of 32.8%. Recent financial results showed remarkable net income growth from KRW 2,100.64 million to KRW 17,905.82 million year-over-year for Q2 2026.
- Click here and access our complete growth analysis report to understand the dynamics of VM.
- Upon reviewing our latest valuation report, VM's share price might be too pessimistic.
Shenzhen Edge Medical (SEHK:2675)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shenzhen Edge Medical Co., Ltd. designs, develops, manufactures, and sells surgical robots in Europe and China, with a market cap of HK$14.64 billion.
Operations: The company's revenue is primarily derived from its surgical robot systems, instruments and accessories, and provision of services, totaling CN¥625.65 million.
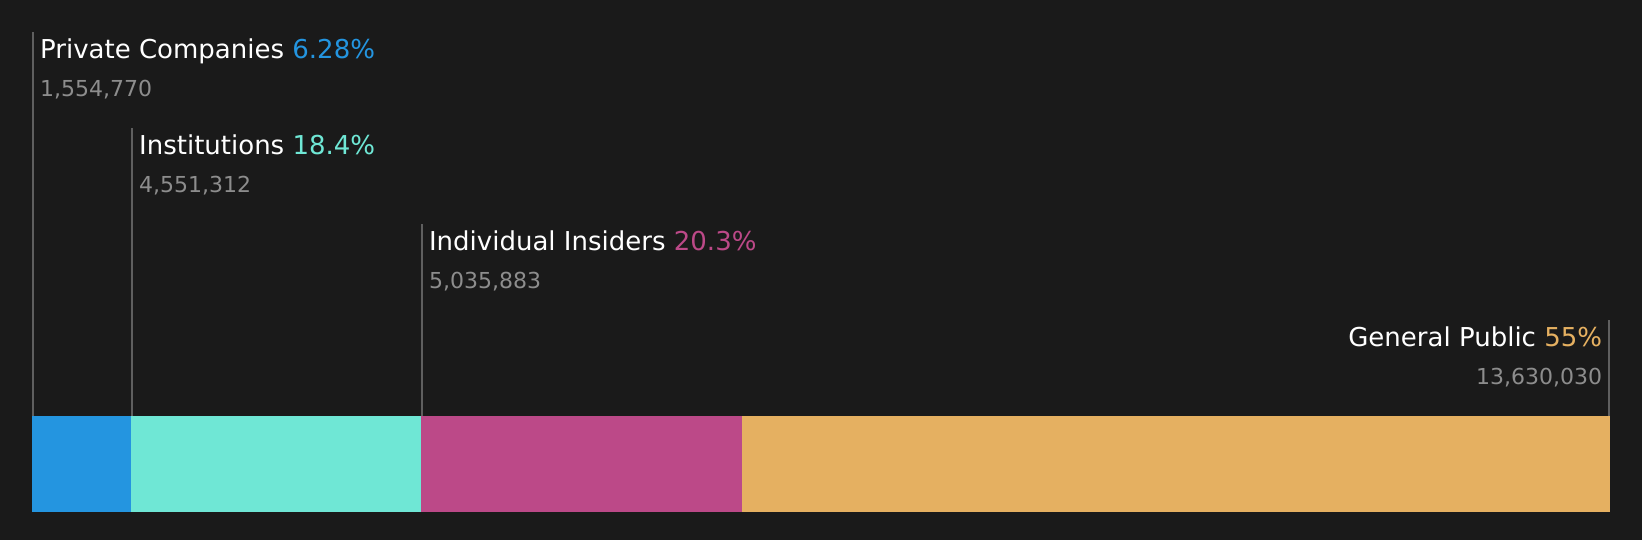
Insider Ownership: 39.9%
Revenue Growth Forecast: 34.4% p.a.
Shenzhen Edge Medical demonstrates strong growth potential, with revenue expanding by 124.1% over the past year and forecasted to grow at 34.4% annually, outpacing the Hong Kong market's average. Despite a current net loss of CNY 19.25 million for H1 2026, this is an improvement from the previous year's loss, indicating progress towards profitability within three years. The company recently initiated a share buyback program to enhance shareholder value and earnings per share.
- Dive into the specifics of Shenzhen Edge Medical here with our thorough growth forecast report.
- Our valuation report here indicates Shenzhen Edge Medical may be overvalued.

Smartsens Technology (Shanghai) (SHSE:688213)
Simply Wall St Growth Rating: ★★★★★★
Overview: Smartsens Technology (Shanghai) Co., Ltd. operates in the semiconductor industry, focusing on the design and development of image sensors, with a market cap of approximately CN¥37.53 billion.
Operations: The company's revenue is primarily generated from its Semiconductor Integrated Circuit Chips segment, which accounts for CN¥9.84 billion.
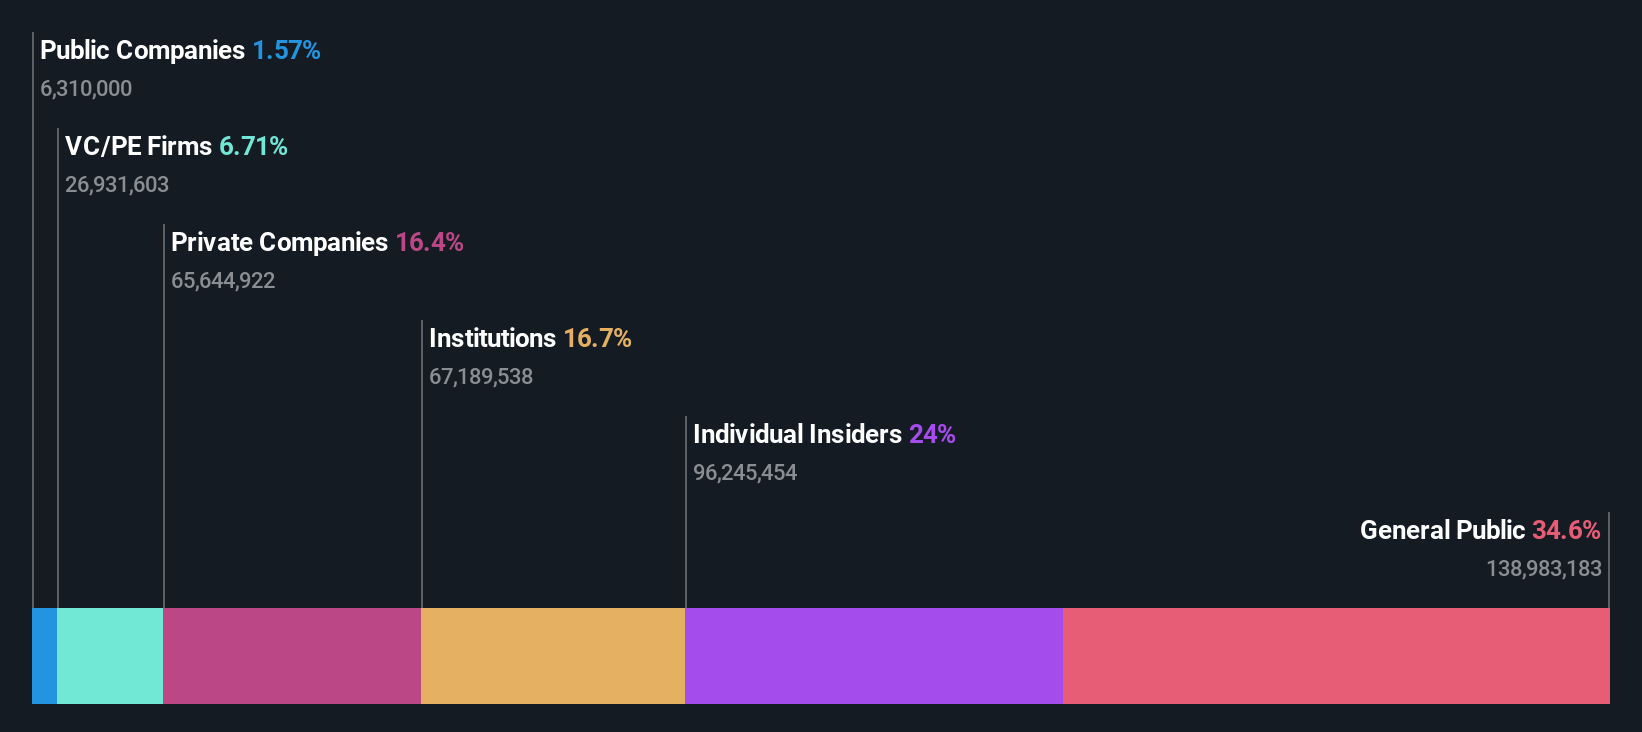
Insider Ownership: 23.3%
Revenue Growth Forecast: 21.5% p.a.
Smartsens Technology (Shanghai) shows promising growth prospects, with earnings and revenue forecasted to grow faster than the Chinese market at 28.6% and 21.5% annually, respectively. The company reported substantial financial progress for H1 2026, with net income rising to CNY 528.43 million from CNY 396.86 million a year ago. Trading significantly below its estimated fair value and offering good relative value compared to peers, it maintains strong insider ownership without recent significant insider trading activity.
- Unlock comprehensive insights into our analysis of Smartsens Technology (Shanghai) stock in this growth report.
- In light of our recent valuation report, it seems possible that Smartsens Technology (Shanghai) is trading behind its estimated value.
Taking Advantage
- Click here to access our complete index of 719 Fast Growing Global Companies With High Insider Ownership.
- Contemplating Other Strategies? Trump's oil boom is here — pipelines are primed to profit. Discover the 80 US stocks riding the wave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com