
Guardant Health (GH) Rides Liquid Biopsy Growth Narrative With Valuation Still In Focus
Guardant Health (GH) draws investor attention after a strong year-to-date share price gain, with the stock up 73.4%. The move comes alongside reported annual revenue of US$1.18b and a net loss of US$453.44m.
Guardant Health’s recent run has been powerful, with a 73.43% year-to-date share price return and a 193.94% 1-year total shareholder return, while the 495.31% 3-year total shareholder return signals strong momentum that has persisted beyond the latest quarterly swing.
Scan the kind of momentum story Guardant Health is having compared with a hand-picked 38 healthcare AI stocks group that is also tying advanced diagnostics to rapid share price moves.
Guardant Health now trades about 11% below the average analyst price target and roughly 18% under one intrinsic value estimate after a sharp rally. Is that a genuine discount, or is it a reflection of caution about ongoing losses?
Most Popular Narrative: 9% Undervalued
Guardant Health's most followed valuation view points to a fair value of about $194 per share, compared with the recent $176.45 close. This puts the current rally in the context of a still perceived discount built on aggressive growth and margin assumptions.
Accelerating adoption of non-invasive blood-based cancer diagnostics is driving substantial growth across Guardant Health's key product lines (Guardant360 Liquid, Reveal, and Shield). This is expanding the company's total addressable market and supporting high double-digit revenue growth, with continued strong volume momentum and share gains documented for both new and established oncology applications.
See why 22 investors see Guardant Health as 9% undervalued.
Result: Fair Value of $194.29 (UNDERVALUED)
Still, Guardant Health’s story carries real pressure points, including ongoing heavy cash burn and the patent judgment, with potential royalties that could weigh on future economics.
Find out about the key risks to this Guardant Health narrative.
Guardant Health: A Very Different Read On Value
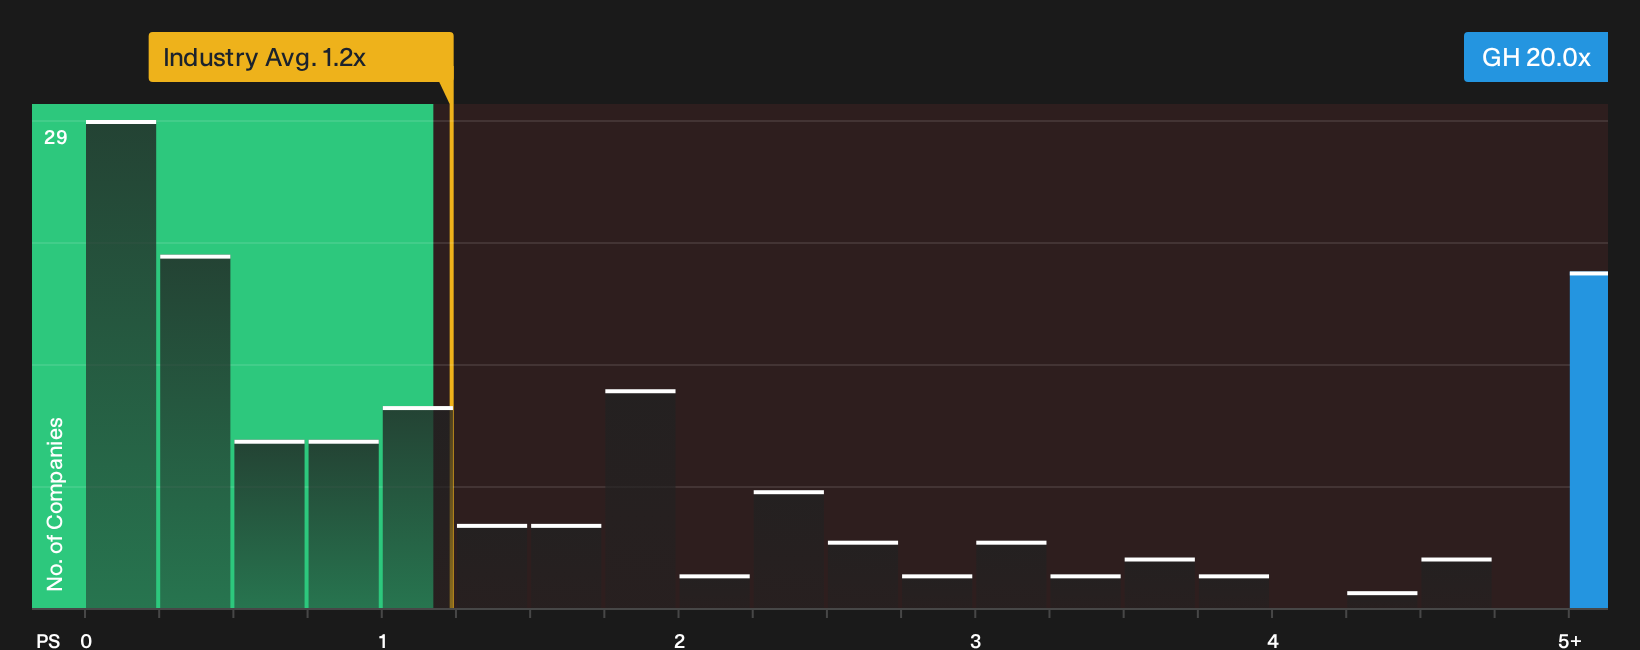
There is a sharp contrast between the analyst narrative that sees Guardant Health as roughly 9% undervalued and what the current sales multiple implies. The stock trades on a P/S ratio of 20x, while the wider US Healthcare group sits around 1.2x and peers average 1.4x.
The fair ratio is estimated at 10.5x, roughly half the current level. That gap suggests investors are already paying a heavy premium for forecast growth and future profitability, so the key question is whether you believe those projections justify holding such a rich multiple over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Guardant Health after this run and valuation debate. Act quickly, review both the upside and the pressure points, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Guardant Health?
Guardant Health might already be on your radar, but some investors look for an edge by lining up a few strong alternatives before making their next move.
- Target potential mispricing across the market by scanning a 30 high quality undervalued stocks that couples solid fundamentals with what some investors view as attractive entry points.
- Prioritize resilience by reviewing a 30 resilient stocks with low risk scores that filters for companies with steadier scorecards and fewer red flags on key risk checks.
- Identify under-the-radar opportunities by checking a 16 high quality undiscovered gems that highlights financially sound businesses that some investors consider less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com