
UK's Top Value Stocks Estimated Below Intrinsic Worth September 2026
As the United Kingdom's FTSE 100 index faces challenges amid weak trade data from China, investors are increasingly cautious about global economic conditions. In this environment, identifying undervalued stocks becomes crucial as they may offer potential resilience and opportunities for growth despite broader market uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows In The United Kingdom
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Polar Capital Holdings (AIM:POLR) | £8.37 | £14.45 | 42.1% |
| PayPoint (LSE:PAY) | £6.31 | £10.71 | 41.1% |
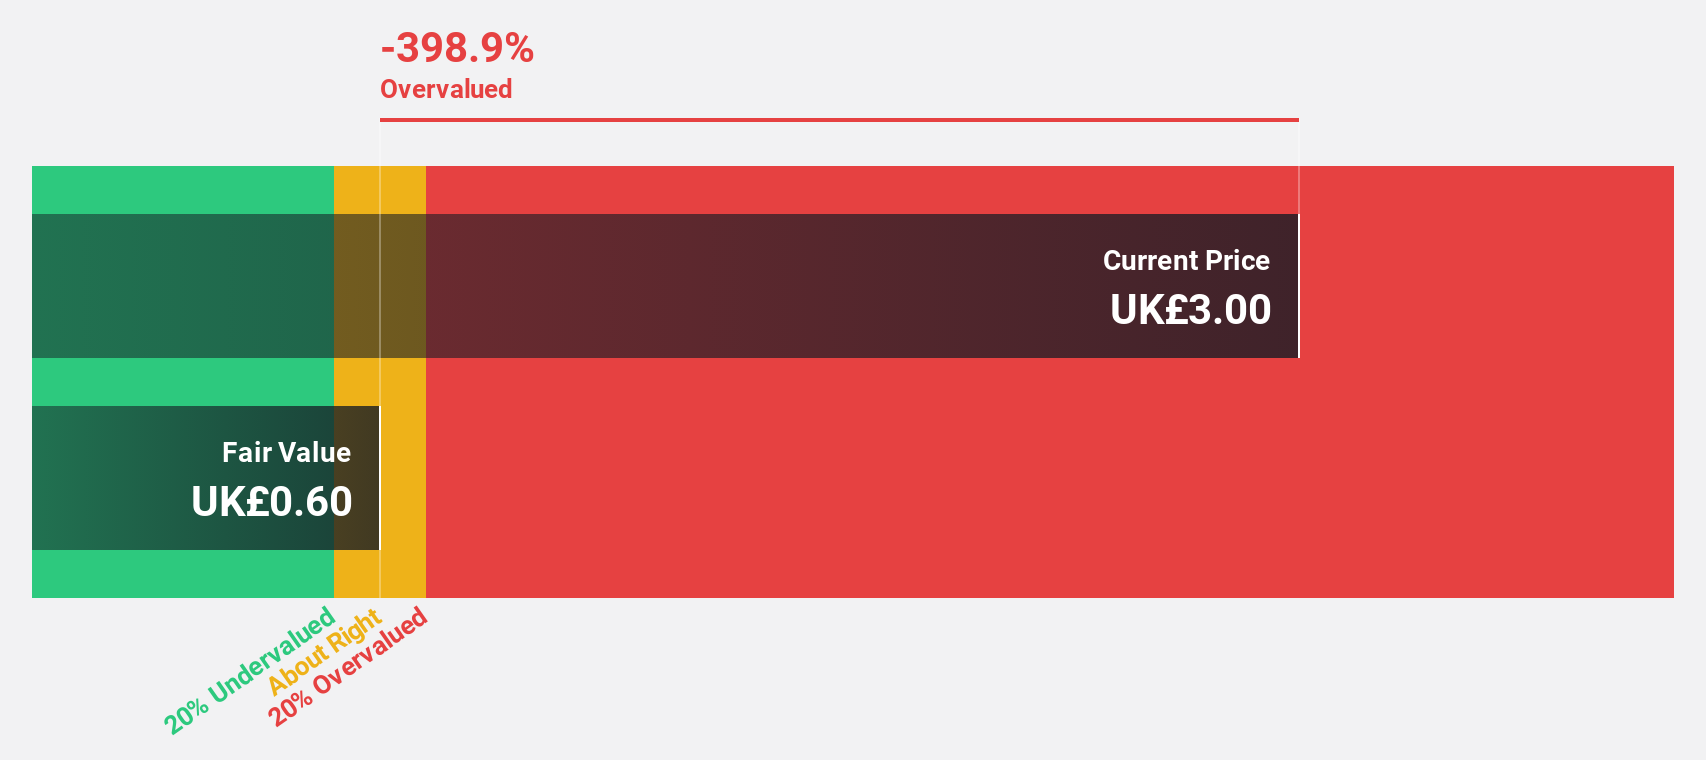
| LSL Property Services (LSE:LSL) | £2.56 | £4.62 | 44.6% |
| Kooth (AIM:KOO) | £1.685 | £2.36 | 28.7% |
| Keystone Law Group (AIM:KEYS) | £6.85 | £9.22 | 25.7% |
| Genus (LSE:GNS) | £20.74 | £35.18 | 41% |
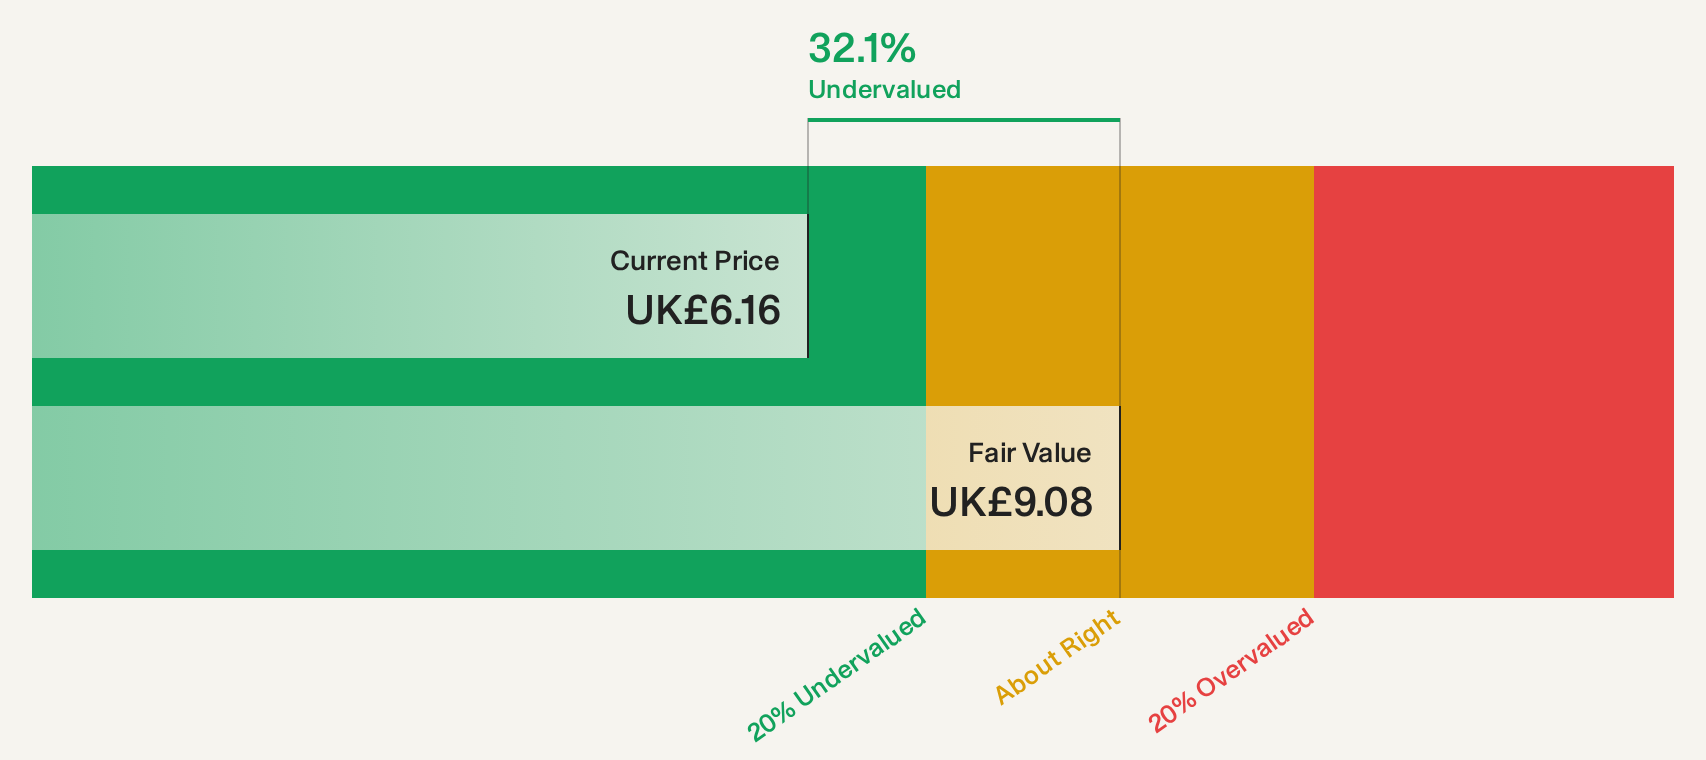
| Frontier Developments (AIM:FDEV) | £6.27 | £9.09 | 31% |
| Foresight Group Holdings (LSE:FSG) | £4.26 | £6.84 | 37.7% |
| AltynGold (LSE:ALTN) | £10.20 | £19.01 | 46.3% |
| accesso Technology Group (AIM:ACSO) | £3.04 | £4.44 | 31.5% |
Let's take a closer look at a couple of our picks from the screened companies.
Frontier Developments (AIM:FDEV)
Overview: Frontier Developments plc develops and publishes video games for the interactive entertainment sector, with a market cap of £211.39 million.
Operations: The company generates revenue from its Computer Graphics segment, amounting to £104.80 million.
Estimated Discount To Fair Value: 31%
Frontier Developments reported strong earnings growth with net income rising to £27.28 million from £16.39 million, yet it faces a forecasted decline in revenue and profits over the next three years. Despite this, the stock trades 31% below its estimated fair value and is undervalued based on discounted cash flow analysis, trading at £6.27 against a future cash flow value of £9.09. Recent strategic alliances with Disney could bolster its creative management simulation portfolio.
- Our earnings growth report unveils the potential for significant increases in Frontier Developments' future results.
- Get an in-depth perspective on Frontier Developments' balance sheet by reading our health report here.
Cairn Homes (LSE:CRN)
Overview: Cairn Homes plc, along with its subsidiaries, operates as a homebuilder in Ireland and has a market capitalization of approximately £1.41 billion.
Operations: The company generates revenue primarily from its Building and Property Development segment, which amounted to €1.12 billion.
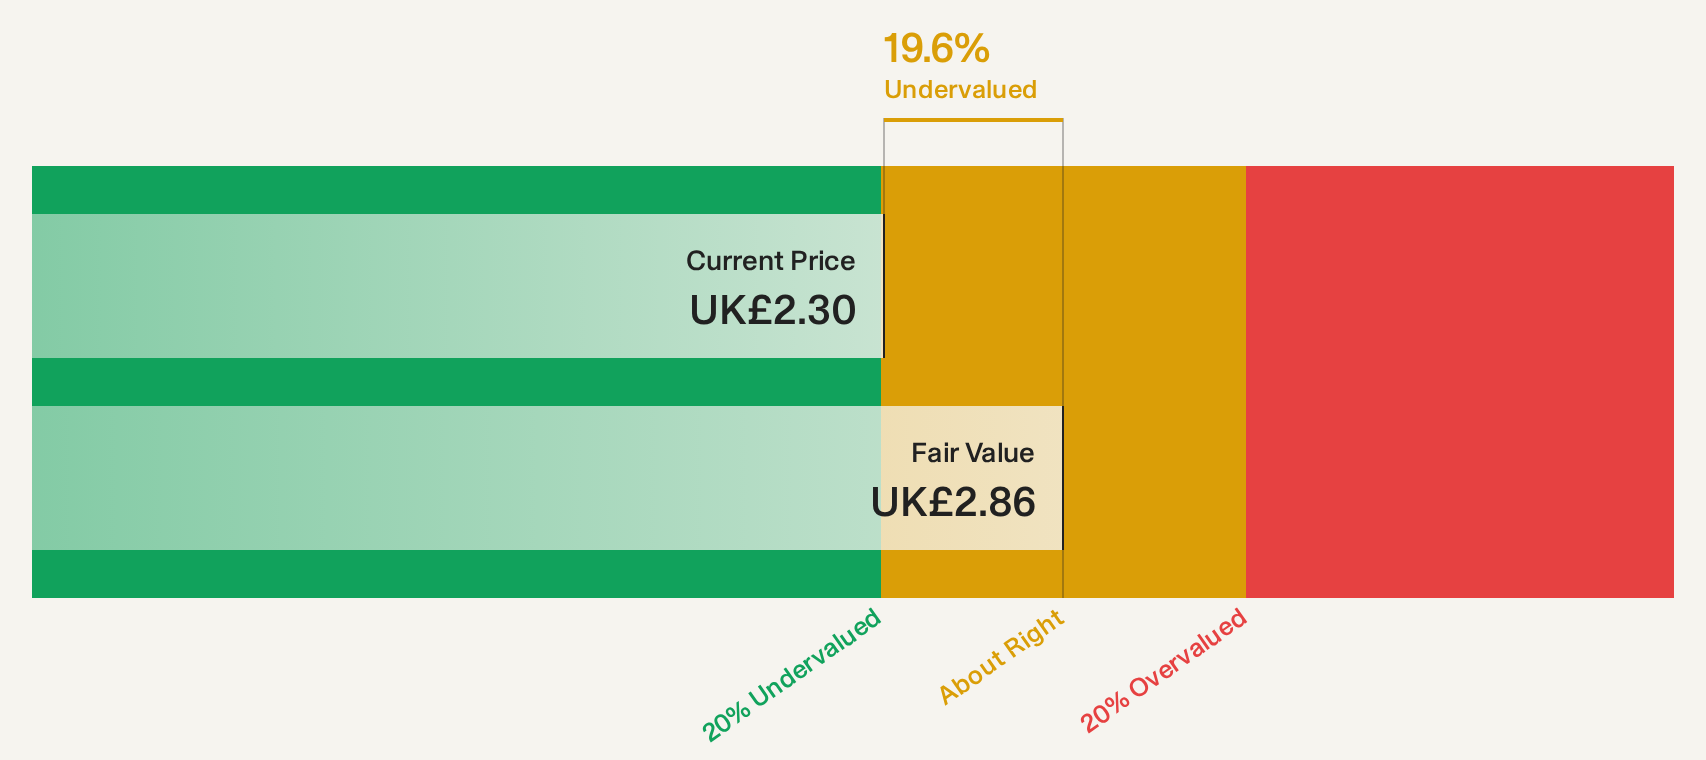
Estimated Discount To Fair Value: 20.2%
Cairn Homes exhibits strong cash flow potential, trading 20.2% below its estimated fair value and significantly undervalued based on discounted cash flow analysis. Recent earnings growth of 60.4% highlights robust financial health, supported by a €50 million share buyback program aimed at reducing share capital. While revenue is forecast to grow at 6% annually, slower than the broader UK market's profit growth expectations, strategic moves like upgraded earnings guidance bolster investor confidence.
- The analysis detailed in our Cairn Homes growth report hints at robust future financial performance.
- Click here and access our complete balance sheet health report to understand the dynamics of Cairn Homes.
LSL Property Services (LSE:LSL)
Overview: LSL Property Services plc, with a market cap of £251.71 million, operates as a business-to-business platform offering residential market services in the United Kingdom.
Operations: The company's revenue is primarily derived from three segments: Financial Services (£48.19 million), Surveying and Valuation (£110.70 million), and Estate Agency excluding Financial Services (£26.70 million).
Estimated Discount To Fair Value: 44.6%
LSL Property Services is trading 44.6% below its estimated fair value, with a current price of £2.56 against a future cash flow estimate of £4.62, highlighting its undervaluation based on discounted cash flow analysis. Despite earnings growth forecasted at 11% annually, slower than the UK market average, recent half-year results show steady performance with net income rising to £8.61 million from £8.19 million last year and an interim dividend maintained at 4 pence per share.
- Our comprehensive growth report raises the possibility that LSL Property Services is poised for substantial financial growth.
- Click here to discover the nuances of LSL Property Services with our detailed financial health report.
Taking Advantage
- Reveal the 13 hidden gems among our Undervalued UK Stocks Based On Cash Flows screener with a single click here.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com