
Is Toyota Motor (TSE:7203) Fully Valued On Its Humanoid Robot Plans?
Robot deployment plans at Toyota Motor (TSE:7203) are in focus after reports that the manufacturer aims to roll out around 400,000 humanoid units, including its ELEY model, across global plants.
For investors watching the tape, Toyota Motor’s share price has eased in the short term, with a 1-month share price return down 3.7% and year to date down 12.7%. However, the 90-day share price return is up 7.3% and the 5-year total shareholder return sits at 69.0%, which points to longer term holders still seeing meaningful value creation as the market reassesses growth potential and execution risks around projects such as large scale humanoid robot deployment.
Scan how other automation heavy plays are shaping up beside Toyota Motor by reviewing the hand picked 93 robotics and automation stocks that could also be re-rating on factory robotics demand.
Toyota Motor’s robot push and recent share pullback create a straightforward question: Is most of the repricing already in the rearview mirror, or does the current tag still leave meaningful upside on the table, as the valuation section explains next?
Most Popular Narrative: 39% Overvalued
Toyota Motor last closed at ¥2,969, while the most followed narrative fair value sits at ¥2,137, which frames the current humanoid robot story against a valuation that already prices in plenty of optimism.
The primary factor in recognizing Toyota as a "company of the future" is its technological breakthrough in solid-state batteries. While competitors struggled to lower the price of current lithium-ion solutions, Toyota introduced a working solid-state battery prototype boasting a range of up to 1,200 km and a charging time of just 10 minutes. This effectively removes the final barriers to mass electric vehicle adoption.
See why 6 investors see Toyota Motor as 39% overvalued.
Result: Fair Value of ¥2,137 (OVERVALUED)
Still, Toyota Motor faces real pressure if solid state battery timelines slip or robot deployment costs overrun. This could quickly cool enthusiasm around this premium narrative.
Find out about the key risks to this Toyota Motor narrative.
Another View On Toyota Motor’s Valuation
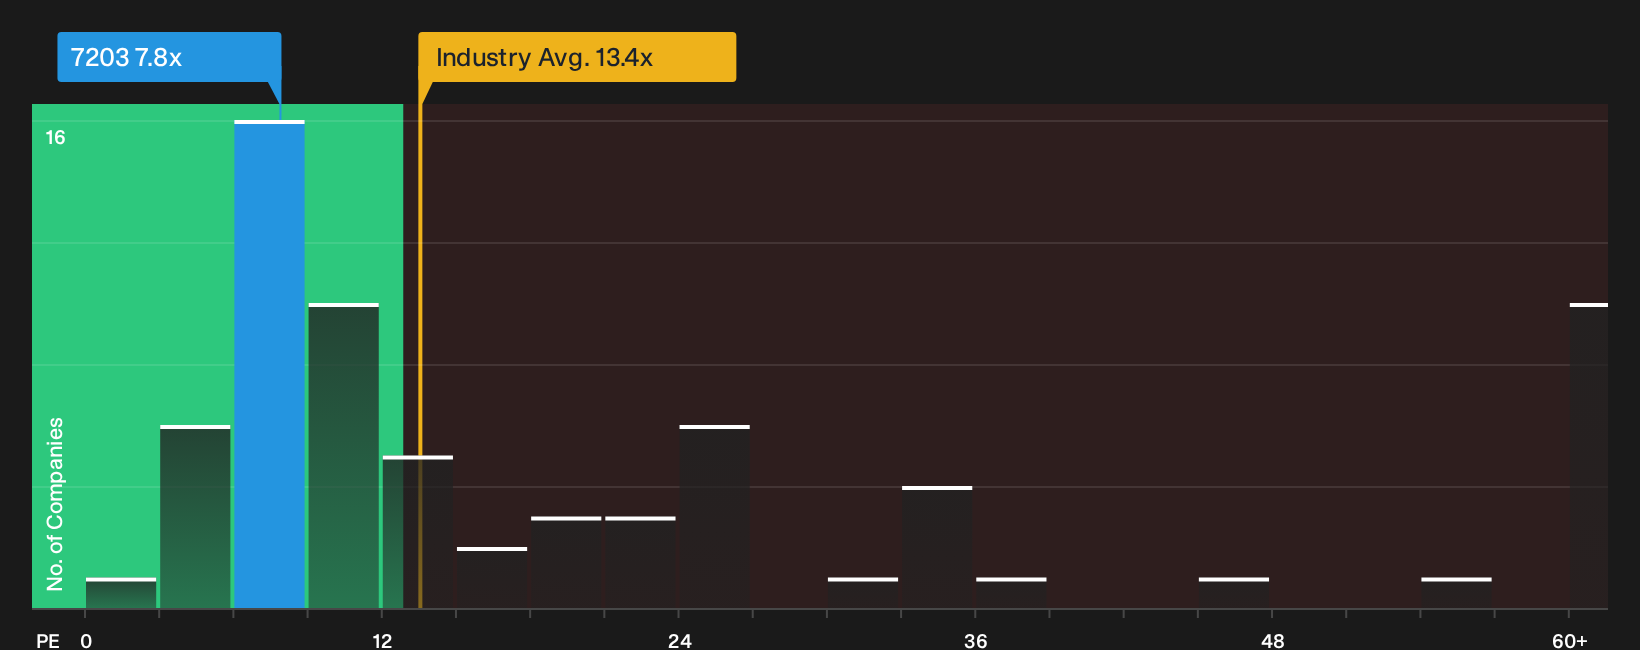
The narrative fair value pegs Toyota Motor at ¥2,137 and calls the stock overvalued, yet the current P/E of 7.8x tells a different story. That multiple sits well below the JP market at 14.1x, the Asian auto group at 13.3x, peers at 11.6x, and even the fair ratio of 16x. For investors, that gap raises a practical question: Is the risk that expectations remain too rich, or that the market eventually moves closer to that higher fair ratio and rerates the shares?
To see how that P/E gap could close or stay wide open, and what the numbers imply for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Toyota Motor is clearly split, so move fast and stress test the story yourself by weighing both the bright spots and the pressure points using the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Toyota Motor?
If the split view on Toyota Motor has you thinking harder about where to put fresh capital, widen the lens and scan other opportunities that match your style.
- Target resilience first by filtering for companies with strong finances and robust balance sheets using the list of solid balance sheet and fundamentals (21 results).
- Hunt for potential mispricing by zeroing in on quality companies that look discounted through the 17 high quality undervalued stocks.
- Build a watchlist of smaller under the radar opportunities before the crowd arrives by reviewing the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com