
Is Kirby (KEX) Undervalued On Its Pullback Or Already Priced For Growth?
Kirby (KEX) has drawn fresh attention after recent price moves left the stock down over the past week, month, and past 3 months, even as its 1 year total return remains positive.
Short term momentum for Kirby has cooled, with the share price down over the past month and past quarter. However, the year to date share price return of 16.45%, alongside a 1 year total shareholder return of 54.91%, signals that longer term holders have still seen strong gains.
Compare Kirby's recent pullback with other transportation and industrial operators by scanning our hand picked list of solid balance sheet and fundamentals (24 results) that may handle volatility more consistently.
Kirby now trades at a sizable discount to both analyst targets and estimated fair value after this pullback. Is the market identifying real risk, or simply marking down a still solid operator out of caution alone?
Most Popular Narrative: 22% Undervalued
On the most followed view of Kirby, the fair value estimate of $166.17 sits well above the recent $130.31 close. This places the latest pullback squarely against an undervaluation story built on tight barge supply and power demand.
Supply constraints and industry wide aging of the barge fleet are restraining new capacity growth, with industry inland barge construction around 60 to 70 units per year and newbuild returns still about 40% away from justified economics. This supports limited vessel availability, firmer pricing and the potential for higher Marine Transportation revenue and net margins.
See why 13 investors see Kirby as 22% undervalued.
Result: Fair Value of $166.17 (UNDERVALUED)
Still, the Kirby narrative can crack if oil and gas focused Distribution and Services weakness persists or if medical cost inflation keeps squeezing margins despite firm demand.
Find out about the key risks to this Kirby narrative.
Another View: Kirby Looks Expensive On Earnings
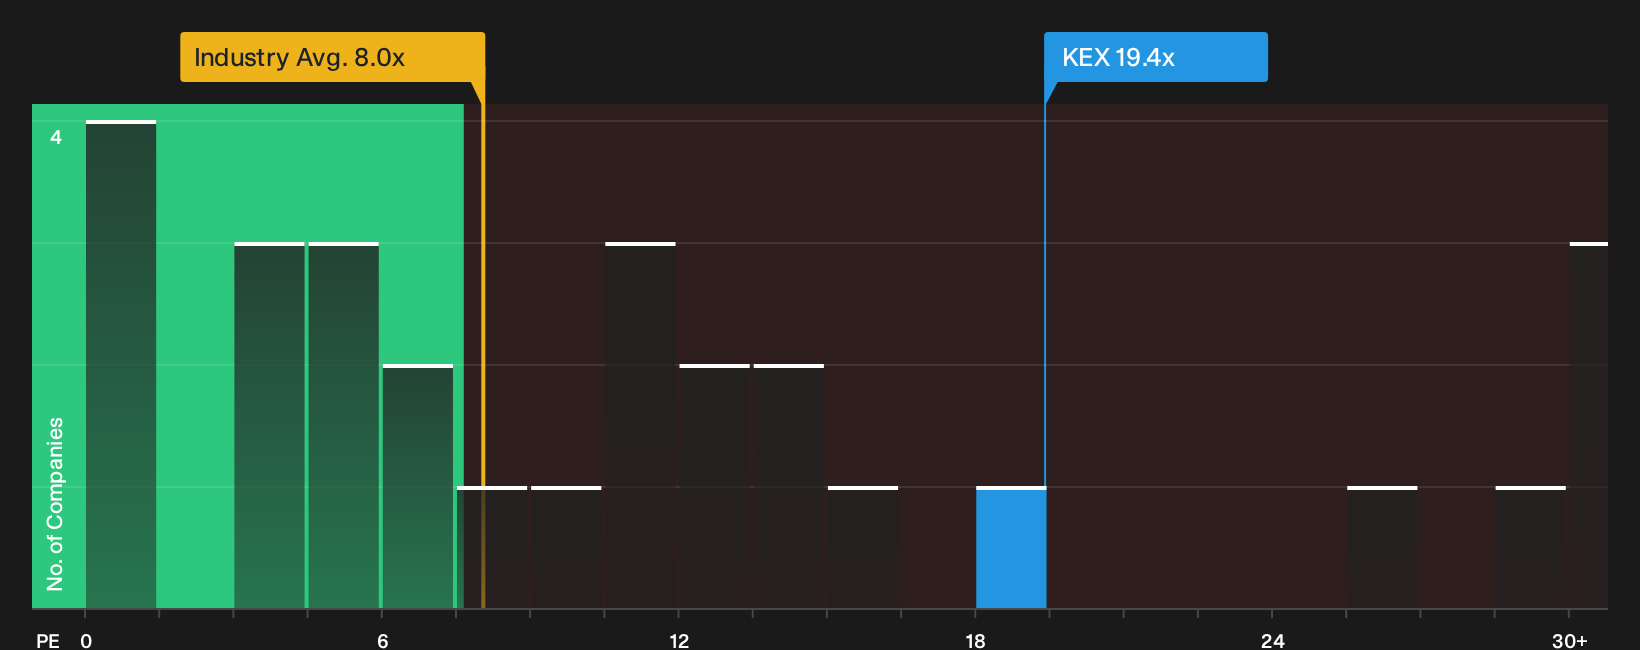
On a simple earnings yardstick, Kirby screens very differently. The stock trades on a P/E of 19.4x, which is higher than the peer average of 14.3x and also above an estimated fair ratio of 18.3x. That richer multiple raises a fair question about how much good news is already priced in for investors.
For a closer look at how this earnings based view stacks up against the rest of the sector and the fair ratio that the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
This mix of optimism and concern around Kirby only matters if it helps you size the opportunity for yourself and act with intent. To see what investors are currently excited about, review the 4 key rewards
Looking for more investment ideas beyond Kirby?
If Kirby has you thinking harder about risk, reward, and timing, use that focus to widen your hunt with a few targeted stock shortlists.
- Chase mispriced opportunities by scanning a curated set of quality companies trading at appealing valuations through the 30 high quality undervalued stocks.
- Strengthen your income stream by reviewing potential high yield payers that feature in the 7 dividend fortresses.
- Dial down portfolio stress by filtering for sturdier businesses with resilient finances using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com