
Asian Market Insights: Envision Greenwise Holdings And 2 Other Promising Penny Stocks
Amidst a backdrop of fluctuating oil prices and evolving monetary policies in Asia, investors are keenly observing the potential opportunities within the region's stock markets. Penny stocks, often seen as relics of past market eras, continue to capture attention due to their affordability and growth potential. These smaller or newer companies can offer significant value when backed by strong financial health, making them an intriguing area for those seeking long-term investment opportunities.
Here's a peek at a few of the choices from the screener.
Envision Greenwise Holdings (SEHK:1783)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Envision Greenwise Holdings Limited is an investment holding company engaged in the construction business in Hong Kong and the People's Republic of China, with a market cap of HK$13.38 billion.
Operations: The company's revenue is derived from two main segments: Superstructure Building and RMAA Works Service, contributing HK$145.88 million, and Reverse Supply Chain Management and Environmental Related Service, generating HK$2.42 billion.
Market Cap: HK$13.38B
Envision Greenwise Holdings has shown significant growth, with annual sales reaching HK$2.46 billion from its construction and environmental services segments, marking a notable turnaround from the previous year’s net loss to a net income of HK$60.94 million. Despite having more cash than debt and covering short-term liabilities effectively, the company faces challenges with high share price volatility and negative operating cash flow. Recent strategic developments include forming a strategy committee to guide long-term growth and completing a follow-on equity offering worth HK$549.53 million, indicating proactive steps towards strengthening its financial position.
- Get an in-depth perspective on Envision Greenwise Holdings' performance by reading our balance sheet health report here.
- Learn about Envision Greenwise Holdings' historical performance here.
Antengene (SEHK:6996)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Antengene Corporation Limited is a clinical-stage APAC biopharmaceutical company focused on developing novel oncology therapies in Greater China and internationally, with a market cap of HK$2.36 billion.
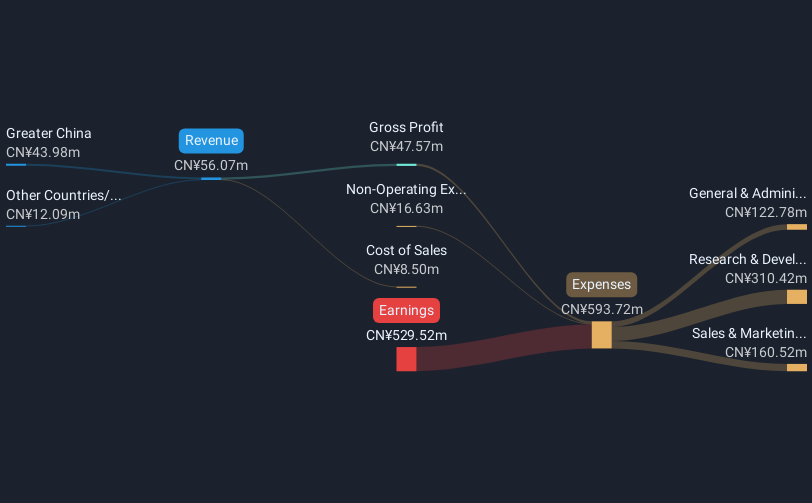
Operations: The company generates revenue of CN¥565.23 million from the research, development, and commercialization of pharmaceutical products.
Market Cap: HK$2.36B
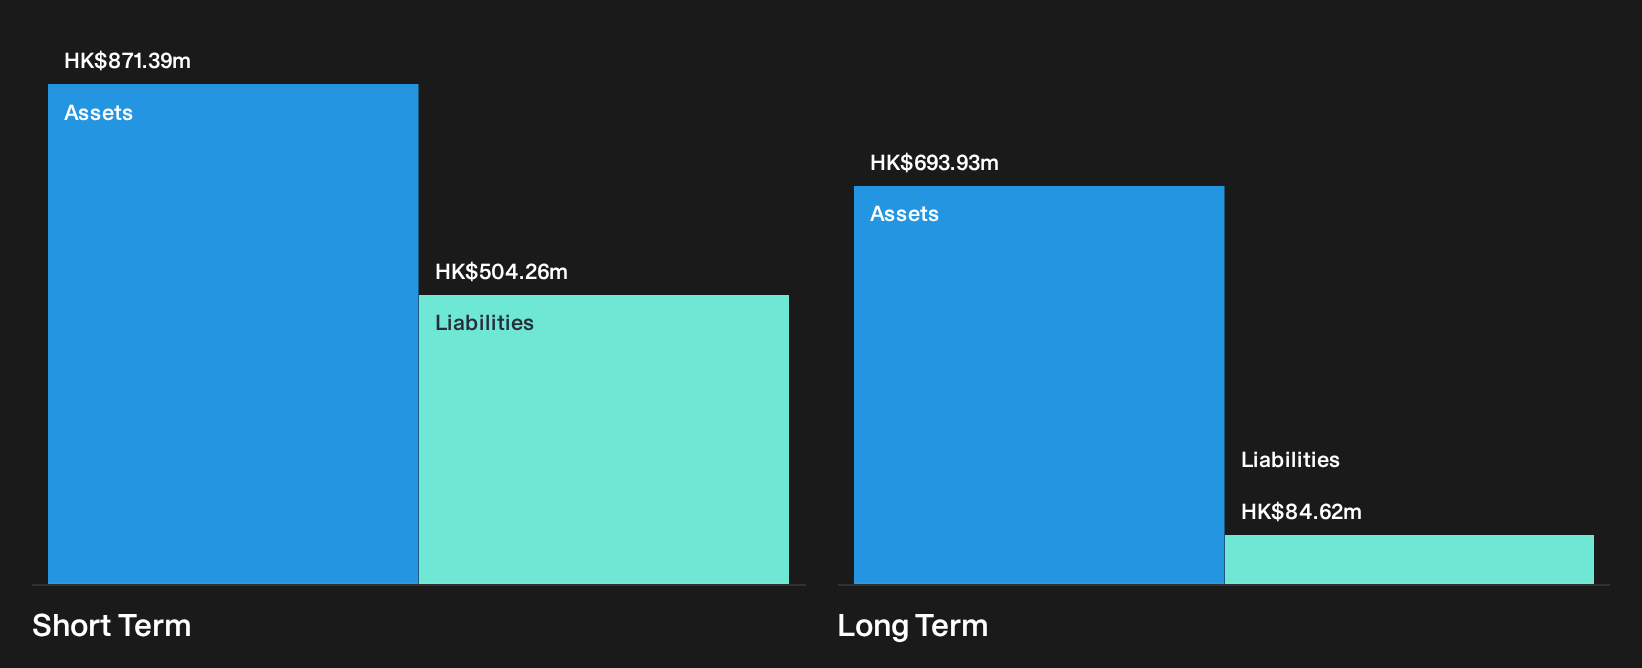
Antengene Corporation Limited has achieved profitability, reporting CN¥565.23 million in revenue and a net income of CN¥216.35 million for the first half of 2026, driven by out-licensing agreements like the one with UCB. The company maintains a strong balance sheet with more cash than debt and short-term assets exceeding liabilities. Recent advancements include dosing the first patient in China for its Phase III CLINCH-3 study of ATG-022, indicating progress in oncology drug development. Despite these positives, anticipated earnings are forecast to decline significantly over the next three years, suggesting potential challenges ahead.
- Dive into the specifics of Antengene here with our thorough balance sheet health report.
- Learn about Antengene's future growth trajectory here.
Viva Goods (SEHK:933)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Viva Goods Company Limited is involved in the design, development, branding, and sale of sports and lifestyle apparel and footwear across multiple regions including the United Kingdom, Republic of Ireland, United States, China, Asia, Europe, Middle East, and Africa with a market capitalization of approximately HK$3.73 billion.
Operations: The company generates revenue from two main segments: Sports Experience, contributing HK$599.05 million, and Multi-Brand Apparel and Footwear, which accounts for HK$10.01 billion.
Market Cap: HK$3.73B
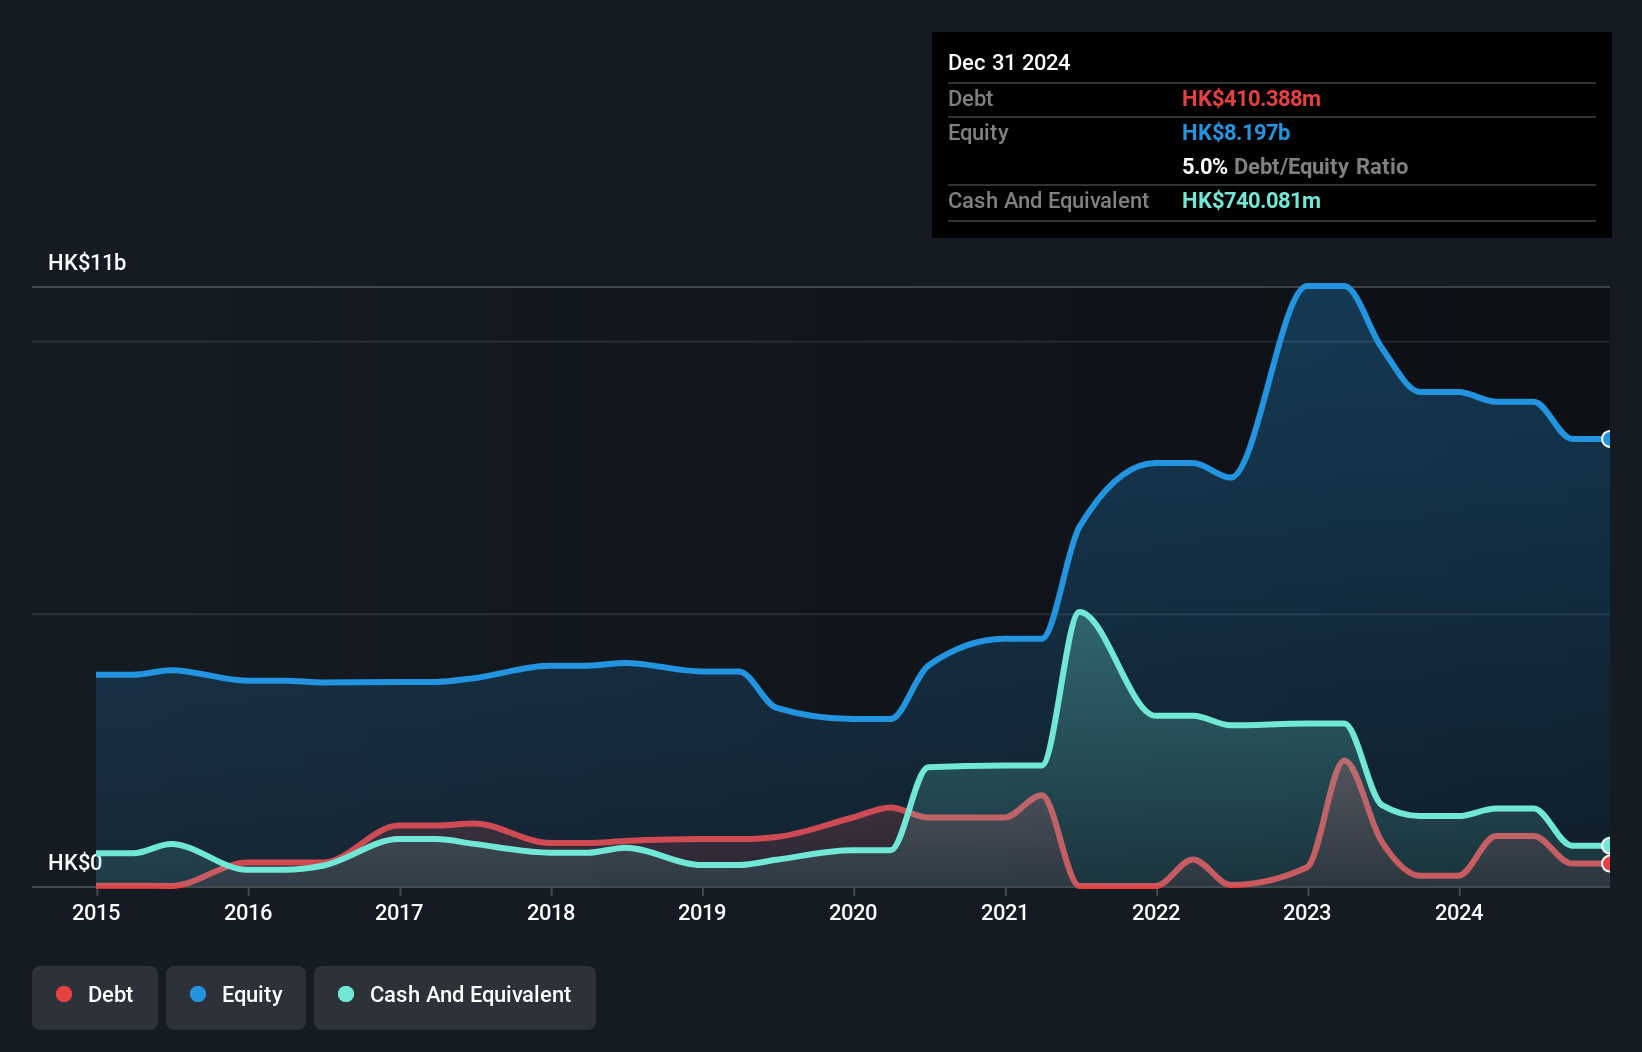
Viva Goods Company Limited reported HK$5.12 billion in sales for the first half of 2026, up from HK$4.81 billion a year earlier, with net income rising to HK$268.8 million. The company has become profitable this year, although its Return on Equity remains low at 4.3%. Debt levels are satisfactory with a net debt to equity ratio of 11.5%, and short-term assets exceed both short and long-term liabilities significantly. Despite past earnings decline, recent strategic initiatives like product realignment and operational efficiency improvements have contributed positively to profitability and margins in key markets such as the US and UK.
- Navigate through the intricacies of Viva Goods with our comprehensive balance sheet health report here.
- Evaluate Viva Goods' prospects by accessing our earnings growth report.
Summing It All Up
- Get an in-depth perspective on all 1,050 Asian Penny Stocks by using our screener here.
- Searching for a Fresh Perspective? AI is about to change healthcare. These 134 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com