
Is Supply Constraints Altering The Investment Case For Fabrinet Stock (FN)?
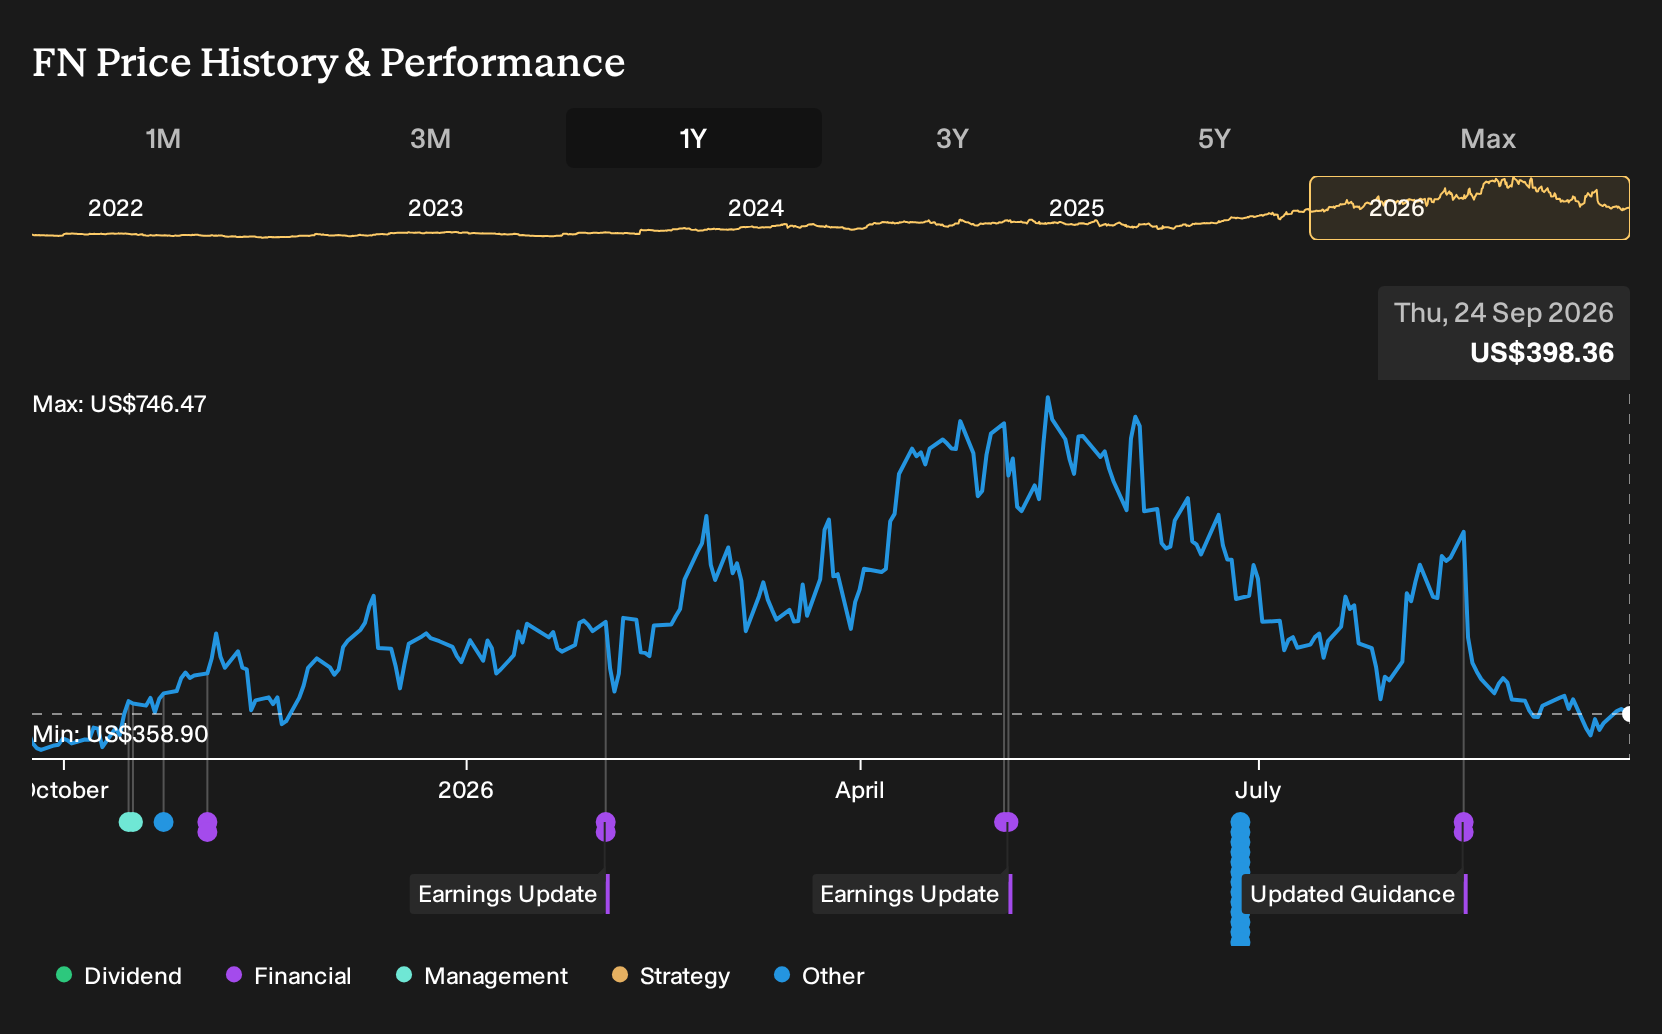
- Osterweis Opportunity Fund disclosed that Fabrinet has been an underperformer in its portfolio in the past due to commodity related supply constraints that limited shipment volumes, leading the fund to trim its position despite strong reported growth.
- The fund’s decision to reduce exposure highlights how supply bottlenecks and execution pressure on shipments can outweigh headline growth when assessing Fabrinet’s operating quality.
- We will now see how Fabrinet’s investment narrative holds up when set against fund level concerns around supply driven shipment limits.
Compare Fabrinet’s supply constrained story with other precision manufacturers that may have cleaner execution by scanning our curated list of list of solid balance sheet and fundamentals (23 results).
Fabrinet Investment Narrative Recap
To own Fabrinet, you need to be comfortable with a story built on AI related data center optics, high value photonics packaging and outsourced precision manufacturing for big customers like Cisco, NVIDIA, Nokia and Amazon. The key near term swing factor is how quickly component availability for lasers, memory and ASICs improves to let Fabrinet fully ship AI related programs.
The Osterweis update mostly reinforces what is already in the thesis. Supply bottlenecks and shipment limits are visible as the main operational drag, not demand. The biggest risk right now is that constraints persist or widen, which could keep capacity underused and introduce program level volatility with those large hyperscaler and networking clients.
There are no new company announcements directly tied to the Osterweis decision, so the most relevant context comes from Fabrinet’s existing capacity and program plans. Management is working toward expanding manufacturing capacity from about US$5.8b to roughly US$9.8b by early Q1 2027, with a longer term path toward US$12.5b to US$14b.
That build out only pays off if Fabrinet can feed it with Datacom and AI related optics projects while keeping supply chain friction manageable. The two 800G hyperscaler direct transceiver programs already in production, plus additional merchant transceiver work scheduled from late 2026 into 2027, provide clear operational milestones for you to watch as a check on execution and supply discipline.
Fabrinet’s analyst narrative points to revenue of US$9.4b and earnings of US$939.9m by 2029, based on an assumed 26.5% yearly revenue growth rate and an earnings increase of about US$466.9m from US$473.0m today.
Uncover why Fabrinet's fair value indicates an 84% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Fabrinet, the most optimistic analysts lean hard into the AWS and hyperscaler demand story, arguing supply hiccups could prove temporary against what they saw as a long runway to about US$8.6b in revenue and US$910.4m in earnings by 2029. This can be read as a more aggressive capacity utilization narrative that may shift after the Osterweis update, so it is worth comparing both sets of expectations before deciding how much risk to take.
Explore 8 other Fabrinet fair value estimates, including one that suggests potential upside of up to 113% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fabrinet research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Fabrinet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fabrinet's overall financial health at a glance.
Looking For More Ideas Beyond Fabrinet?
If this Fabrinet story has you rethinking position sizing and risk, it can help to broaden your watchlist with other businesses that fit clear financial filters. The Simply Wall St Screener gives you a fast way to compare different types of opportunities side by side so you can decide what belongs in your next round of research.
- Prefer resilient balance sheets and steadier fundamentals that can support long term compounding, even when sentiment swings, by reviewing the 31 resilient stocks with low risk scores.
- If you are hunting for compelling price tags backed by quality metrics and solid cash generation, focus your search on the 30 high quality undervalued stocks.
- For investors willing to do deeper work on smaller companies that the broader market may not be paying attention to yet, start with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com