
Dynex Capital (DX) Stock Still Looks Cheap On New Preferred Stock Sale
Dynex Capital has delivered a 49.6% gain over the past three years, yet the recent pullback and fresh preferred share financing leave a clear question for investors about how firmly its current share price rests on its earnings power. With the common stock now around US$11.34, the focus turns to what those earnings actually justify.
- A 49.6% return over three years puts Dynex Capital in the spotlight, since that kind of outcome encourages investors to test whether the earnings story still lines up with the price you see today.
- The new US$120 million Series D preferred stock, carrying a stated 9.375% rate, can reshape Dynex Capital's funding costs and capital structure, which matters for how much of its earnings ultimately belong to common shareholders.
- Your read on Dynex Capital is one view; the desks covering it have another. See what analysts think Dynex Capital's shares could be worth.
The issue now is whether Dynex Capital's current valuation is justified by the earnings that support its share price.
If you want a broader watchlist of income-focused alternatives while you assess Dynex Capital's latest preferred issue and earnings support, start with a focused screen of 7 dividend fortresses.
Is Dynex Capital Still Cheap on Earnings?
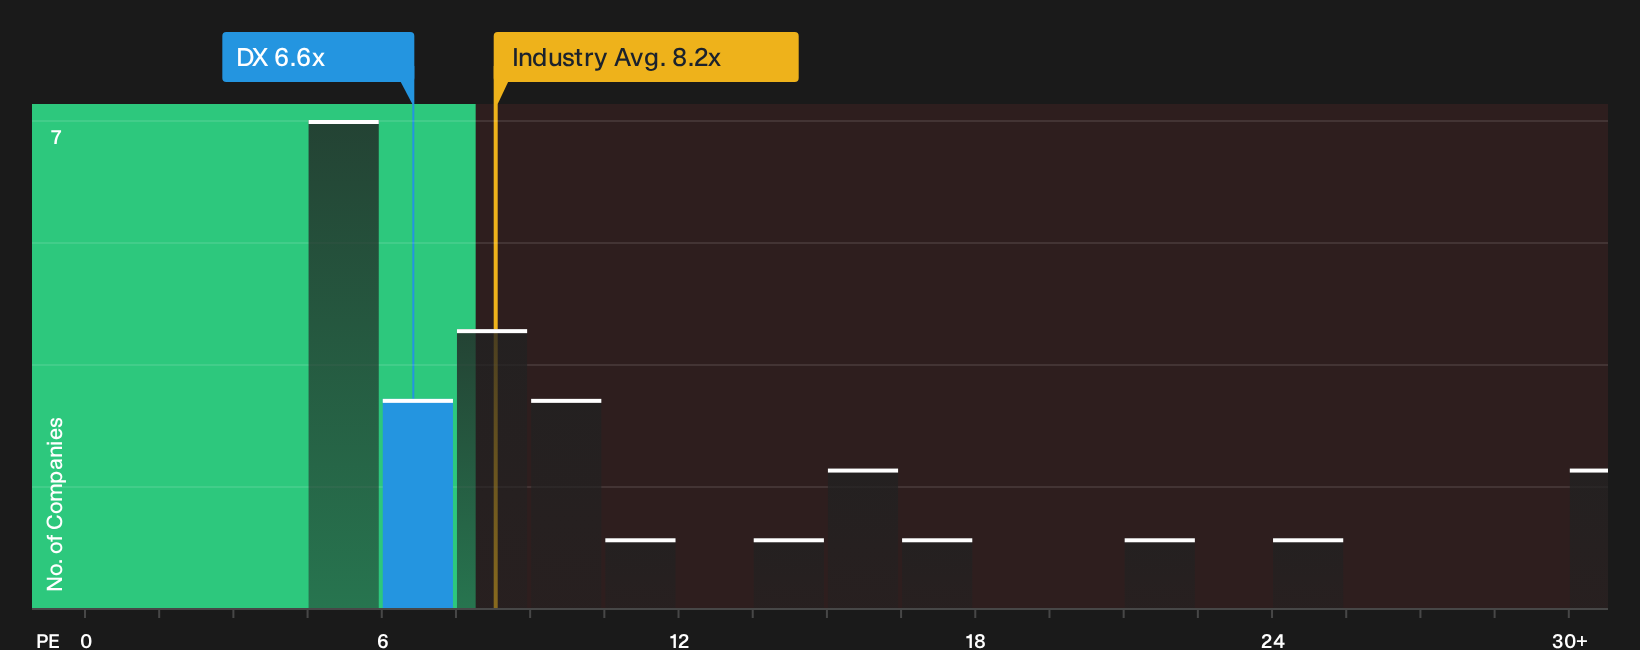
P/E is the cleanest way to frame Dynex Capital because earnings are still the main anchor for what common shareholders are paying for each dollar of profit. On this lens, Dynex Capital trades at roughly 6.6x earnings, which is slightly below both the mortgage REIT industry average of about 8.2x and the peer group at roughly 6.9x. That puts the stock at a lower earnings tag than many similar vehicles that investors use for income and rate exposure.
Because the Fair Ratio model suggests a higher P/E would typically fit Dynex Capital’s profile, the current 6.6x points to the shares screening as undervalued on this metric. The fresh 9.375% Series D preferred issuance adds a new fixed funding layer. Yet despite that extra capital cost, the common equity still trades at a discount to the earnings multiple the framework implies. For anyone weighing where the risk and payout profile really sit, this gap is the piece worth stress testing most carefully before acting on it. Explore the numbers behind Dynex Capital's P/E valuation.
The Dynex Capital Narrative: What Would Justify Today's Price?
Narratives on Dynex Capital pick up where the P/E debate leaves off and explain which paths for future earnings, funding costs and payout capacity would need to hold for today’s valuation to appear either stretched or conservative. Each scenario links a fair value estimate to a clear mix of potential catalysts and risks, allowing you to track over time which version of the story seems to be unfolding on Simply Wall St’s Community page.
A clear, written Narrative on Dynex Capital now gives you a way to lock in your view on whether the new US$120 million Series D preferred issue ultimately strengthens or dilutes the earnings claim of common shareholders. Putting those assumptions into a number-driven framework makes it easier to track how well the stock’s future results line up with the story you are betting on.
Share your own Narrative for Dynex Capital and set out the assumptions behind your valuation.
One more key question for Dynex Capital before you move on
There is still one angle worth checking before you lean on any earnings multiple for Dynex Capital. Professional coverage has already sketched out where they expect this business to be a few years from now. Explore where analysts expect Dynex Capital to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com