
Rio2 (TSX:RIO) Stock May Look Expensive As Exploration News Lifts Sentiment
Rio2 has delivered a very large 3 year share price return, which naturally raises a simple question for investors who follow mining explorers. Does the current price around earnings really stack up after that kind of move?
- The stock is up about 1,600% over 3 years, which puts a lot of weight on whether the underlying earnings story can support that kind of gain.
- Fresh exploration programs in Peru, Chile and Canada, along with index inclusion for Rio2, may support expectations for future profit potential and the timing of when earnings could matter more to valuation.
- The analysts covering Rio2 have run their own numbers. See what analysts think Rio2's shares could be worth.
The stock's next move may depend on whether Rio2's current earnings profile can justify where the share price now trades.
If you want more context around Rio2's rerating and earnings story, compare it with other gold producers using the 36 elite gold producer stocks
Is Rio2 Getting Expensive on Earnings?
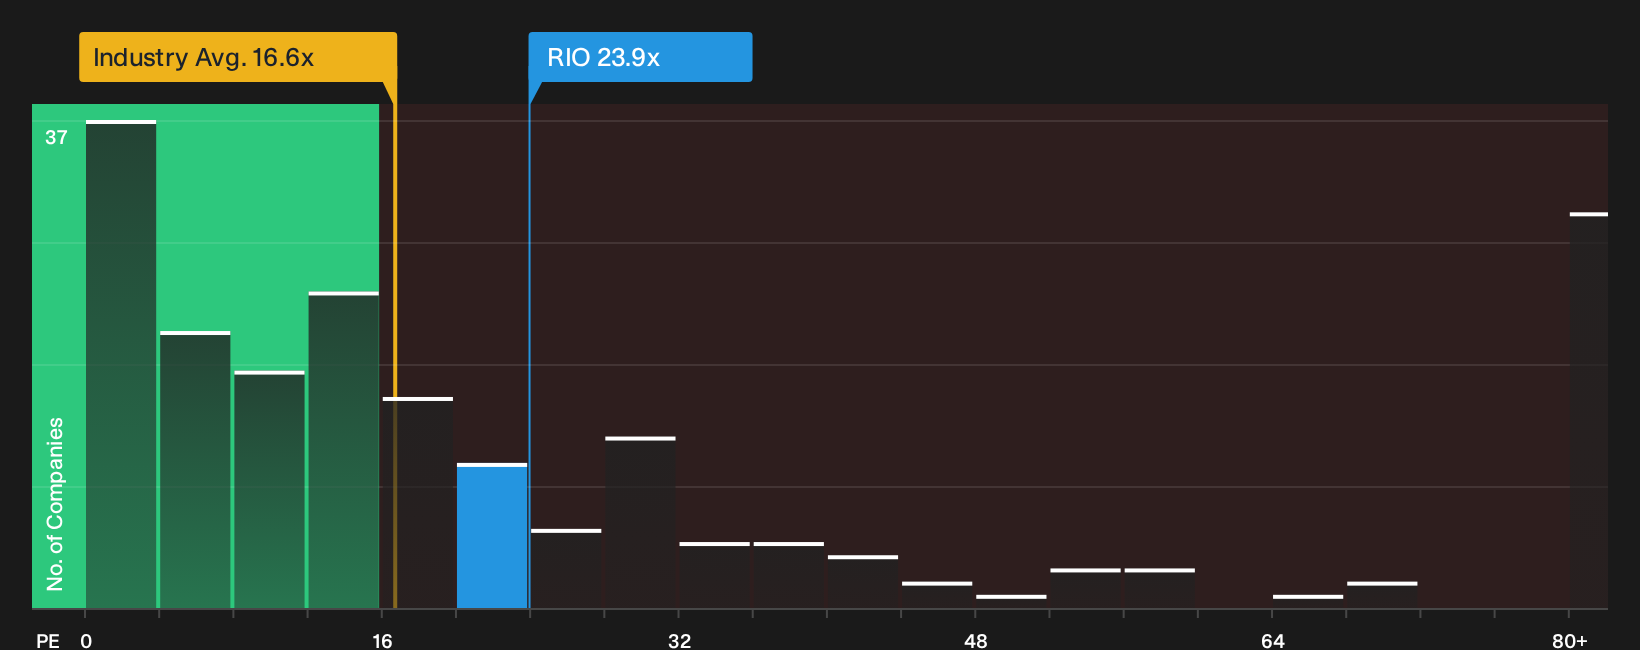
The P/E ratio suits Rio2 because earnings are the key anchor investors often use once a miner moves beyond the earliest exploration phase. On this yardstick, Rio2 trades on about 23.9x earnings, which is higher than the broader metals and mining sector average of roughly 16.6x but lower than the peer basket at about 39.9x. That leaves the shares priced above the sector as a whole, yet not at the richest end of comparable explorers and junior producers.
The Fair Ratio model, which adjusts the P/E you might expect for Rio2 based on growth assumptions, margins, size and risk, sits below the current 23.9x, so the shares screen as overvalued on this framework. Because the index inclusion and exploration update have already lifted sentiment, the present P/E implies investors are paying up for Rio2's story relative to what this tailored benchmark would usually support. Explore the numbers behind Rio2's P/E valuation.
The Rio2 Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Rio2's P/E puzzle leaves off by spelling out which combinations of future growth, profitability and risk would need to play out for the shares to look materially higher or lower than today. Each narrative links its number to a specific view on how Rio2's growth path, margin profile and project risk could evolve, giving you a set of assumptions you can track over time on the Community page as fresh information arrives.
One of the top community narratives on Rio2: 83% undervalued
"Assume 90,000 oz/year at steady state with an AISC of about US$1,237/oz and apply higher gold price scenarios for Rio2…"
Discover why this Narrative puts Rio2 at 83% undervalued.
Rio2's valuation still leaves one big piece of the puzzle unresolved
All the current ratios and market moves only tell part of the story, because professional coverage also sketches out where this business might sit a few years from now. Explore where analysts expect Rio2 to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com