
3 US Dividend Stocks Outside Mega Cap Tech Worth A Closer Look
With Apple and Nvidia now carrying far more weight in the S&P 500, index gains lean heavily on just two stocks while rising Treasury yields pull against the broader market. That concentration risk can leave more diversified dividend and quality value stocks overlooked. This article walks through three companies from a US Dividend and Quality Value Stocks Outside Mega-Cap Tech screener that appear positively exposed to this setup and may merit a closer look.
The stocks covered below are just a sample, and the full screen surfaced 8 more companies with similarly compelling income and quality stories that are not unpacked in this article. To go straight to the source, analyze and identify your own higher conviction ideas inside the US Dividend and Quality Value Stocks Outside Mega-Cap Tech screener.
PPG Industries (PPG)
Overview: PPG Industries is a global paints and coatings supplier that serves architectural, industrial, automotive, aerospace and marine customers across multiple regions.
Operations: PPG Industries generates about US$6.7b from Industrial Coatings, US$5.7b from Performance Coatings and US$4.0b from Global Architectural Coatings.
Market Cap: US$23.8b
For investors hunting for income and quality away from mega-cap tech, PPG Industries offers coatings exposure tied to industrial demand, cost discipline and balance-sheet awareness that fits the screener’s more defensive, dividend-friendly tilt.
"PPG Industries is building out its aerospace and protective and marine coatings capacity, supported by a roughly US$300 million aerospace backlog and more than US$0.5 billion of related investments."
What really matters from here is how one less visible cost and pricing pressure shapes the gap between reported margins and investor expectations.
If that pricing tension is what you care about most, the full narrative for PPG Industries sets out how PPG Industries’ margin story could be quietly decoupling from expectations.
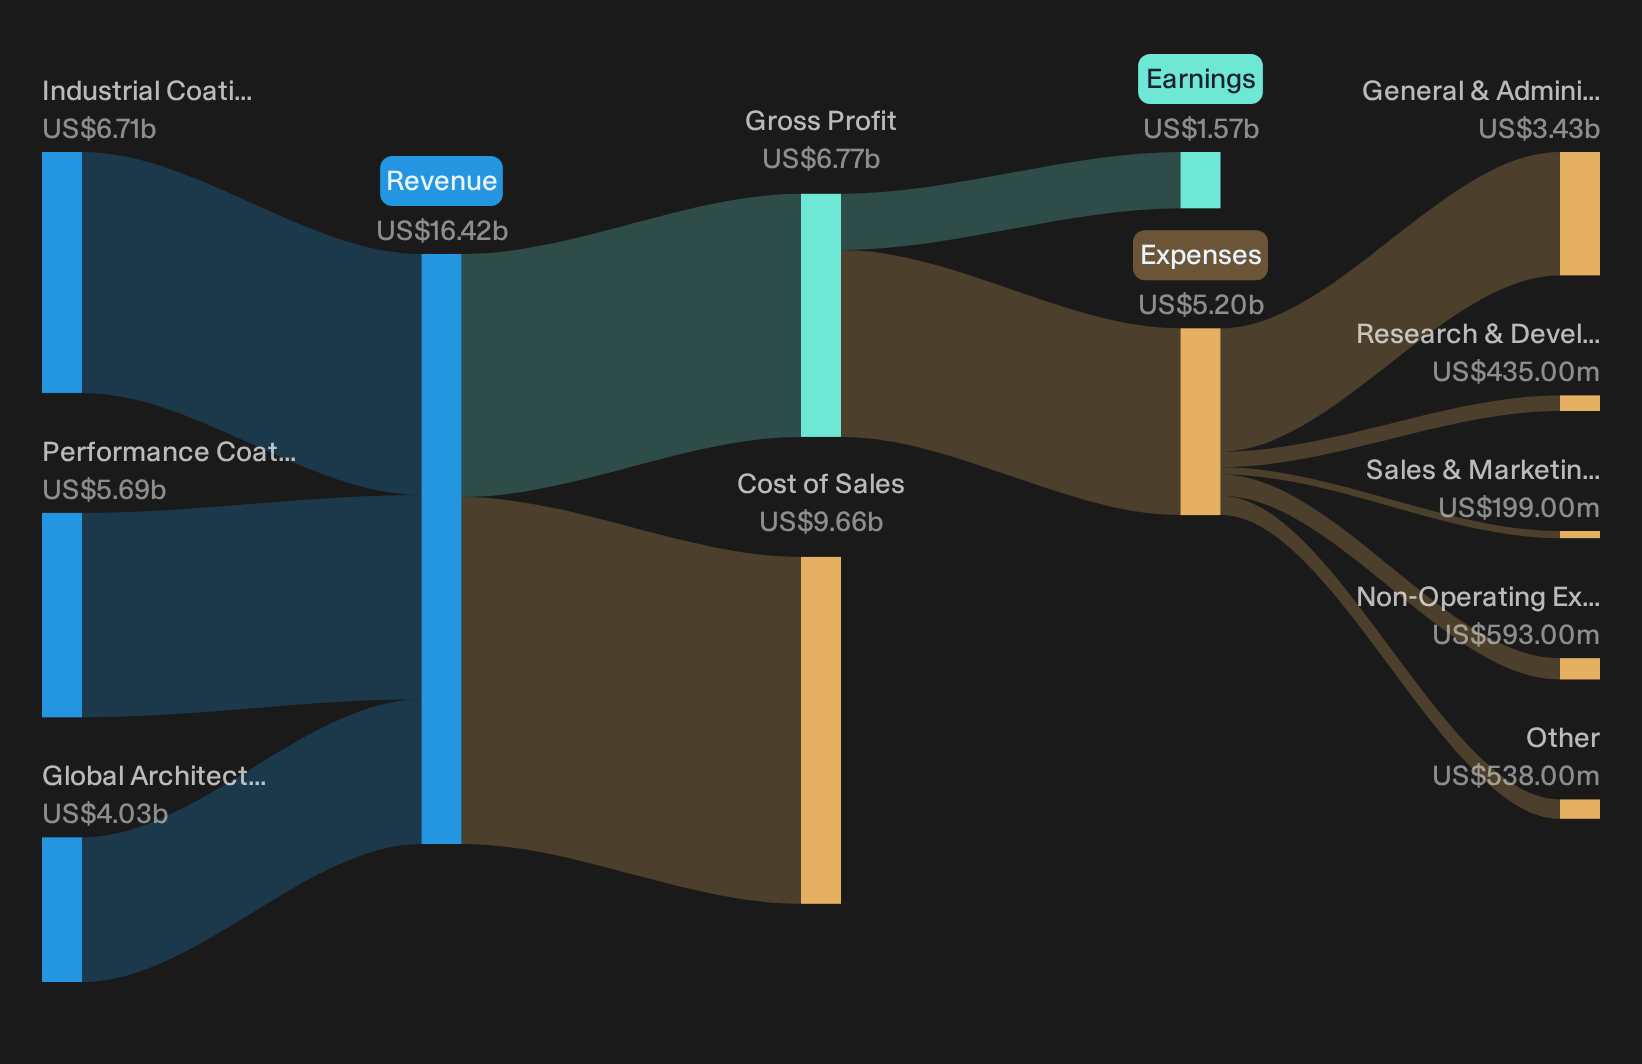
UnitedHealth Group (UNH)
Overview: UnitedHealth Group brings together health insurance, pharmacy benefits and data driven care services to provide integrated health care solutions.
Operations: UnitedHealth Group generates about US$346.5b from UnitedHealthcare, US$155.2b from Optum Rx, US$100.0b from Optum Health and US$19.7b from Optum Insight.
Market Cap: US$333.3b
UnitedHealth Group fits this screener as a large, profitable health care business that adds defensive, dividend paying exposure away from the tech heavy S&P 500 concentration.
"The company is addressing unanticipated changes in Medicare membership profiles which impacted 2025 revenue. They are taking measures to ensure complex patients engage in clinical and value-based programs, which should help stabilize and potentially increase future revenue."
What happens to margins if one less visible cost and utilization swing lands differently from what current Medicare and Optum planning assumes?
If that utilisation swing is what you are watching, the full narrative for UnitedHealth Group explains how UnitedHealth Group’s revenue mix and margin risks could be quietly shifting beneath the surface.

Minerals Technologies (MTX)
Overview: Minerals Technologies develops mineral based products and environmental systems used in consumer goods, packaging, infrastructure and industrial applications worldwide.
Operations: Minerals Technologies generates about US$1.1b from Consumer & Specialties and US$1.0b from Engineered Solutions, with sizeable United States exposure.
Market Cap: US$2.1b
Minerals Technologies fits this dividend and quality value screen as a smaller industrial materials business that offers asset based cash flows and tech light diversification just as index concentration in Apple and Nvidia increases.
"Ongoing investments in capacity expansions for high-growth, sustainable products (e.g., sustainable aviation fuel purification, animal health solutions, fabric care, and pet litter in Asia) are positioned to benefit from global population growth, urbanization, and heightened sustainability demand, directly supporting revenue growth and above-average margin expansion."
What happens to Minerals Technologies’ earning power if one still emerging set of sustainability driven end markets grows faster than current expectations?
If that sustainability curve is what you care about, the full narrative for Minerals Technologies explains where Minerals Technologies’ earnings power could accelerate and what risks might quietly cap the upside.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time headlines catch the next breakout, early entries are already flying. Scan curated lists that are still under the radar and consider acting before they become widely followed.
- Look for resilient compounding potential by tracking companies in the 31 resilient stocks with low risk scores that seek to keep portfolio volatility contained while momentum slows elsewhere.
- Explore structural demand shifts by reviewing the 39 power grid technology and infrastructure stocks, which highlights businesses connected to grid upgrades, electrification spending and infrastructure refresh cycles.
- Identify cash generative AI exposure by using the 37 profitable AI stocks that aren't just burning cash, focused on businesses incorporating AI while maintaining attention on earnings, cash flow and balance sheet discipline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com