
Does Leadership Transition Change The Bull Case For Mosaic Stock (MOS)?
- Mosaic announced that longtime executive Karen Swager, Executive Vice President, Operations, plans to retire. Senior Vice President and Chief Administrative Officer Walt Precourt is set to take over the operations role from December 1, while Swager remains a senior advisor until the second quarter of 2027.
- The handover places Mosaic’s global production footprint, environmental and safety programs, and procurement and shared services under a single executive who has already led its phosphate, potash, and strategy work. This consolidation could influence how the business manages costs and operational reliability.
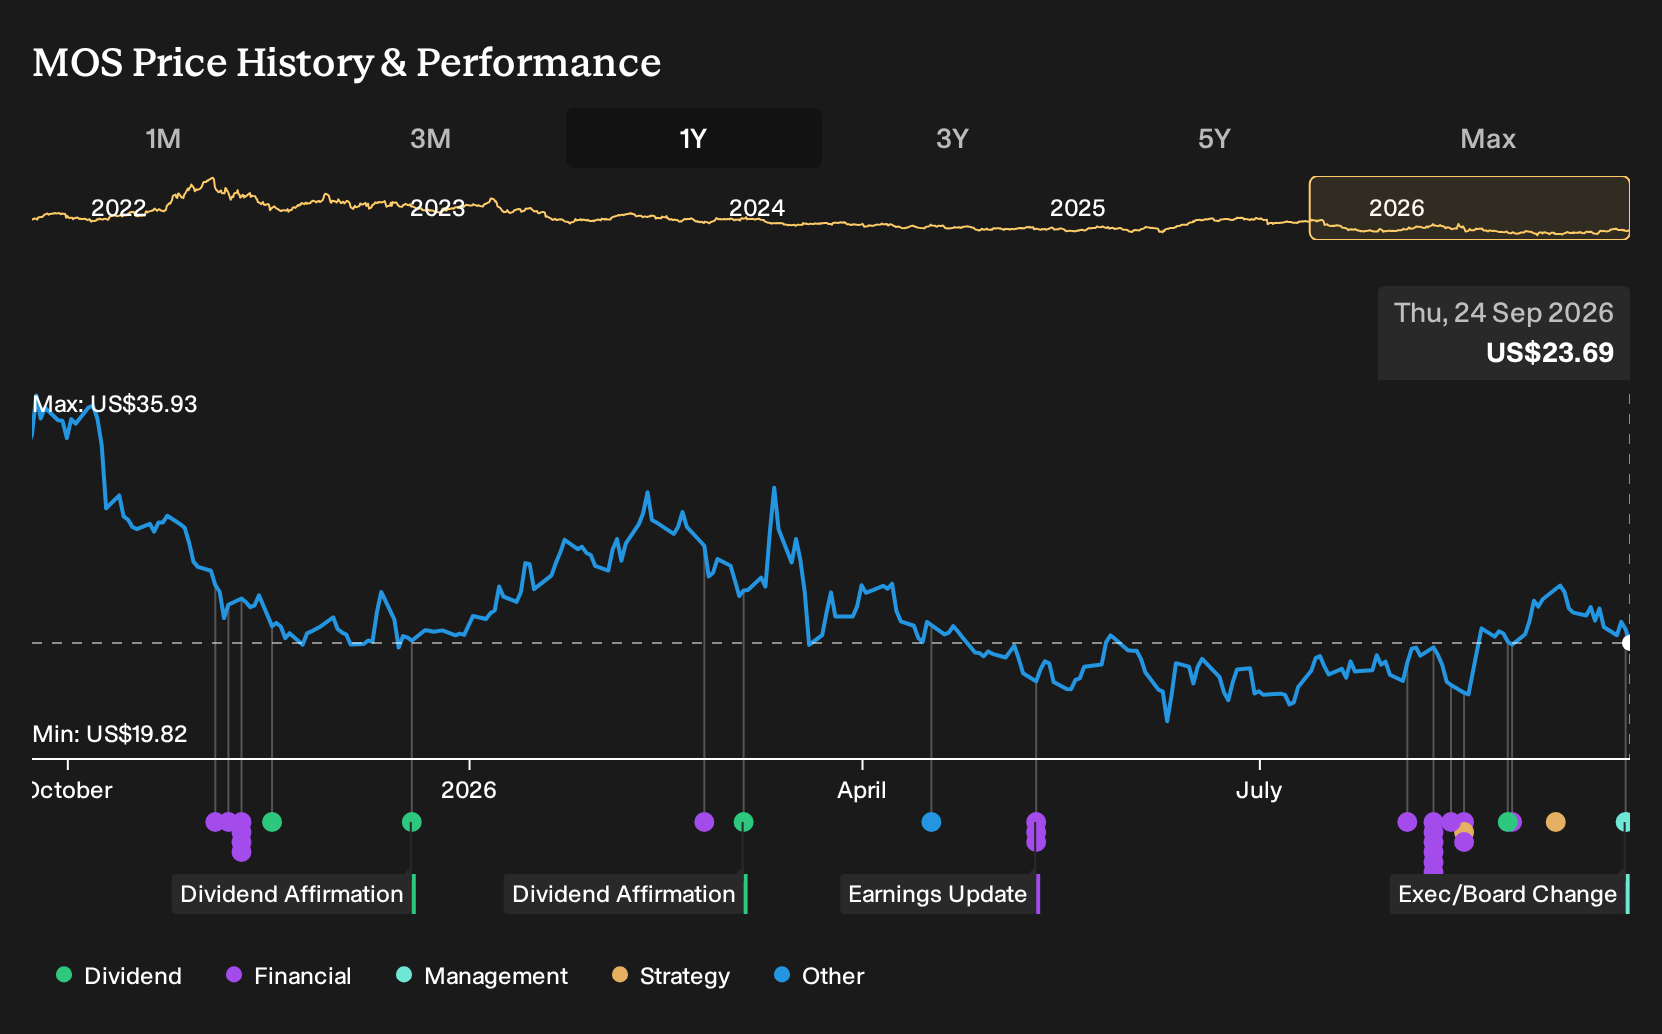
- We will now assess how Mosaic’s investment narrative could be affected by this operations leadership shift and tight global fertilizer supply.
Scan how Mosaic’s leadership shake-up compares with other materials players by zeroing in on list of solid balance sheet and fundamentals (23 results) in similar capital intensive sectors.
Mosaic Investment Narrative Recap
To own Mosaic, investors need to trust that tight fertilizer supply and steady farm demand can support pricing while the business works through an unprofitable patch. In the short term, the key swing factor remains fertilizer pricing and volumes, especially in Brazil and U.S. phosphates. The leadership shuffle itself is unlikely to change that in the near term.
What could matter is how effectively Mosaic executes on cost control, asset reliability, and environmental compliance, with operations and EHS now under one leader. If projects in automation and maintenance stay on track, that would support efforts to improve margins. If regulatory or environmental costs climb faster than expected, earnings risk is likely to remain a central concern.
The most relevant disclosure here is that Mosaic is currently loss making, with interest costs and dividends not well covered by earnings. That puts real weight on Precourt’s expanded remit. Operational missteps could make already limited financial flexibility even tighter, especially if fertilizer prices soften or credit conditions in Brazil become more restrictive.
Analysts currently model a shift away from the recent loss of US$638.5 million, helped by efficiency projects, tight global supply, and higher value products. The leadership transition is likely to be judged on whether production reliability improves, unit costs ease, and the business can move closer to the profit path that is being modeled.
Mosaic's current earnings of US$45.0 million are projected by analysts to reach US$421.4 million by 2029. This implies an earnings increase of about 9x, while revenue is expected to be around US$12.7b and remain fairly flat each year over that period.
Uncover why Mosaic's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts Mosaic’s push into advanced fertilizers front and center. The most optimistic analysts were already penciling in revenue of about US$13.6b and earnings of roughly US$968.6 million by 2029, far above consensus. With the operations role changing hands, those upbeat assumptions may shift. It is worth comparing these contrasting stories before deciding how this leadership move fits your own thesis.
Explore 5 other Mosaic fair value estimates, including one that suggests as much as 149% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mosaic research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mosaic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mosaic's overall financial health at a glance.
Looking For More Mosaic-Inspired Investment Ideas?
If Mosaic has sharpened your thinking about balance sheets, earnings power, and leadership risk, it can be helpful to scan a wider field of candidates with similar financial discipline before committing fresh capital.
- Prioritize financial resilience by starting with companies that pair robust balance sheets with solid fundamentals using the list of solid balance sheet and fundamentals (23 results).
- Focus on price versus quality by filtering for businesses that appear mispriced relative to their fundamentals through the 30 high quality undervalued stocks.
- Target portfolio income by hunting for higher yielding payout streams that still clear key financial checks with the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com