
3 Logistics Stocks That Could Gain From North American Supply Chain Shifts
North American supply chains are being redrawn in real time as questions swirl around the future of USMCA, new cross border tariffs bite and boardrooms rethink where plants and warehouses should sit. That sort of upheaval can punish some stocks and create fresh openings in others. This article walks through three USMCA exposed logistics and supply chain providers and how this policy reset could matter for their long term story.
The three logistics stocks below are just a sample set, and the full screen surfaced 55 other North American supply chain and freight providers with equally compelling stories that are not covered here. To identify and analyze the highest conviction opportunities that fit your own risk and return preferences, head straight to the North American Supply Chain Resilience and Logistics Providers screener.
Radiant Logistics (RLGT)
Overview: Radiant Logistics is a third party logistics provider that manages technology enabled air, ocean, and ground freight across North American supply chains.
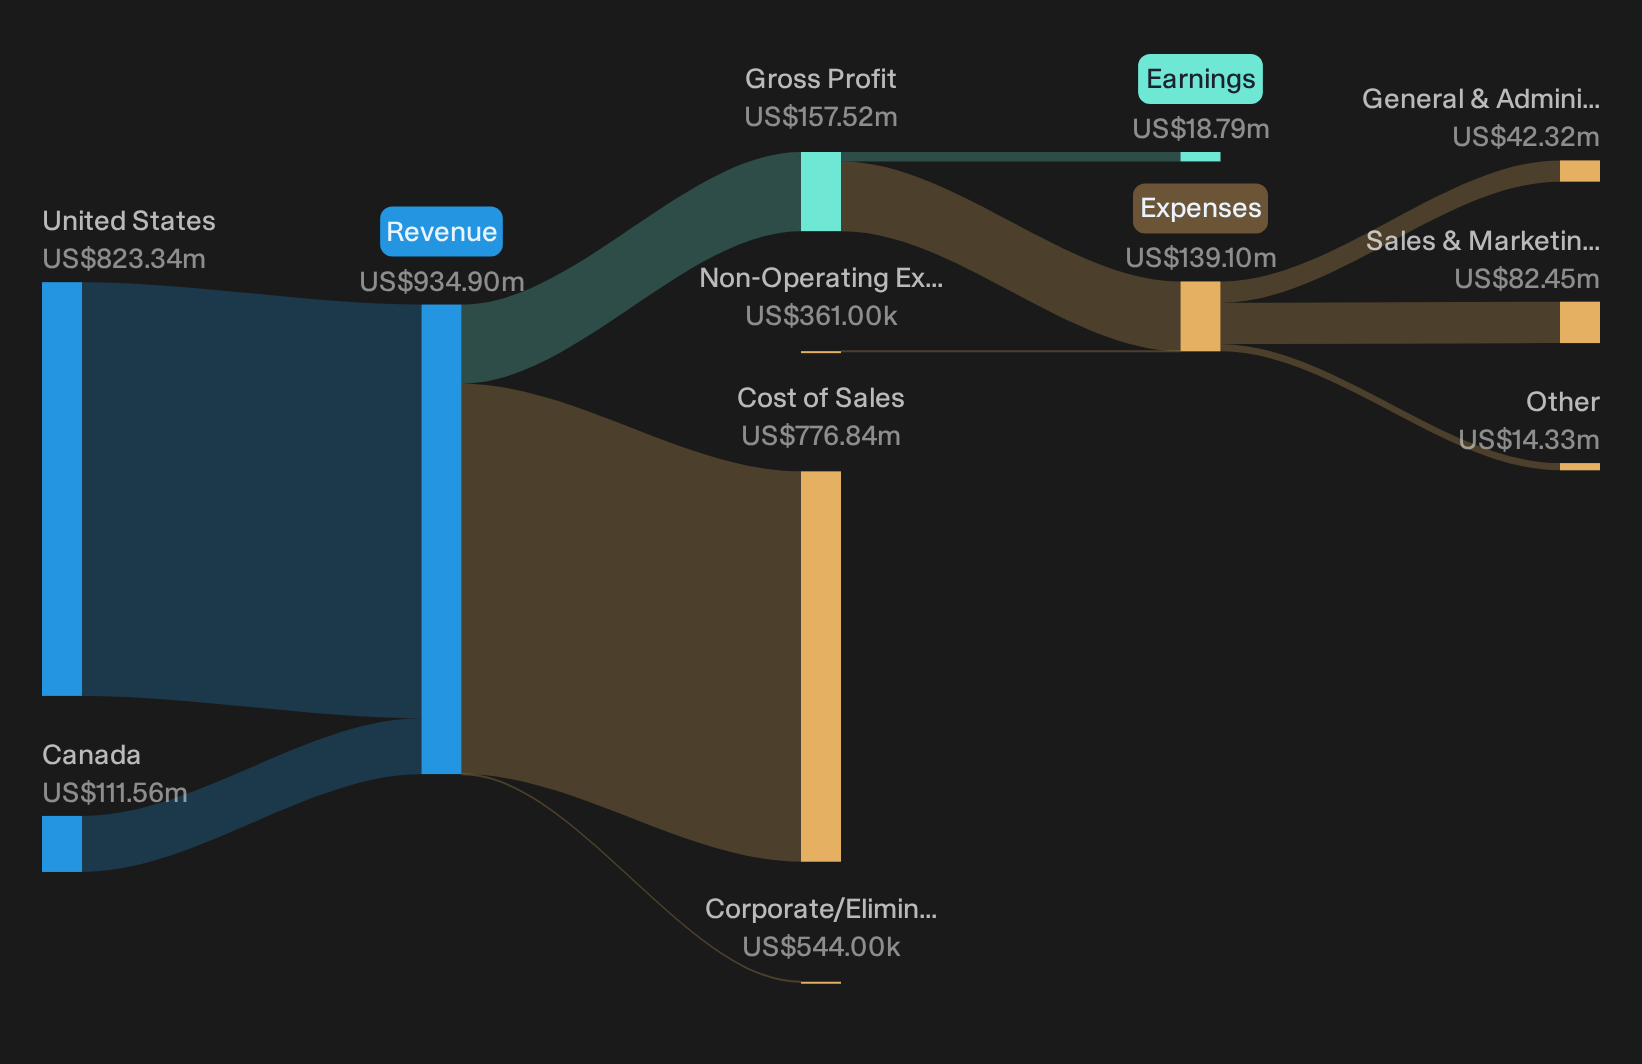
Operations: Radiant Logistics generates about US$934 million from transportation air freight services, primarily in the United States at about US$823 million and Canada at about US$112 million.
Market Cap: US$407 million
Radiant Logistics sits right in the flow of goods between the U.S., Canada, and Mexico. This positioning makes its technology and freight network central to how shippers rethink supply routes under shifting USMCA rules and fresh tariff friction.
"Although the Navegate platform offers faster deployment and deeper shipment visibility during trade and route disruptions, customer adoption might progress gradually."
The real swing factor for Radiant Logistics is how that slower than expected shift in shipper behavior ultimately feeds through to margins.
That margin question is the real hinge for Radiant Logistics, and the full narrative for Radiant Logistics shows how shifting customer behavior could either compress returns or begin to accelerate operating leverage.
Hub Group (HUBG)
Overview: Hub Group is a North American freight specialist that coordinates intermodal, trucking, warehousing, and logistics services for retailers and manufacturers.
Operations: Hub Group generates about US$2.2b from Intermodal and Transportation Solutions and around US$1.6b from Logistics, primarily within the United States.
Market Cap: US$1.9b
For this supply chain resilience screen, Hub Group matters because it helps big shippers rewire how freight moves across rail, truck, and warehouse networks as cross border trade gets more complicated and time sensitive.
"Record intermodal service levels, closer collaboration with rail partners and a single rail network position Hub Group to win more over the road conversion in upcoming bid cycles, which directly supports intermodal revenue and can help mix driven earnings."
What really shapes the Hub Group story now is how one unresolved pressure on reporting credibility influences the value investors place on those freight flows.
That credibility question is exactly what the full narrative for Hub Group unpacks, separating short term noise from areas where Hub Group’s earnings power could be quietly accelerating.

Ryder System (R)
Overview: Ryder System runs outsourced truck fleets, warehouses, and supply chain operations that keep North American manufacturers and retailers supplied and delivered.
Operations: Ryder System generates about US$6b from Fleet Management Solutions, US$5.6b from Supply Chain Solutions and US$2.3b from Dedicated Transportation Solutions, with around US$11.9b coming from the United States plus smaller contributions from Canada and Mexico.
Market Cap: US$9.1b
Ryder System matters in this screen because it is the kind of full stack logistics partner large shippers turn to when USMCA rules, tariffs, and cross border volumes make in house fleets and warehouses too complex to manage alone.
"Ryder's sustained investment and growth in asset-light supply chain and dedicated solutions reflects its focus on e-commerce, omnichannel fulfillment, and logistics outsourcing, and supports contract-based, recurring revenues and margin stability."
The real story for Ryder System is how one quiet shift in customer outsourcing appetite filters through to pricing power and long term contract economics.
That contract shift is the hinge. The full narrative for Ryder System shows how Ryder System’s mix of assets and recurring contracts could help translate that outsourcing trend into cash flows that are potentially less cyclical and may grow at an accelerating pace.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every headline catches up, the cleanest entry points can be gone. Scan these curated shortlists before momentum gets away and act now.
- Target steadier income streams by reviewing the 7 dividend fortresses and spot high-yield payers that could support your portfolio when growth stories cool.
- Explore potential AI momentum with the 37 profitable AI stocks that aren't just burning cash and focus on businesses already turning AI into real earnings instead of just burning cash.
- Prepare for possible infrastructure opportunities using the 39 power grid technology and infrastructure stocks and track companies tied to grid upgrades while they remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com