
AutoZone (AZO) After Earnings And Store Growth Looks Fully Valued
AutoZone (AZO) is back in focus after its latest quarterly update, with fresh earnings, record store expansion and mixed market reaction putting the stock on many investors’ watchlists this month.
Over the past year, AutoZone has been a rollercoaster for shareholders, with the share price sliding on a 1-year total shareholder return that declined 30.8%. During the same period, the business crossed US$20b in annual sales, opened its 8,000th store and reported quarterly earnings that beat profit expectations. Recent share price pressure therefore appears to be more about shifting sentiment and perceived risks than a lack of operational activity.
Compare AutoZone’s latest moves with those of other retailers that have resilient balance sheets and cash flows by checking the hand picked list of solid balance sheet and fundamentals (23 results) in the same space.
The stock now trades near a 1 year low even as AutoZone reports higher sales, more stores and record earnings per share. Is most of the value already reflected, or is there still upside left in the valuation?
Most Popular Narrative: 1% Overvalued
AutoZone last closed at $2,861.75, sitting just below the narrative fair value of $2,829.08. This frames the stock as essentially fully priced with little gap between the two figures.
The new-store economics arrived this quarter with numbers attached. A store now assumes $1.7 million in first-year sales, ramping to $2.7 million by year six, against an average investment of $2.9 million. This is a path management says produces roughly 15% ROIC by year four and north of 20% by year six. The prior call’s answer to the same underlying question was qualitative: new stores were “performing better” than the pro forma, full stop. Investors who wanted math instead of adjectives got it.
See why 1 investors see AutoZone as 1% overvalued.
Result: Fair Value of $2,829.08 (ABOUT RIGHT)
Still, AutoZone’s narrative could be tested if domestic DIY weakness persists or if SG&A keeps rising faster than the growth initiatives can justify.
Find out about the key risks to this AutoZone narrative.
Another View on AutoZone’s Valuation
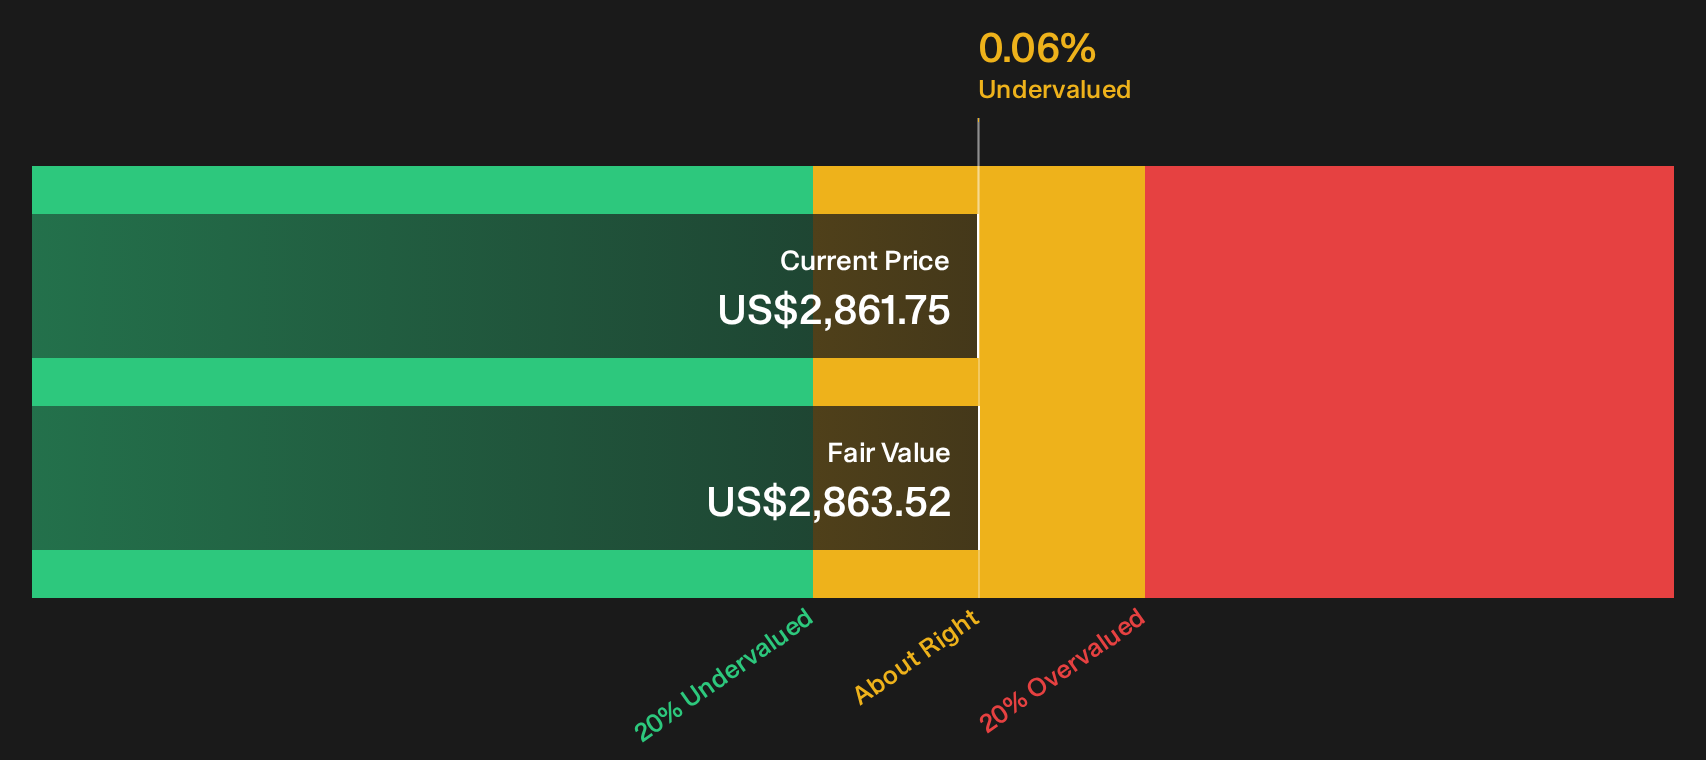
That fair value of $2,829.08 lines up almost perfectly with our DCF estimate, which puts AutoZone at $2,863.52 based on future cash flows. On this view the stock at $2,861.75 screens as essentially in line with the model. If both methods say “about right,” the question is where the real mispricing is likely to come from next: the story or the numbers?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this AutoZone story feels finely balanced between risk and reward, act quickly by checking the underlying data for yourself and pressure testing every assumption. Then compare what you see with the 4 key rewards and 2 important warning signs.
Looking for more AutoZone investment ideas?
Do not stop your research with AutoZone alone. Use the Simply Wall Street screener to spot fresh opportunities before they slip past more cautious investors.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (23 results) that pair financial strength with fundamental support.
- Hunt for potential mispricings by reviewing the 30 high quality undervalued stocks that combine quality metrics with compressed valuations.
- Prioritize capital preservation by focusing on the 31 resilient stocks with low risk scores that score well on stability and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com