
Is Enpro (NPO) Still Below Fair Value On Its Move To $311?
Enpro (NPO) drew fresh attention after its recent share move, with the stock closing at $311.19. Investors are weighing this price against the company’s fundamentals in sealing and advanced surface technologies.
Recent trading tells a mixed story for Enpro. The 1-day share price return of 1.88% and 7-day gain of 8.47% come after the 90-day share price return declined 17.95%, while the 5-year total shareholder return of 271.89% shows how strong longer-term momentum has been.
Compare Enpro’s latest move with a curated pool of industrial and capital-goods peers by scanning the list of solid balance sheet and fundamentals (23 results) for other businesses with resilient financial foundations.
Enpro looks like a high quality industrial technology business, yet the recent surge to $311.19 after a choppy quarter raises a tougher issue. Is this strength fairly reflected in the valuation or stretching it?
Most Popular Narrative: 20.1% Undervalued
Against the last close of $311.19, the most followed narrative assigns Enpro a fair value of $389.50, which implies a sizable valuation gap once forecast profits and cash flows are factored in at an 8.48% discount rate.
Continued portfolio transformation and disciplined capital allocation, including targeted organic investments, bolt-on acquisitions, and share repurchases, are expected to boost free cash flow, enhance return on invested capital, and support long-term EPS growth.
See why 2 investors see Enpro as 20% undervalued.
Result: Fair Value of $389.50 (UNDERVALUED)
Still, the Enpro narrative depends heavily on Advanced Surface Technologies delivering on expectations, while exposure to cyclical semiconductor and commercial vehicle markets could disrupt that path.
Find out about the key risks to this Enpro narrative.
Another View: Enpro on Earnings Multiples
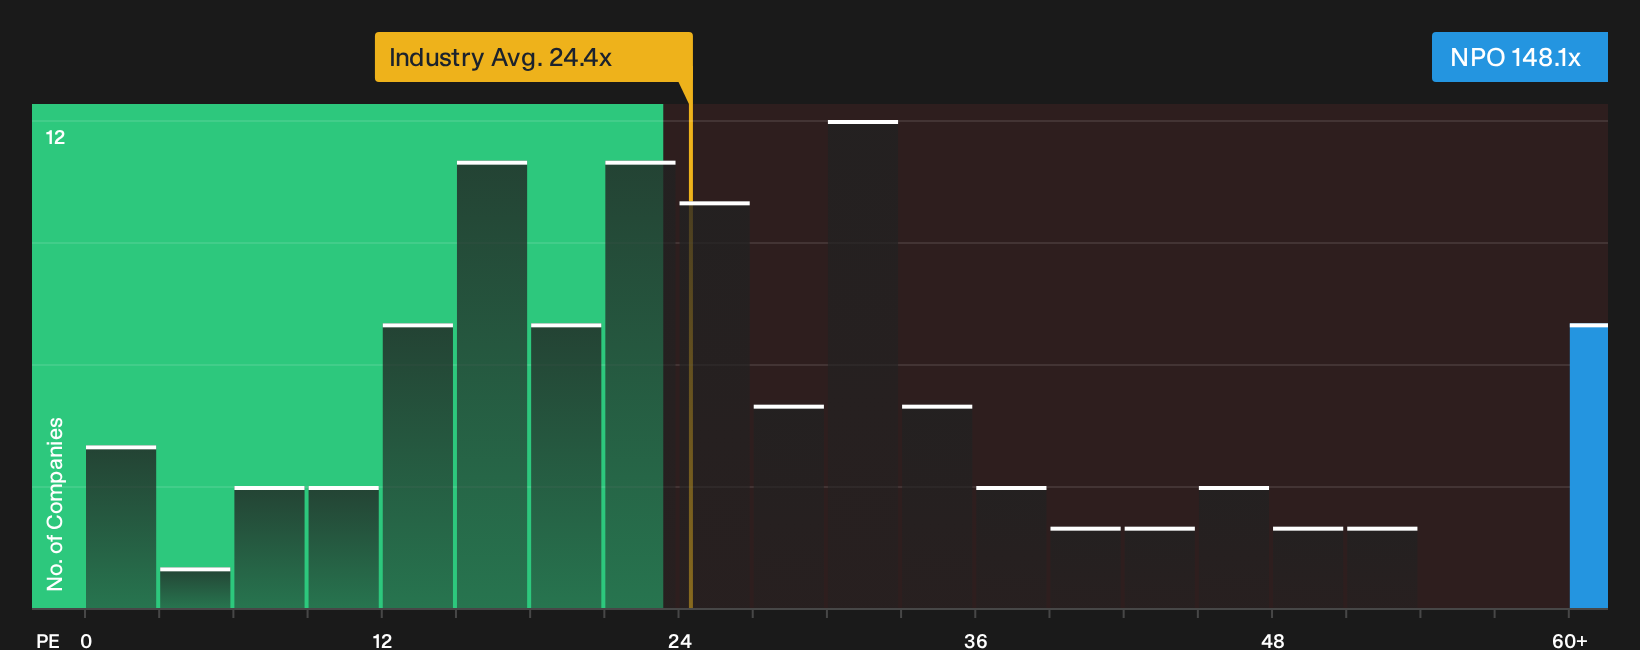
The fair value story for Enpro built on future cash flows and a $389.50 anchor runs into a very different picture when you look at today’s earnings. On a P/E of 148.1x, the stock trades at a heavy premium to both the US Machinery industry on 24.4x and peer average on 31.7x, and it also sits well above a fair ratio of 52.2x that the market could move toward over time.
That gap suggests investors are paying a high price right now for projected profit growth. The real question is how much execution risk you are comfortable with if sentiment shifts back toward that lower fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of optimism and concern around Enpro will mean different things to different investors, so move quickly and test the numbers against your own expectations. To help frame that view, start with the balance of 3 key rewards and 2 important warning signs
Looking for more Enpro investment ideas?
If Enpro has you thinking harder about price, quality, and risk, do not stop with one stock. Broaden your watchlist now and avoid missing stronger setups.
- Target resilient cash generators by scanning the 30 high quality undervalued stocks that pair robust fundamentals with prices that may sit below intrinsic value.
- Strengthen your income stream by reviewing the 7 dividend fortresses built around higher-yield companies with the potential to support regular payouts.
- Dial down portfolio stress by focusing on the 31 resilient stocks with low risk scores that highlight businesses with steadier balance sheets and more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com