
Humana (HUM) Expands CenterWell Distribution, Is It Still 9% Below Fair Value?
Humana (HUM) is back in focus after TempraMed Technologies signed a distribution agreement with CenterWell Pharmacy, Humana’s pharmacy brand, to supply temperature controlled medication storage products across the United States.
Humana’s share price has eased in recent weeks, with a 30-day share price return of down 2.4% and a 90-day share price return of down 0.9%, even as the year-to-date share price return sits at 43.8% and the 1-year total shareholder return is 51.6%. This suggests strong momentum over the past year despite some shorter term cooling, as investors weigh news like the CenterWell and TempraMed agreement against past three and five year total shareholder returns that have been more muted.
Scan how Humana compares with other insurers and healthcare players by tracking the momentum, quality and value signals across a curated set of 31 resilient stocks with low risk scores.
Bulls point to Humana’s strong 1 year rebound and recent CenterWell momentum, while bears highlight the softer 3 year record and modest pullback. Which case does the current valuation support next?
Most Popular Narrative: 9% Undervalued
Humana’s most followed valuation story pegs fair value at $419.04 versus the last close at $380.32. This leaves a modest narrative gap that hinges on how the Medicare Advantage margin restoration plan plays out.
Humana’s multiyear Medicare Advantage margin restoration plan that targets at least a 3% pretax margin by 2028, including 2027 bid discipline and exits from about 600,000 lower return plans with an aim to recapture a significant portion into higher value products, may influence earnings and net margins.
See why 60 investors see Humana as 9% undervalued.
Result: Fair Value of $419.04 (UNDERVALUED)
Still, the Humana story can slip if exits from Medicare Advantage plans reduce member retention more than expected, or if tighter coding scrutiny increases compliance costs.
Find out about the key risks to this Humana narrative.
Another View: What Humana’s P/E Is Signalling
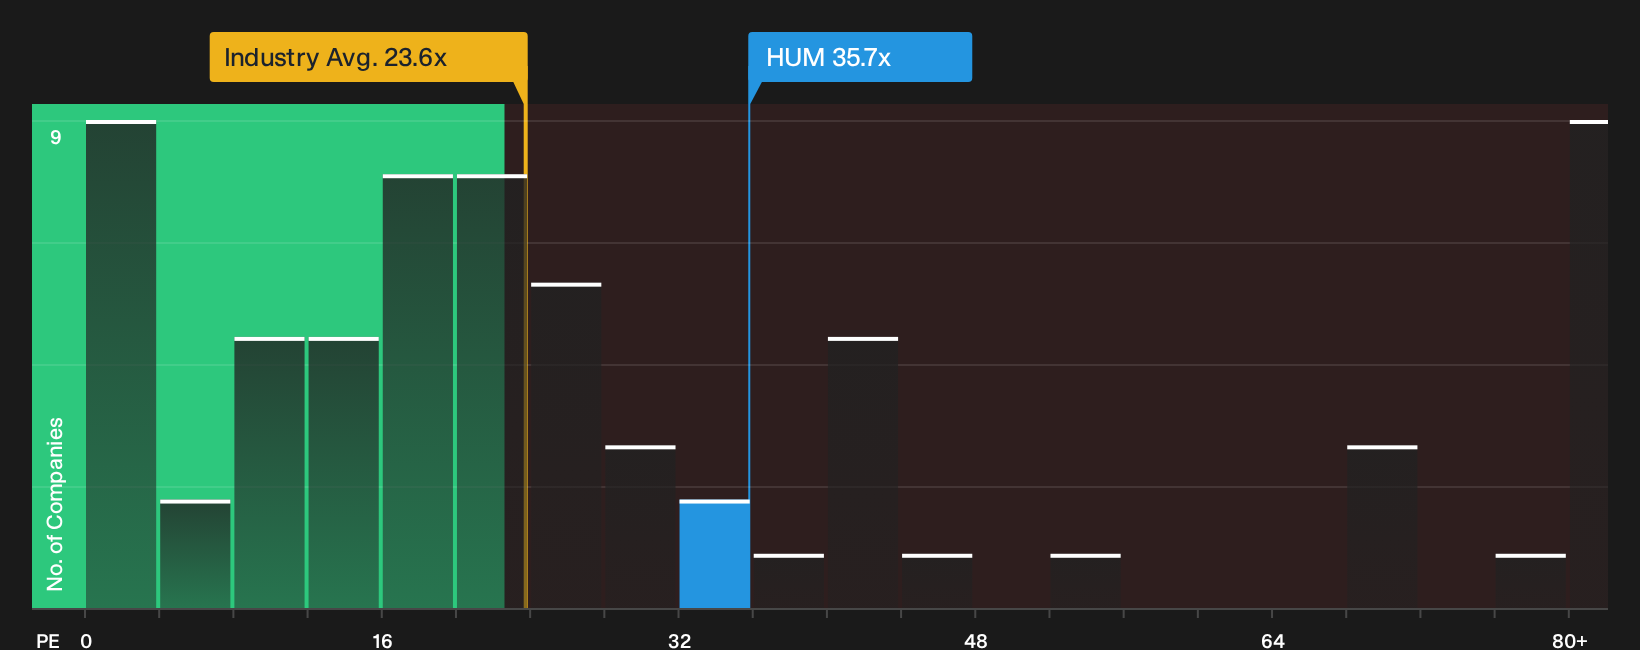
Humana may look 9% undervalued on fair value estimates around $419, yet the market is charging a P/E of 35.7x versus 23.6x for the wider US Healthcare sector and 24.4x for peers, while the fair ratio is 46.2x. Is that gap a safety margin or a premium that could compress?
See what the numbers say about this price in our valuation breakdown, then weigh it against your own expectations for Humana’s earnings path and risk tolerance. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Humana’s valuation and recent share price moves leave the story open for interpretation. Act while the data is fresh and form your own stance using the 2 key rewards and 2 important warning signs.
Looking for more Humana sized investment ideas?
If Humana has you thinking more broadly about your portfolio, do not stop here. Put fresh ideas on your radar before the market does.
- Target potential opportunities by scanning a curated pool of ideas that look mispriced using the 30 high quality undervalued stocks.
- Focus on companies with relatively cleaner finances and sturdier funding through the list of solid balance sheet and fundamentals (23 results).
- Review a focused set of under-the-radar prospects in the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com