
Intuitive Machines (LUNR) Jumped, But What Is Driving Attention Now?
Intuitive Machines (LUNR) is back in focus after handing over the SXM-11 satellite to SiriusXM and securing a contract to build two IM 300 platforms for a new customer segment.
These contract wins have arrived during a choppy year for Intuitive Machines, with the share price down 12.19% year to date and 20.67% over 90 days, yet supported by a 55.45% 1-year total shareholder return that indicates momentum has been rebuilding rather than fading.
Compare Intuitive Machines with a curated group of space and aerospace contractors riding similar contract momentum through our 93 robotics and automation stocks to see how this story stacks up against other automation and satellite plays.
For Intuitive Machines, the tension is clear. Do you lean into the recent contract wins and recent jump, or wait for the math to offer a cleaner entry?
Most Popular Narrative: 32% Undervalued
On the most followed valuation view, Intuitive Machines carries a fair value of $23.00 against a last close of $15.70. This frames the recent pullback as a discount rather than a warning sign for investors who buy into that thesis.
Balancing High-Growth Potential with Capital DilutionIntuitive Machines (LUNR) has successfully shifted from a high-risk startup to a Lunar Infrastructure Prime, backed by a $943M backlog and a strategic pivot toward high-margin data services via the Lanteris acquisition. While the trajectory toward positive Adjusted EBITDA in 2026 is clear, the current stock price reflects a "perfection premium" that overlooks recent share dilution.
See why 25 investors see Intuitive Machines as 32% undervalued.
According to sorkdhkddlek, that fair value estimate anchors on a $23.00 "going concern" level that already bakes in recent share dilution, a $943m backlog and the tilt toward higher margin data services rather than one off lunar delivery work.
The same narrative flags that analysts are building their case off a forecast 17.9% annual revenue expansion while Intuitive Machines remains unprofitable over the next three years. This means any shortfall in execution could hit both earnings expectations and sentiment quickly.
For readers weighing that 32% valuation gap against risks like ongoing losses, a P/S ratio that is flagged as expensive versus peers, and a history of shareholder dilution, the key question is whether the current $15.70 price already reflects those pressure points or still underestimates the long run economics of the lunar services model described above.
Result: Fair Value of $23.00 (UNDERVALUED)
Still, Intuitive Machines faces real pressure if projected revenue acceleration or lunar mission execution stumbles, or if further capital raises deepen shareholder dilution and weaken the case for the stock being 32% undervalued.
Find out about the key risks to this Intuitive Machines narrative.
Another View On Intuitive Machines’ Valuation
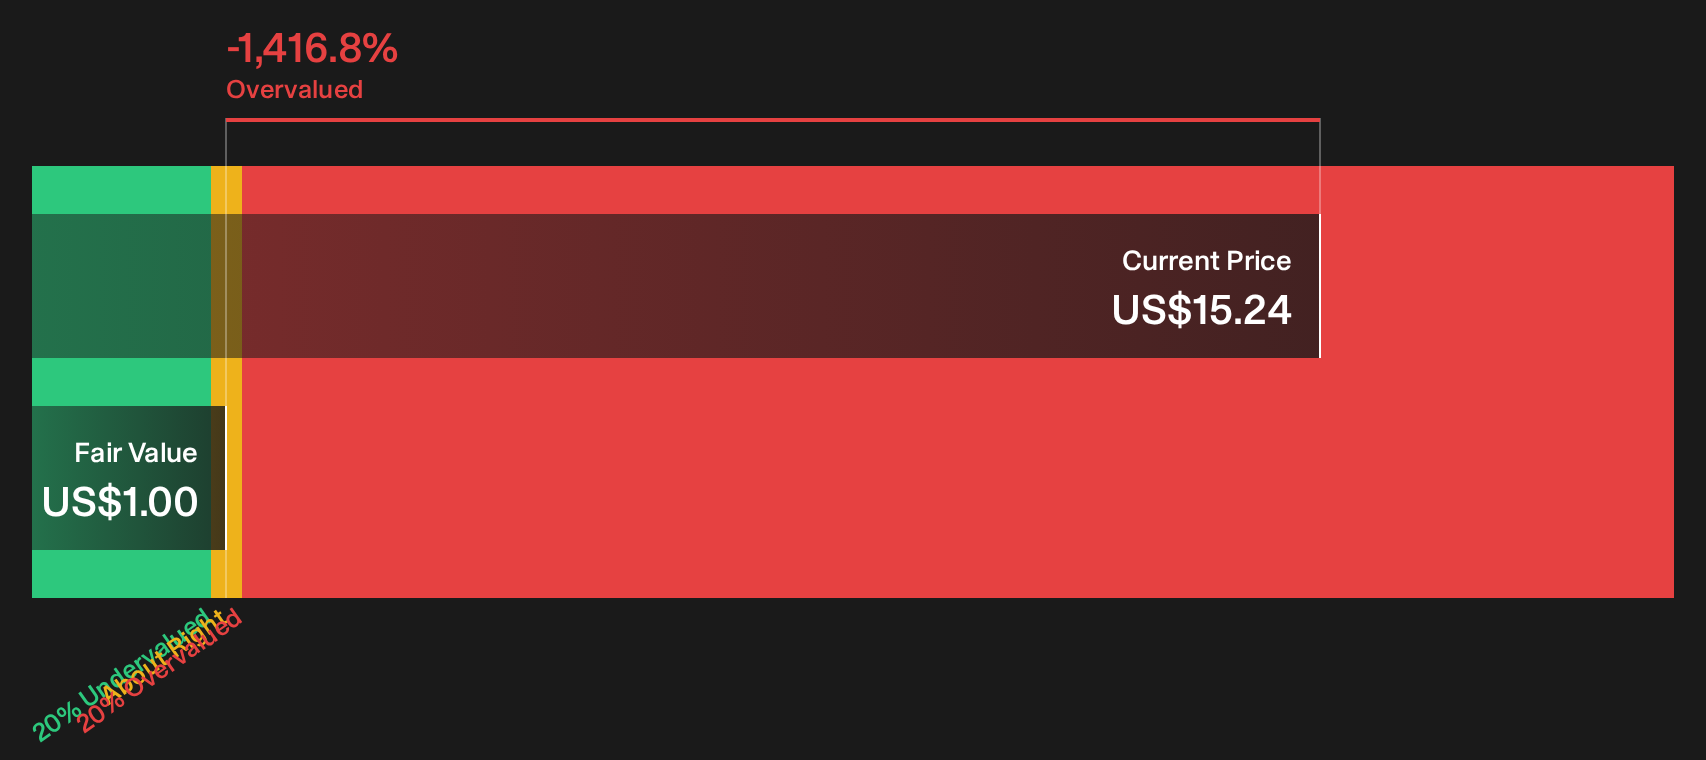
The first narrative leans on a revenue multiple that points to Intuitive Machines being undervalued at $23.00. A second lens tells a very different story. The SWS DCF model estimates future cash flows at only $1 per share, which implies the current $15.70 price is expensive rather than cheap. That gap raises a simple question: Is the crowd focusing too much on revenue potential and not enough on cash generation risk?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of contract momentum and valuation friction around Intuitive Machines feels unresolved, consider acting promptly to review the data yourself and stress test your own thesis against the 1 key reward and 3 important warning signs.
Looking for more Intuitive Machines style ideas?
If Intuitive Machines has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to surface other opportunities that fit your playbook.
- Target bargain opportunities by zeroing in on quality businesses trading below intrinsic value through the 30 high quality undervalued stocks.
- Strengthen your income foundation by scanning for reliable high-yield payers using the 7 dividend fortresses.
- Prioritise resilience by filtering for companies with robust finances and low-risk profiles via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com