
Micron Technology (MU) Is Facing Fresh Short Pressure
- Micron Technology (NasdaqGS:MU) is facing new scrutiny after Martin Shkreli and Michael Burry publicly disclosed short positions in the stock.
- Shkreli has argued that Micron's recent share price gains are outpacing what he sees as sustainable memory pricing power.
- Burry has highlighted the risk of future oversupply as global memory production expands, questioning current optimism around long-term margins.
- The choice by Shkreli and Burry to short Micron after strong share price gains raises fresh questions about memory-cycle timing and pricing power, but the business story runs wider than these high profile shorts. Take a look at 4 other big wins we have identified for Micron Technology.
For a broader view of how memory and storage suppliers fit into the build out of data centers and AI hardware, explore 84 AI infrastructure stocks.
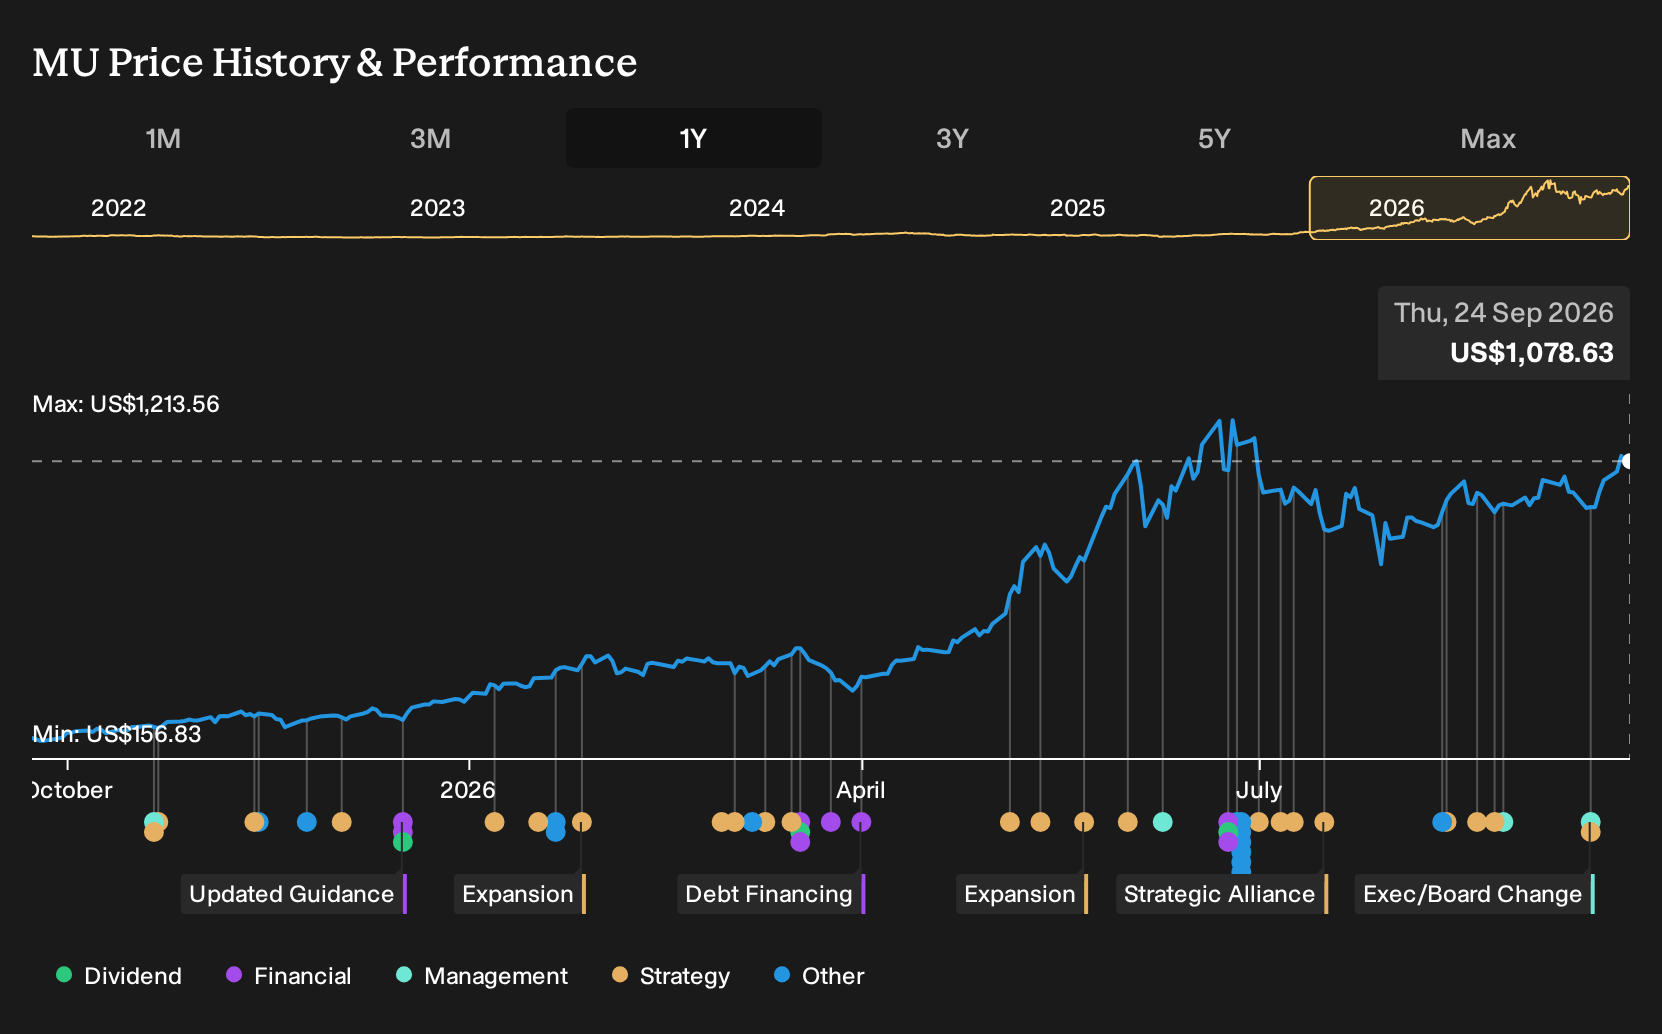
Micron Technology produces memory and storage components that feed into everything from PCs and smartphones to cloud data centers and AI hardware. As a result, any shift in long term pricing power or future supply can ripple across a wide swath of the semiconductor industry.
See which insiders are buying and selling Micron Technology following this latest news.
Micron’s AI supercycle story meets high-profile skepticism
The Micron Technology Narrative assumes AI-driven demand keeps advanced DRAM and high-bandwidth memory tight enough for years to support higher-value products and more resilient earnings, while still accepting that competition and capital intensity are real risks. Shkreli and Burry going public with shorts puts a spotlight on how fragile that balance might be.
"Explosive growth in AI and data center applications is driving robust, sustained demand for advanced DRAM and high-bandwidth memory, resulting in improved pricing power..."
See how the full story points towards a $1,507 fair value for Micron Technology.
The shorts directly lean against the Narrative’s clearest reward, that tight supply and multi-year AI contracts can keep pricing power durable. Their focus on future oversupply challenges the idea that Micron can keep shifting mix toward high-value HBM and DDR5 without running into a classic DRAM down-cycle like past periods for Samsung or SK Hynix.
This episode also presses on a flagged risk, that heavy investment in new fabs and advanced nodes can strain free cash flow if pricing weakens. If more investors adopt the Shkreli or Burry view, volatility already flagged in the risk data could rise further, even if the long-run AI memory thesis proves directionally right.
For anyone following Micron Technology, this news matters only in relation to which story you think is more likely: extended AI-driven tightness or a return to old-style memory cyclicality.
The Micron Technology story still hides one thing in the earnings footnotes
Headline profit figures only tell part of the Micron Technology story, and internal checks are flagging something in the way those results are built that most holders never review. See what our checks flag about the quality of Micron Technology's earnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com