
Affirm Holdings (AFRM) Tests Valuation After Rolling Out Its New Underwriting Model
Affirm Holdings (AFRM) has rolled out a new transformer-based underwriting model at checkout, using in-house machine learning to reassess consumer credit histories in real time and expand approvals for thin-file borrowers.
Recent price action suggests investors are weighing this new underwriting model against a mixed return profile for Affirm Holdings. The share price closed at US$71.63 after a 5.2% 1-day share price gain, yet the 30-day share price return is down 8.1% and the 1-year total shareholder return has declined 8.1%. This follows a very large 3-year total shareholder return and points to momentum cooling after a strong multi‑year run as the market reassesses growth potential and risk.
Compare Affirm Holdings' AI-driven underwriting push with other payment and fintech players that screen well on balance sheet strength and fundamentals using our curated list of solid balance sheet and fundamentals (23 results)
So is Affirm Holdings’ recent pullback telling you something about the underlying business, or just marking a swing in sentiment that has run ahead of fundamentals and valuation?
Most Popular Narrative: 28% Undervalued
The most followed narrative currently values Affirm Holdings at $99.23 per share, well above the recent close at $71.63. This frames the underwriting model update against expectations for the long term earnings profile.
Rapid growth and strong engagement with Affirm Card, an actively invested product moving toward high attach rates and greater offline usage, expands Affirm's addressable market beyond online retail, diversifies revenue streams, and drives higher frequency of transactions, which should accelerate GMV and contribute to margin improvement.
Deployment of AdaptAI and other proprietary risk/pricing analytics gives Affirm a competitive edge in optimizing merchant and consumer conversion, reflected in measurable GMV increases for participating merchants, which will help support higher gross margins and revenue efficiency over time.
See why 51 investors see Affirm Holdings as 28% undervalued.
Result: Fair Value of $99.23 (UNDERVALUED)
Still, the bullish Affirm Holdings story can unravel if a major merchant partnership falls away or if 0% APR products squeeze profitability harder than analysts expect.
Find out about the key risks to this Affirm Holdings narrative.
Another View: What the SWS DCF Model Says About Affirm Holdings
The first narrative presents Affirm Holdings as undervalued at $99.23 per share. However, the SWS DCF model tells a more cautious story. On that cash flow view, an estimate of $61.25 per share sits below the current $71.63 price, which frames the stock as overvalued instead. Which lens feels closer to how you think Affirm’s future will actually play out?
For readers who want to see how this second approach is built from the ground up, including the key cash flow inputs and discount rate, Look into how the SWS DCF model arrives at its fair value.
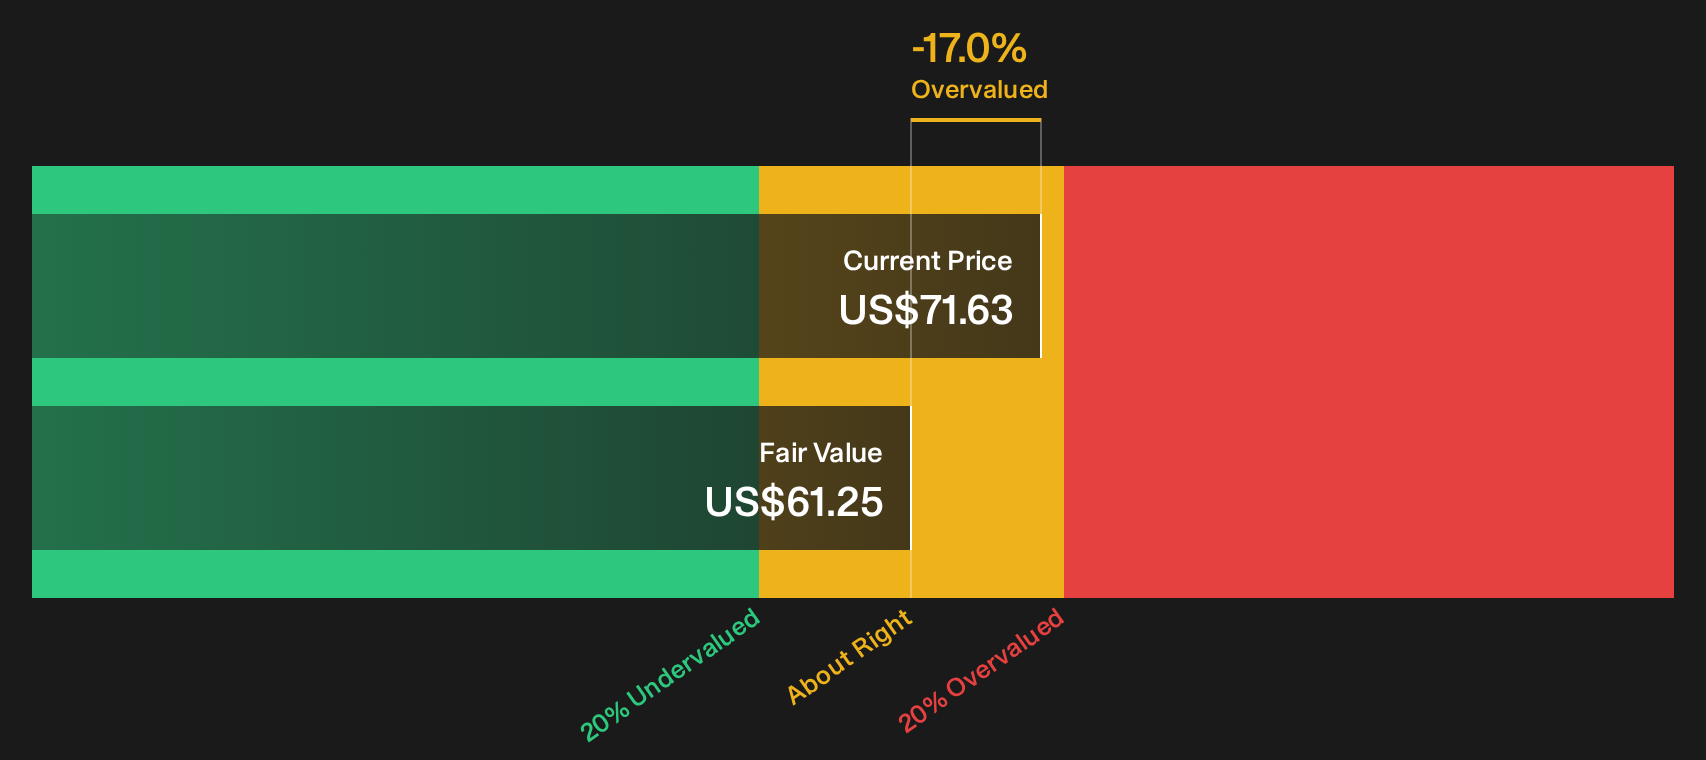
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Affirm Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Affirm Holdings is clearly split, so move fast, interrogate the numbers and stress test both sides of the story using the 5 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Affirm Holdings?
Do not stop with Affirm Holdings. Use this pullback as a prompt to refresh your watchlist and source fresh ideas that fit your risk and return style.
- Target potential bargains early by scanning for quality companies that trade below their estimated worth through the 30 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses with robust payouts using the 7 dividend fortresses.
- Sleep easier during volatility by searching for shares that score well on resilience with the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com