
Data Center Bond Raise Could Be A Game Changer For CleanSpark (CLSK)
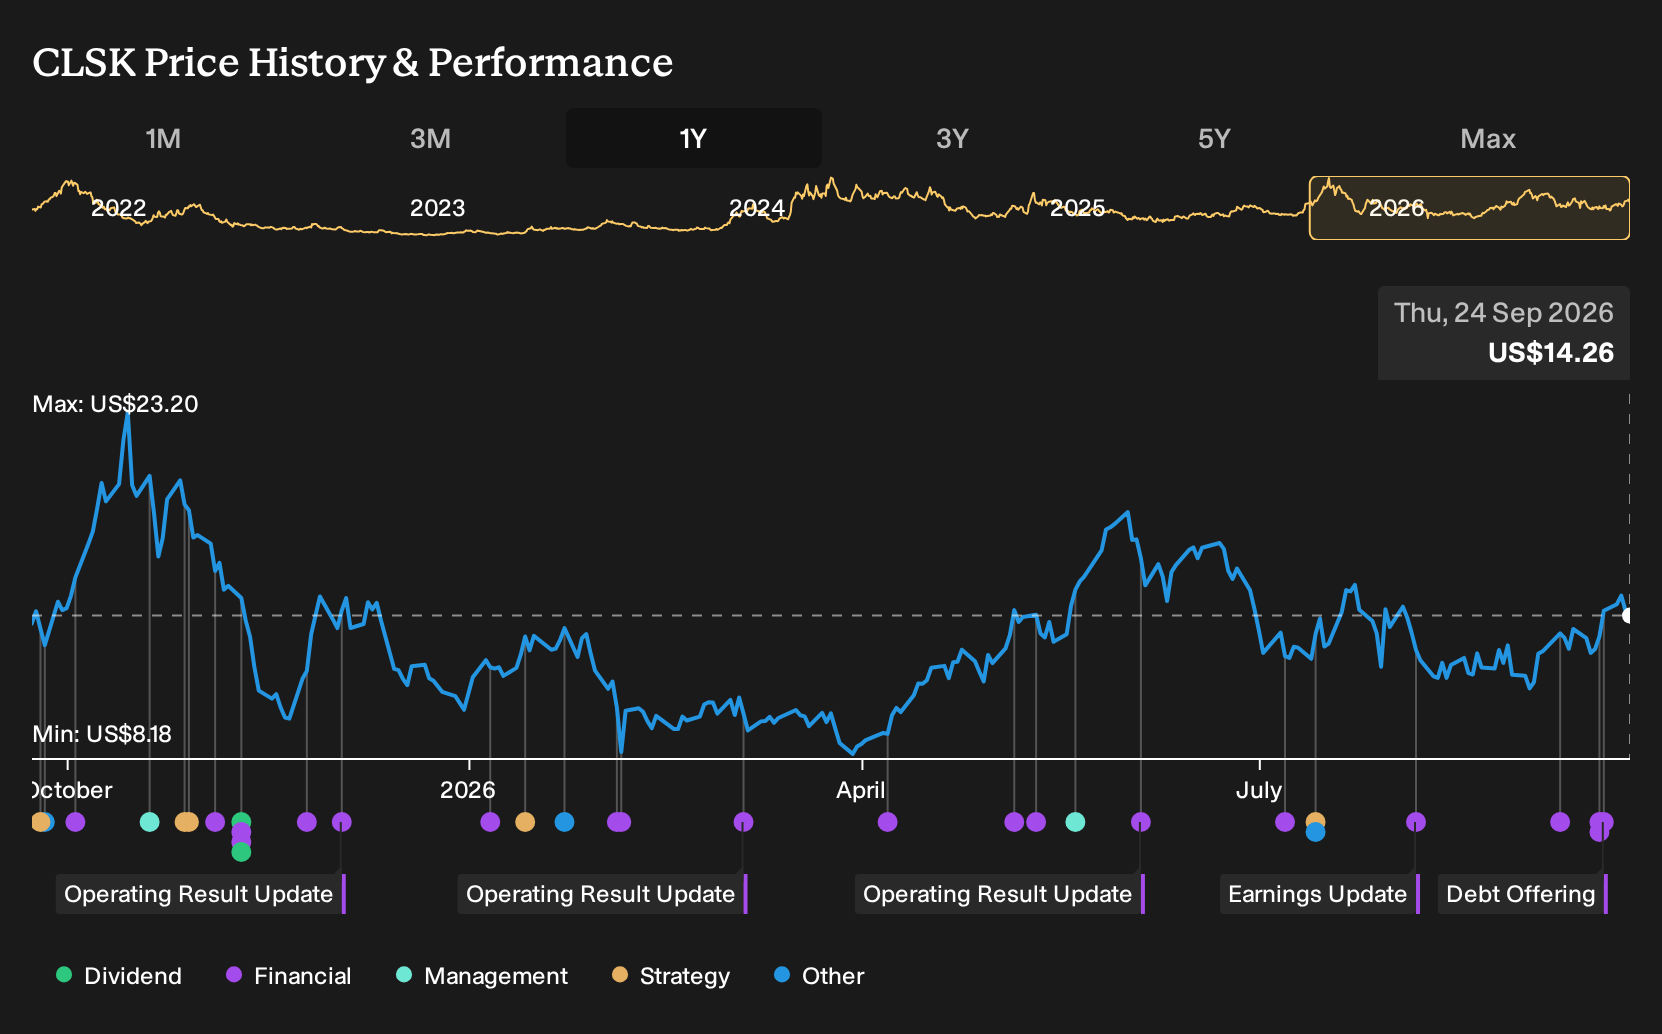
- CleanSpark recently completed a fixed income deal, issuing US$2.24186b of 7.875% senior secured notes due 2031, with guarantees and security over key project assets.
- The bond proceeds are earmarked for the Sandersville data center build, reimbursing prior equity funding and setting up debt service reserves. This highlights the capital intensity and financing structure behind CleanSpark's expansion plans.
- We will now look at how this large 2031 note financing shapes CleanSpark's investment narrative and future capacity build out.
Compare CleanSpark's massive 2031 bond raise with other capital intensive plays building out power hungry infrastructure by scanning our hand picked 84 AI infrastructure stocks in one shot.
CleanSpark Investment Narrative Recap
To own CleanSpark, you need to believe large scale, power efficient Bitcoin mining can deliver acceptable returns through cycles, even with earnings still in the red. The 7.875% notes give the Sandersville project dedicated funding and visibility on completion, which supports CleanSpark's capacity ambitions but also hard wires interest costs into a business already tied to Bitcoin pricing.
In the short term, the key swing factor remains Bitcoin economics relative to CleanSpark's mining costs. The biggest risk is that heavy CapEx and new debt land on a weak Bitcoin backdrop, which could squeeze margins and stretch a balance sheet already flagged as having less than one year of cash runway.
The most relevant recent update is the completion of the US$2.24186b 7.875% senior secured notes due 2031. This deal is tightly linked to the Sandersville data center, with proceeds allocated to finishing the build, reimbursing prior equity invested, and funding debt service reserves for that project.
For you, the questions are clear: Can CleanSpark bring Sandersville online on time and on budget? Can it run that extra capacity at a low enough cost to offset fixed coupon payments while remaining exposed to Bitcoin price swings, ongoing halving events, and an industry where less efficient peers may still be exiting?
CleanSpark's narrative projects US$857.1 million revenue and US$98.0 million earnings by 2029, assuming 8.1% yearly revenue growth and an earnings improvement of about US$1.1 billion from a loss of US$1.0 billion today.
Uncover why CleanSpark's fair value indicates a 67% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts anchor on CleanSpark’s ability to build and scale faster than peers. Before this bond deal, that group was modeling revenue reaching about US$1.2b and earnings of roughly US$148.2 million by 2029. Those projections reflect a far more upbeat view, which could shift once this 7.875% debt load is fully digested.
Explore 4 other CleanSpark fair value estimates, including one that suggests as much as 82% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CleanSpark research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CleanSpark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CleanSpark's overall financial health at a glance.
Looking For More Ideas Beyond CleanSpark?
If this CleanSpark bond story has you thinking about portfolio balance, it can help to scan a wider set of opportunities using the Simply Wall St Screener.
- For investors hunting for mispriced quality, start with a focused set of 30 high quality undervalued stocks that pair strong fundamentals with more modest expectations.
- If capital preservation sits near the top of your checklist, you may prefer a 30 resilient stocks with low risk scores built around resilient balance sheets and lower volatility profiles.
- Those who want sturdier income streams can filter for 7 dividend fortresses that combine higher yields with robust cash coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com