
TD SYNNEX (SNX) Stock Drops As Hyve Cash Drag Clouds Record Profit
Traders punished TD SYNNEX on the headline, driving the stock down almost 10% to about US$259, even as the company posted what it called a record quarter. The market fixated on the hit to cash flow from roughly US$1b of working capital tied up in Hyve, while earnings power told a different story.
Non GAAP operating income climbed to US$736m and non GAAP EPS reached US$5.68, both ahead of management’s own guidance range. The reaction centered on balance sheet strain. The core question now is whether that cash drag proves temporary or something more stubborn.
Love TD SYNNEX’s earnings power but worried about that Hyve related working capital drag on cash flow? Check out the list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$21,558.4m vs. US$15,650.9m (up around 38%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$416.2m vs. US$224.8m (up around 85%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$5.25 vs. US$2.76 (up around 90%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 1.7% vs. 1.3% (margin improved)
Prefer clean visuals instead of another wall of earnings tables and balance sheet figures? See TD SYNNEX’s full financial picture with a focus on valuation in the interactive company report for TD SYNNEX.
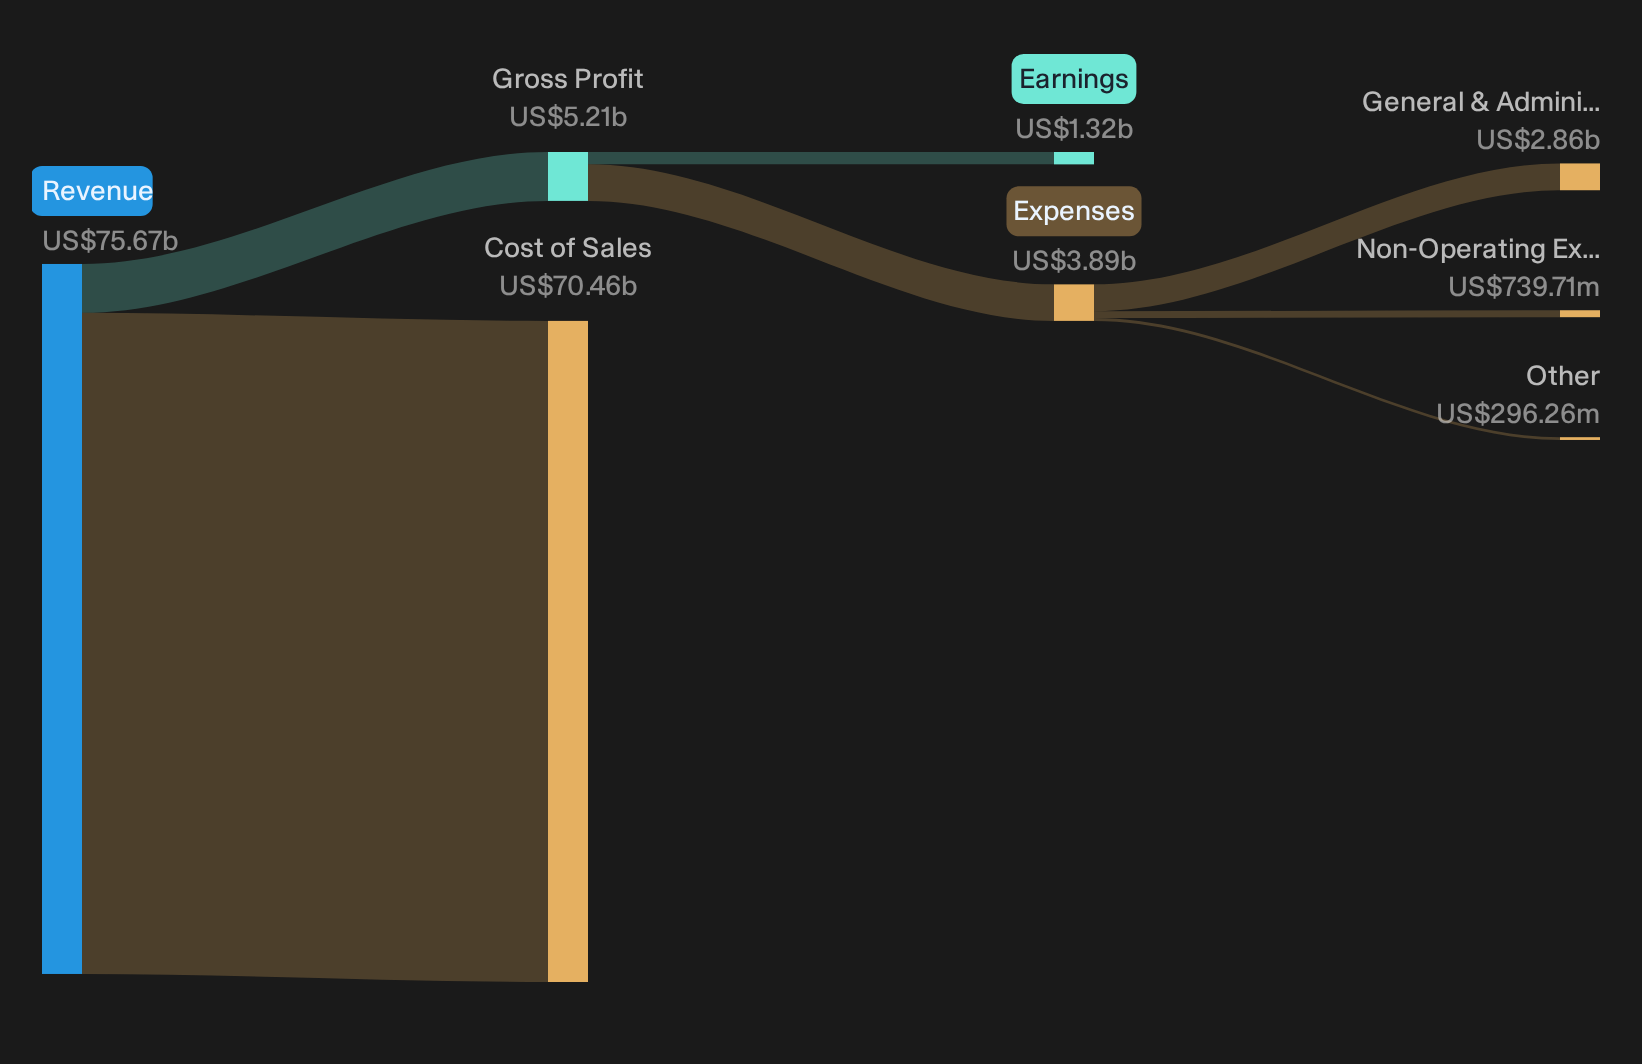
TD SYNNEX Bull Story Meets Real Hyve Milestones
Bulls have argued that TD SYNNEX can turn Hyve into a second engine of earnings power, while keeping distribution margins resilient through AI infrastructure demand and a cost plus approach. This quarter gives hard proof on several of those points. Hyve gross billings reached US$7.0b, more than doubling year on year, with manufacturing now roughly two thirds of that activity. This lines up with the narrative of full rack AI programs ramping on new capacity in Nevada and elsewhere.
Distribution did its part too. Gross billings of US$24.8b with stronger data center and Advanced Solutions, plus a modest improvement in operating margin on billings to 1.95%, support the idea that the cost plus model and vendor designations are holding up. Non GAAP operating income of US$736m and EPS of US$5.68 above guidance show that the dual engine earnings hypothesis is, at least operationally, on track this quarter.
Compare that earnings engine with street expectations and see whether Wall Street thinks TD SYNNEX can sustain it. Track the consensus price target analysis for TD SYNNEX.TD SYNNEX Bears Focus on Cash, Not EPS Beat
Bearish investors have argued that TD SYNNEX is piling on fixed costs and working capital for Hyve just as hyperscaler demand could cool, leaving shareholders with weaker cash generation even if earnings per share look healthy. This quarter gives that concern fresh fuel. Non GAAP EPS of US$5.68 and Hyve billings of US$7.0b cleared expectations, yet free cash flow swung to roughly US$1b consumed as Hyve inventory and program ramps pulled net working capital up to US$6.5b.
Critics worry that “multi year” AI rack deals can still see volume cuts. The 3.61% Hyve operating margin on billings, well below last year’s 5.04%, suggests the biggest AI programs are lower margin and capital hungry. Management guidance calls for better cash conversion ahead, but the near term reality is clear: bears looking for working capital strain, thinner Hyve economics and a fragile utilization story just saw several of their milestones hit.
After a quarter where TD SYNNEX consumed roughly US$1b of cash to support Hyve working capital, it is fair to ask whether this is a one off or a sign of structural pressure on future cash generation. Review our independent risk analysis for TD SYNNEX which shows 1 important warning signOwn Your Next Investing Move
If the contrast between TD SYNNEX’s earnings strength and Hyve cash drain has your attention, register free with Simply Wall St and add it to a Watchlist so you can track share price against fair value and wait for the setup that fits your plan. Once you are invested, use the Portfolio Command Center to cut through headline noise and focus on the key developments that matter for your holdings. Round it out by tapping into thousands of perspectives through the Community and see how other investors are thinking about the same risks and opportunities. By spotting potential catalysts and pressure points early, you give yourself a better chance of staying ahead of the broader market.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Some stocks are building breakout momentum while others are quietly dropping into attractive territory under the radar for now. Consider researching opportunities early rather than waiting for broader attention.
- Target reliable income streams by scanning curated high yield opportunities through the 7 dividend fortresses while payout strength still appears aligned with balance sheet support and current conditions.
- Spot early movers in artificial intelligence infrastructure by reviewing the 84 AI infrastructure stocks before enthusiasm spreads and attention shifts fully toward the most widely followed large caps.
- Evaluate potential growth pivots among carefully filtered 8 elite penny stocks with strong financials that pair stronger balance sheets with active operations instead of purely speculative stories with no clear business traction.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com