
Is Dutch Bros (BROS) Undervalued On Strong Revenue Growth And Improving Profitability?
Dutch Bros (BROS) has drawn fresh attention after reporting strong revenue growth along with a fourth straight year of improving profitability, while the share price remains down sharply from earlier highs.
Recent trading tells a mixed story for Dutch Bros, with the share price at about $38.51 and a 30 day share price return that declined 24.61%. This extends a 90 day drop of 46.40% and a year to date fall of 38.05%, even as the 3 year total shareholder return is up 65.42%. This suggests long term holders have still seen meaningful gains while short term momentum has faded as investors reassess growth prospects and risk.
Spot fresh ideas by comparing Dutch Bros with a curated 16 high quality undiscovered gems that share strong fundamentals but have stayed off most investors' radar so far.Bulls point to Dutch Bros’ growing revenue base and improving profitability, while bears highlight the sharp share price reset. The next step is to see which side the current valuation leans toward.
Most Popular Narrative: 50.5% Undervalued
Compared to Dutch Bros' last close at $38.51, the most followed narrative pegs fair value at $77.76, which implies a wide gap that hinges on how much faith you put in long term store growth and margins.
The evolving menu, featuring specialty beverages, energy drinks, and an expanded food pilot, taps into the consumer trend toward premiumization and customization in beverages; these higher-margin offerings and incremental morning daypart food sales support higher average ticket sizes and future margin/earnings growth.
See why 80 investors see Dutch Bros as 50% undervalued.
Result: Fair Value of $77.76 (UNDERVALUED)
Still, the bullish Dutch Bros story could be challenged if labor costs stay elevated or if aggressive new shop growth leads to saturation and weaker returns.
Find out about the key risks to this Dutch Bros narrative.
Another View on Dutch Bros Valuation
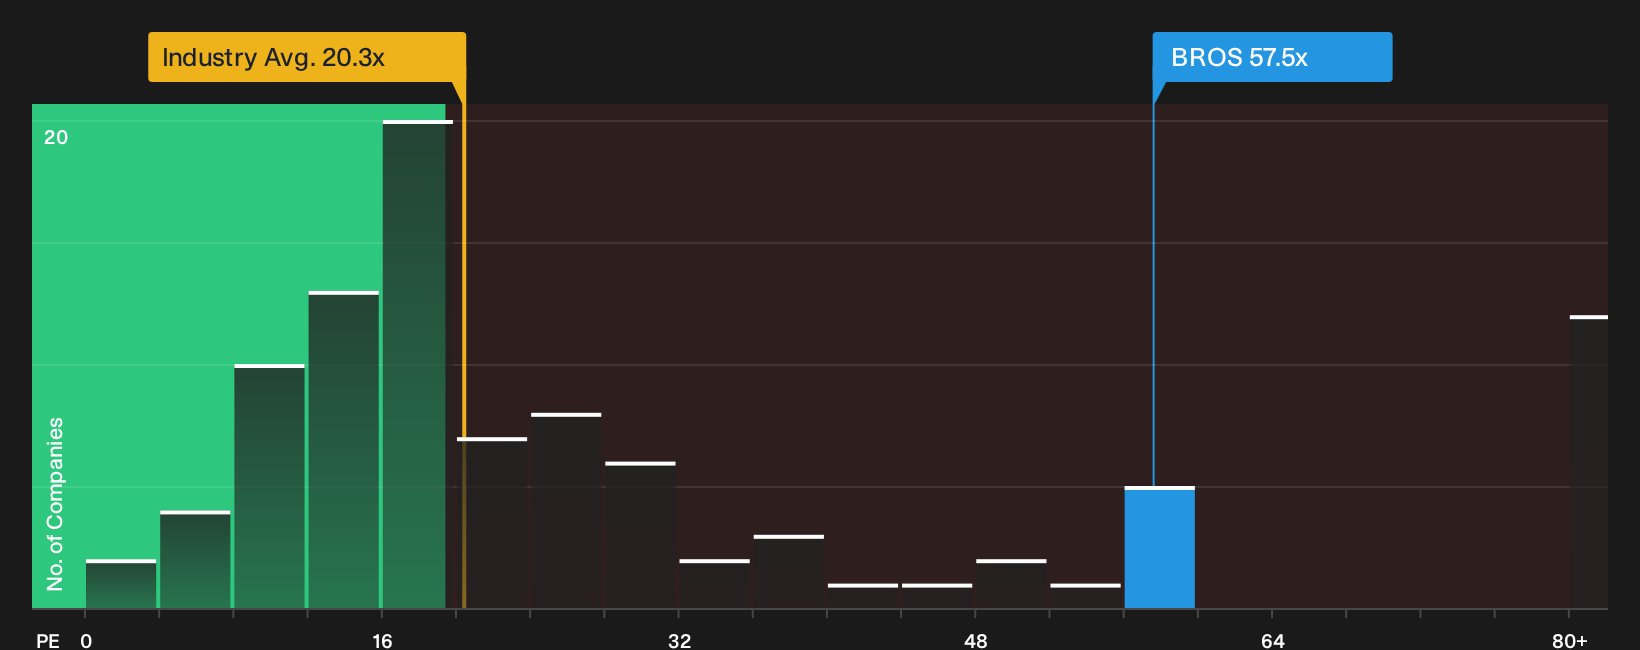
The DCF work suggests Dutch Bros is trading at a discount to its modeled cash flows, yet the market is still placing a rich P/E of 57.5x on the stock versus 39.2x for peers and 20.3x for the wider US Hospitality group. With a fair ratio of 27.9x flagged, that is a wide gap. Is the premium compensating you for growth, or simply adding extra valuation risk if expectations slip?
For a closer look at how the earnings multiple compares with what the numbers imply, and where that leaves room for upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of investors see optimism in Dutch Bros’ story, but the real question is how you read the risk and reward trade off for yourself. If you want to weigh the upside drivers directly, start with the 3 key rewards.
Looking for more Dutch Bros investment ideas?
If Dutch Bros has you thinking harder about risk, reward, and timing, do not stop at one ticker. Use focused screens to spot opportunities others ignore.
- Target potential mispricings by scanning a curated pool of quality companies trading below what their fundamentals might justify through the 30 high quality undervalued stocks.
- Prioritise resilience and capital strength by filtering for businesses with sturdy finances using the list of solid balance sheet and fundamentals (23 results).
- Hunt for steady income potential by reviewing companies that combine higher yields with staying power via the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com