
Alten (ENXTPA:ATE) Stock May Be Undervalued On Its Current Earnings
Alten has seen its share price move around over the years, and the current level asks a straightforward question. Is the stock price you see today properly supported by the earnings the business generates?
- Over the past 5 years the share price has fallen 39.4%, which puts the focus squarely on whether the current earnings base still justifies the valuation.
- The group earns its money by providing engineering and technology consulting services, so profitability, utilisation rates and how efficiently those fees turn into cash flow can play a big part in how much investors are prepared to pay for each euro of earnings.
- There is a second opinion on Alten worth weighing. See what analysts think Alten's shares could be worth.
For investors, the debate is whether Alten's present share price reflects a fair multiple of the earnings the company is producing today.
If you want extra context on whether Alten's earnings multiple feels reasonable, it can help to compare it with other mature tech and consulting stocks using the 177 high quality undervalued stocks
Is Alten Still Cheap on Earnings?
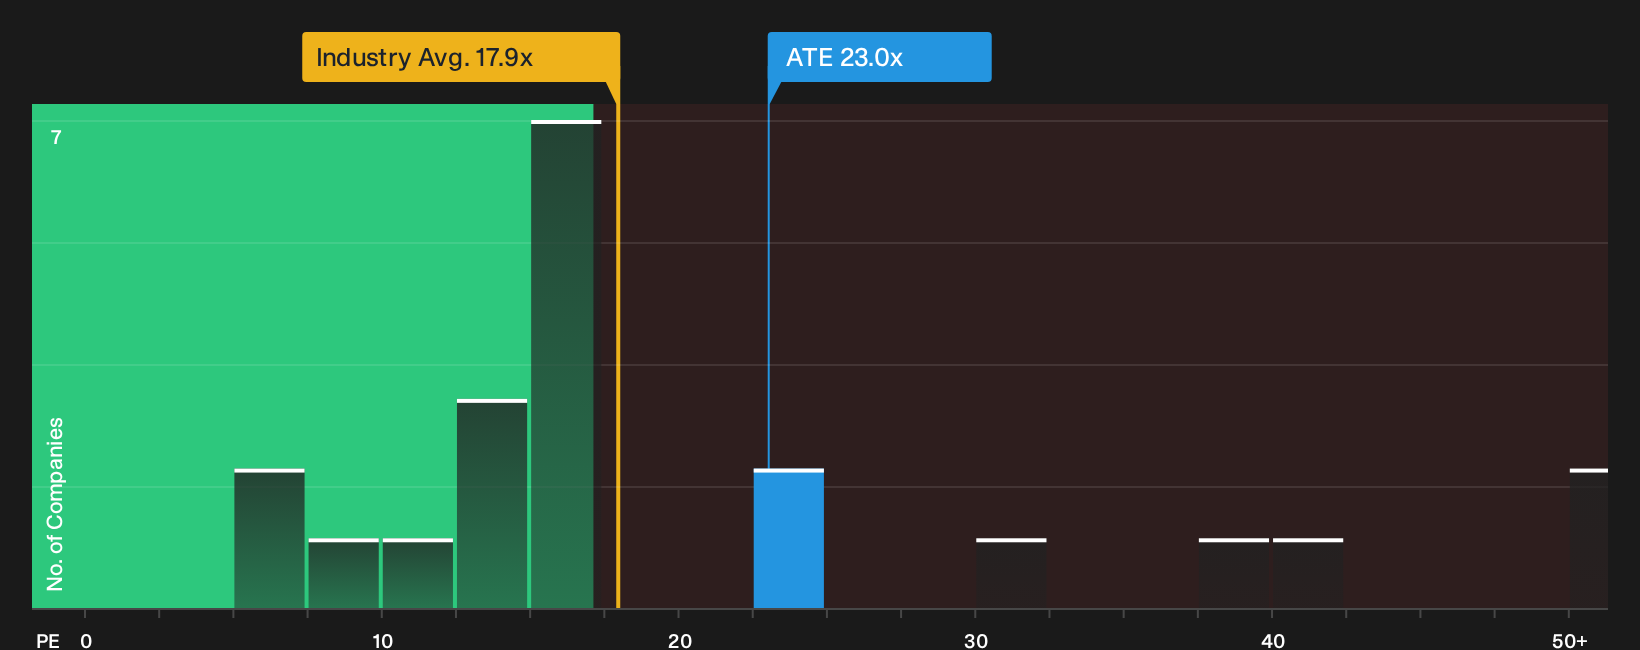
The P/E multiple fits Alten reasonably well because earnings are a central yardstick for a consulting group that converts billable work into profit. On this measure, the stock trades on about 23.0x its trailing earnings.
That compares with roughly 18.6x for the wider IT sector and about 12.9x for direct peers, so the market is already asking you to pay a higher price for each euro of Alten profit. The in house fair multiple, which adjusts for the group’s own growth profile, margins, size and risk, suggests the current P/E sits below what might be expected for this business. For an investor, the key question is whether Alten’s earnings quality and cash conversion are strong enough to justify that higher P/E against peers while still offering value against that tailored benchmark. Explore the numbers behind Alten's P/E valuation.
The Alten Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Alten valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to look meaningfully higher or lower than today’s price. Rather than relying on a single multiple or model output, each narrative lays out the key drivers behind its fair value view so you can compare those assumptions with Alten's reported results over time.
Alten inspires sharply different views, with one crowd seeing upside in a tougher project environment and another focusing on structural pressure on how it earns its fees.
Bull case: 26% undervalued
"Successful acquisitions, as evidenced by headcount increases from acquisitions, indicate potential revenue synergies and long-term earnings growth as these acquisitions are integrated…"
Discover why this Narrative puts Alten at 26% undervalued.
Bear case: 29% overvalued
"ALTEN is facing a fundamental shift in client demand as major sectors like automotive, aerospace, and telecoms rapidly ramp up offshoring to low-cost countries…"
Explore why this Narrative puts Alten at 29% overvalued.
Alten's valuation still hinges on one unresolved issue
Price and earnings only tell part of the story for Alten, because the research checks also flag specific areas of concern that investors may want to weigh before feeling comfortable with the risk profile. Take a closer look at 4 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com