
What Target (TGT)'s Retail Media Growth Means For Shareholders
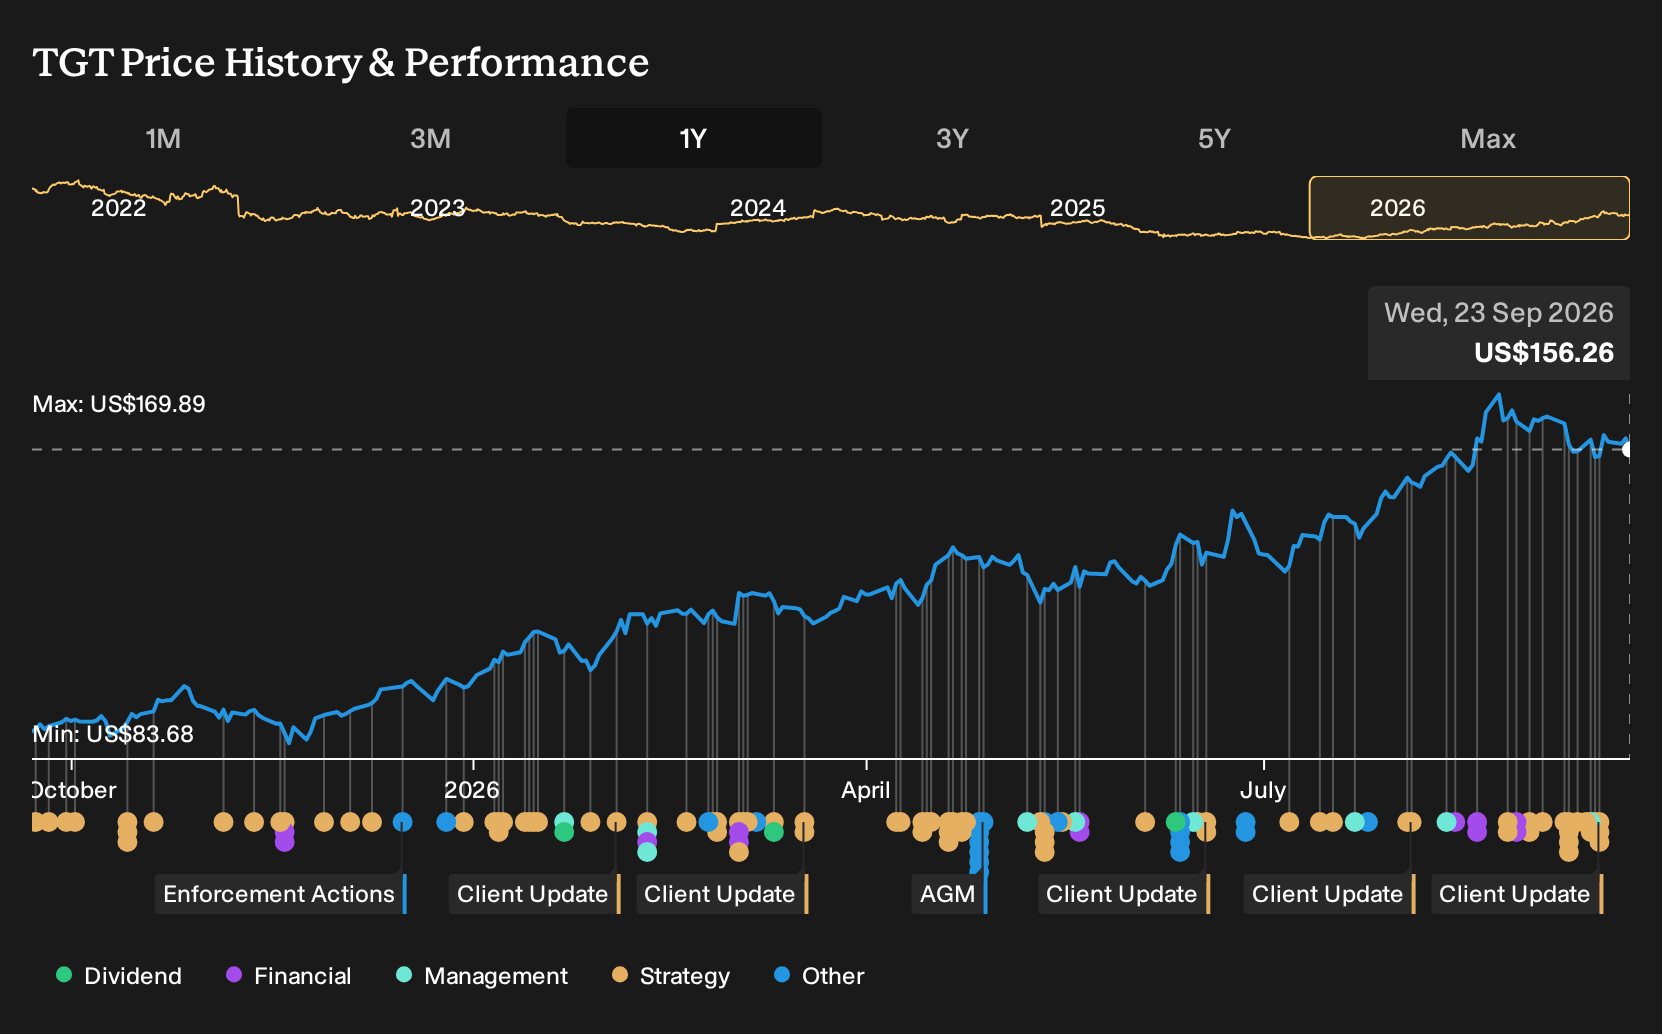
- Target Corporation declared a quarterly dividend of $1.16 per share, payable on December 1, 2026, and rolled out new premium beauty, food, and home-care partnerships across hundreds of stores and Target.com.
- Growth in Target's higher-margin Roundel retail media business and the curated Beauty Studio concept reflects a tilt toward more service-driven revenue streams.
- The focus now is on how this mix of retail media and premium partnerships could influence Target's broader investment narrative.
Compare Target’s mix of premium partnerships, retail media and regular dividends with other retailers by reviewing a curated set of resilient balance sheet plays in our list of solid balance sheet and fundamentals (23 results)
Target Investment Narrative Recap
To own Target, you need to believe the retailer can keep pushing shoppers toward higher margin areas like Roundel, Beauty Studio and premium food while holding onto share in everyday essentials. In the near term, the key issue remains execution on omnichannel convenience and merchandising that actually resonates with younger households, not just adding more product on shelves.
The latest dividend affirmation and partnership rollout does not materially change that near term catalyst. The biggest operational risk still lies in cost pressure and execution gaps in e-commerce versus top competitors, where missteps could erode margins and limit the benefit of these newer, higher margin revenue streams.
The dividend announcement is a clear marker of where Target is today. Management is choosing to maintain a long dividend track record with a US$1.16 quarterly payout and a history that now stretches to a 237th consecutive distribution since 1967, while still investing heavily in media, store experience and technology.
For you as an investor, that mix of ongoing cash returns and spending on Roundel, Beauty Studio and supply chain upgrades defines the trade off. The payout supports a more income oriented thesis, but the key factor still lies in how quickly these newer businesses scale relative to rising labor, regulatory and online fulfillment costs.
Target Earnings and Revenue Assumptions
Target's narrative projects US$119.0b revenue and US$4.6b earnings by 2029. This implies 3.4% yearly revenue growth and an earnings increase of about US$0.2b from US$4.4b today.
Discover how Target's fair value indicates a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts already expected Target to reach about US$121.1b in revenue and US$4.7b in earnings by 2029, helped by faster tech adoption and sharper execution. You might see this dividend and premium partner push as evidence for that more upbeat story, or as a reason to recheck both bullish and cautious forecasts.
Explore 5 other Target fair value estimates, including one that suggests as much as 42% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Target research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Target. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Target's overall financial health at a glance.
Looking For More Ideas Beyond Target?
If this Target story has you thinking about portfolio balance, it can help to compare it with other businesses that have different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential growth with tighter risk controls, filter for resilient companies using our 30 resilient stocks with low risk scores.
- If income is a priority, compare Target's payout with other high-yield candidates through the 7 dividend fortresses.
- To widen the opportunity set beyond well known stocks, scan for lesser known businesses with strong fundamentals via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com