
What Is Drawing Fresh Attention To Freeport-McMoRan (FCX)?
Freeport-McMoRan (FCX) put income on the table again, with its Board declaring a total cash dividend of $0.15 per share tied to the miner’s performance-based payout framework.
Freeport-McMoRan’s share price has been volatile in recent months, with a 1-week gain of 1.74% but a 1-month decline of 9.80%. At the same time, a 90-day share price return of 15.42% and a year-to-date move of 38.80% point to momentum that has been building over a longer stretch.
Spot similar momentum in copper and materials by scanning our hand picked 17 top copper producer stocks.After a sharp run over the past year and with only a narrow gap to analyst targets, the choice is straightforward: step into Freeport-McMoRan at today’s price, or wait for volatility to offer a cheaper entry as the valuation picture unfolds next.
Most Popular Narrative: 1% Undervalued
Freeport-McMoRan’s most followed narrative pegs fair value at $72.59, just above the last close of $72.08. This points to only a slim valuation gap and puts the focus squarely on how its copper projects and policy backdrop play out from here.
Substantial U.S. policy tailwinds, including critical mineral designations, tariffs on imported copper, and ongoing government industry dialogue, are driving premium domestic copper pricing. With Freeport supplying 70% of U.S. refined copper, this premium is adding $1.7 billion in annual EBITDA upside and could structurally lift revenue and profit if these differentials persist or are institutionalized.
See why 104 investors see Freeport-McMoRan as 1% undervalued.
Result: Fair Value of $72.59 (UNDERVALUED)
Still, the story around Freeport-McMoRan can change quickly if Indonesian regulatory terms tighten or if the current U.S. copper price premium fades faster than expected.
Find out about the key risks to this Freeport-McMoRan narrative.
Another View On Freeport-McMoRan’s Valuation
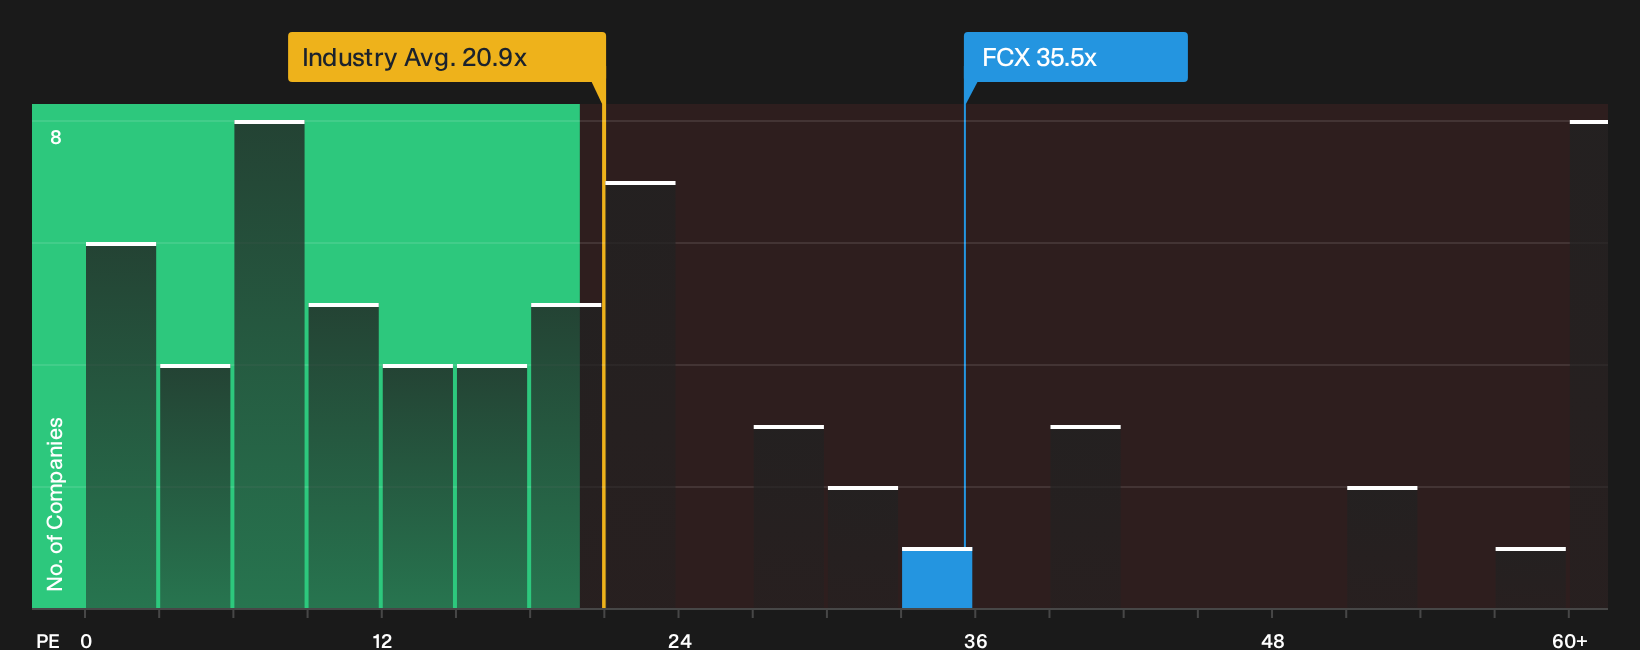
Fair value from the analyst narrative frames Freeport-McMoRan as only slightly undervalued, yet the simple multiples picture looks very different. FCX trades on a P/E of 35.5x versus a fair ratio of 25.6x, peers at 20.4x and the wider US Metals and Mining group at 20.9x, which points to a rich earnings multiple that could compress if sentiment cools.
That spread can look like a quality premium or a valuation risk depending on how much copper upside you are willing to pay for. Which side of that trade are you on? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Freeport-McMoRan’s valuation and sentiment make this a judgment call that rests with you, so move quickly, review the underlying data, weigh both the risks and potential upsides, and then anchor your view in the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Freeport-McMoRan?
If Freeport-McMoRan has you thinking about where to put fresh capital next, use a focused stock screener to spot opportunities that fit your own playbook.
- Target potential upside with a curated 16 high quality undiscovered gems that highlights under-the-radar businesses with strong underlying fundamentals.
- Prioritize resilience by scanning a 30 resilient stocks with low risk scores that surfaces companies with profiles designed to limit nasty surprises.
- Build a sturdier core by filtering for a list of solid balance sheet and fundamentals (23 results) that can help you stress test ideas before committing real money.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com