
LegalZoom.com (LZ) Slides As Meta’s Muse Sparks Questions About Its Valuation
Meta’s Muse AI sparks questions for LegalZoom.com (LZ)
LegalZoom.com (LZ) came under pressure after Meta unveiled its autonomous AI assistant Muse, which some investors believe could change how consumers discover and purchase online legal services.
Recent trading has been rough for LegalZoom.com, with the share price down 2.4% on the day of the Muse headlines. The 7 day and 90 day share price returns have each fallen about 6.9%, while the year to date share price return is down 41.1% and the 1 year total shareholder return has declined 46.7%. This points to fading momentum as investors reassess long term competitive risks rather than reacting to any single company update.
Scan beyond LegalZoom.com and see how other online platforms exposed to AI driven disruption are trading with the curated 16 high quality undiscovered gems.
LegalZoom.com has a long record as an online legal platform, yet the sharp share price slide appears more closely linked to concerns about new AI gateways. Do current levels reflect weakening fundamentals, or are they an overreaction in sentiment as investors reprice that risk?
Most Popular Narrative: 26% Undervalued
LegalZoom.com last closed at $5.65, while the most followed narrative puts fair value at $7.60 using a 7.45% discount rate. This frames the current slide against a longer term cash flow view rather than short term AI headlines.
Robust free cash flow generation and a strengthened balance sheet provide LegalZoom with flexibility to strategically invest in growth initiatives and pursue further M&A, supporting long-term earnings growth.
See why 10 investors see LegalZoom.com as 26% undervalued.
Result: Fair Value of $7.60 (UNDERVALUED)
Still, the narrative around LegalZoom.com can crack if generative AI makes core services easier to copy or if lower subscription retention undercuts the recurring revenue story.
Find out about the key risks to this LegalZoom.com narrative.
Another View on LegalZoom.com’s Valuation
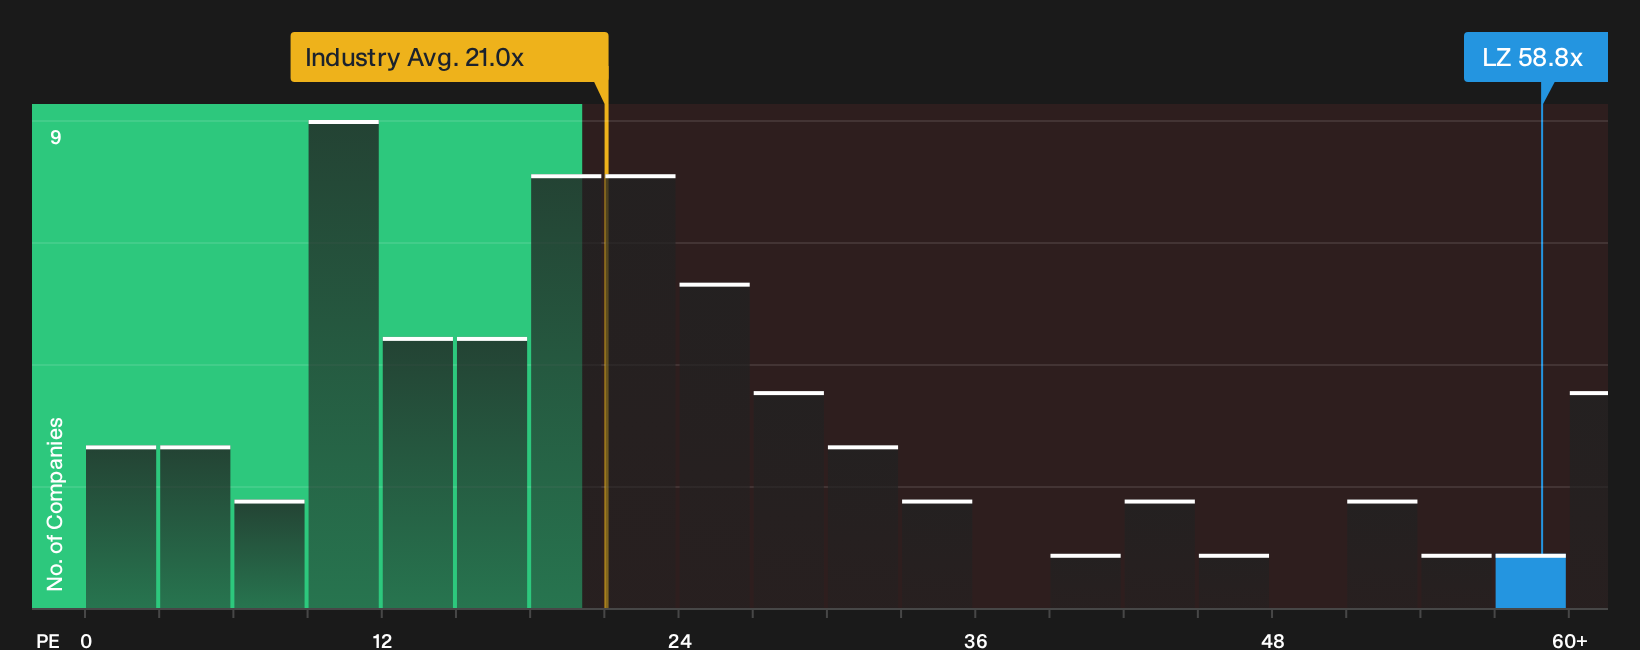
The first story on LegalZoom.com leans on cash flow and a fair value of $7.60. A very different picture appears once the focus shifts to earnings. The stock trades on a P/E of 58.8x, while the US Professional Services peer average is 21.4x and the fair ratio is 36.4x.
That gap suggests investors are already paying a hefty premium for LegalZoom.com relative to both its sector and where the fair ratio implies the multiple could move. This raises a simple question: Is the cash flow upside strong enough to justify that kind of earnings based stretch?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed opinions remain about how LegalZoom.com stacks up after all this. These moves rarely wait for investors to catch up, so weigh the downside and upside for yourself with the full picture in 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond LegalZoom.com?
Do not stop at LegalZoom.com. Fresh ideas often come from comparing it with very different opportunities, and the screener can surface those quickly for you.
- Target durable compounding potential by scanning companies that score well on balance sheet strength and fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality by filtering for companies that pair strong cash generation with attractive valuations using the 29 high quality undervalued stocks.
- Prioritise resilience first by focusing on companies with lower risk characteristics and steadier profiles through the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com